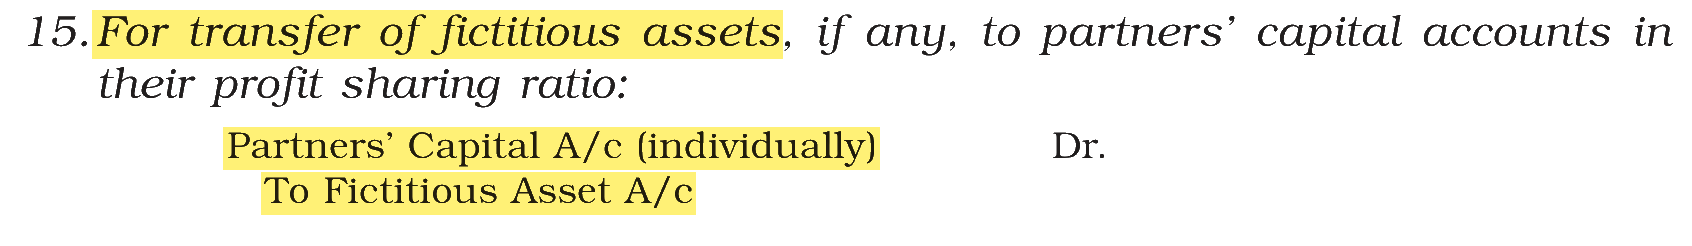
At the time of dissolution of partnership firm, Fictitious assets are transferred to the:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Debit of Partners’ Capital A/c
Fictitious assets (for example, deferred revenue expenditure or a debit balance of the Profit and Loss Account) are losses not yet written off. They have no realisable value, so they are not taken to the Realisation Account; they are written off by debiting the partners’ capital accounts in their profit sharing ratio.
Why the other options are incorrect
Option (1) Credit of Realisation A/c — Incorrect. The credit side of the Realisation Account records liabilities and amounts realised; a fictitious asset realises nothing.
Option (2) Debit of Realisation A/c — Incorrect. Only real assets are transferred there; fictitious assets are left out.
Option (3) Credit of Partners’ Capital A/c — Incorrect. A fictitious asset is an accumulated loss, so it reduces the partners’ capital and is debited.
NCERT (2026-27 edition): NCERT (2026-27 edition):
|