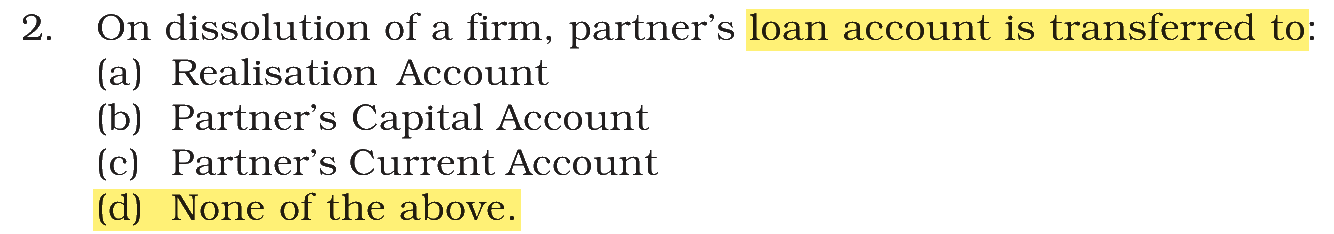For which of the following, situations "No entry" will be passed at the time of Dissolution of firm when all the assets and Liabilities were already transferred.
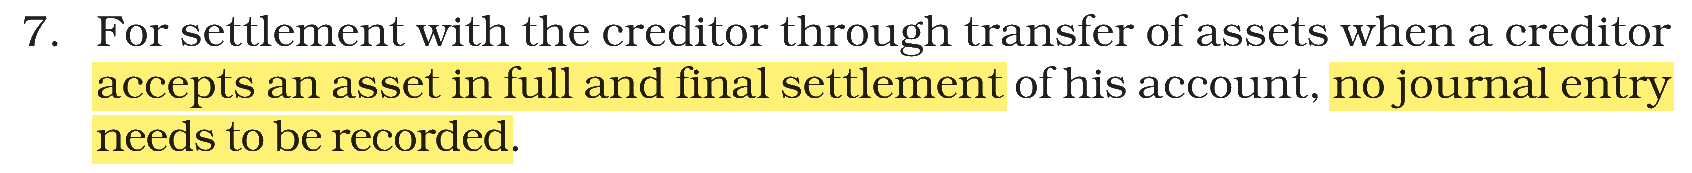
A) Creditors of ₹50,000 were settled by giving stock of ₹60,000 in full settlement.
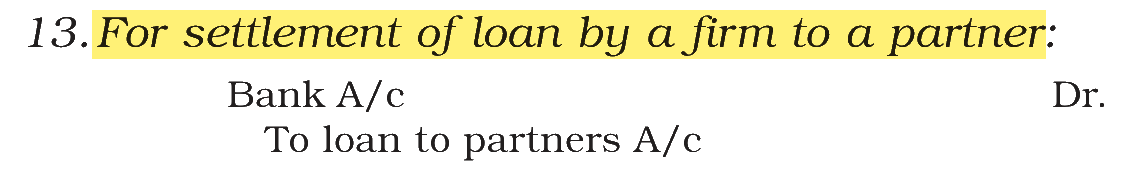
B) Loan to B of ₹60,000 was settled at ₹55,000 (B is a partner).
C) Realisation expense amounted to ₹5,000. Debtor of ₹8,000 paid these expenses in full settlement
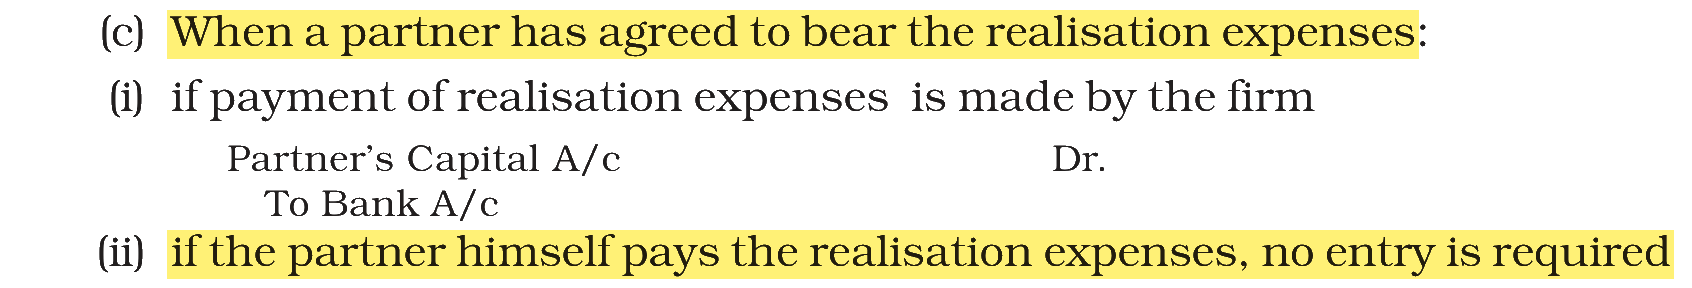
D) Realisation expenses amounted to ₹10,000 were to be borne by C, a partner and were paid by him personally.
E) A's Loan to firm of ₹25,000 was settled by giving him furniture of same amount
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → A, C and D only
Once all assets and outside liabilities are in the Realisation Account, no entry is needed when a settlement involves no cash and no partner’s account.
(A) Creditors of ₹50,000 were settled by giving stock of ₹60,000 in full settlement — True. A creditor who accepts an asset in full settlement needs no journal entry; both items already sit in the Realisation Account.
(B) Loan to B of ₹60,000 was settled at ₹55,000 (B is a partner) — False. A loan to a partner is settled through an entry (cash received or his capital account adjusted).
(C) Realisation expense amounted to ₹5,000. Debtor of ₹8,000 paid these expenses in full settlement — True. The debtor is settled without any cash reaching the firm and the expense is paid without the firm paying cash, so nothing passes through the books.
(D) Realisation expenses amounted to ₹10,000 were to be borne by C, a partner and were paid by him personally — True. When the partner who bears the expenses pays them himself, no entry is required.
(E) A’s Loan to firm of ₹25,000 was settled by giving him furniture of same amount — False. A partner’s loan is not transferred to the Realisation Account, so its settlement with an asset needs an entry (A’s Loan A/c Dr. To Realisation A/c).
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|