Match List I with List II.
|
List - I |
List - II |
|
(A) Asset taken over by partner |
(I) Partner's capital A/c Dr |
|
(B) Realisation expenses |
(II) Partner's capital A/c Dr |
|
(C) Liabilities met by partner |
(III) Realisation A/c Dr |
|
(D) Realisation Expenses paid on behalf of partner by firm |
(IV) Realisation A/c Dr |
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A)-(II), (B)-(IV), (C)-(III), (D)-(I)
On dissolution, every transaction with assets and outside liabilities passes through the Realisation Account; a partner who takes or pays something on the firm’s behalf is adjusted through his capital account.
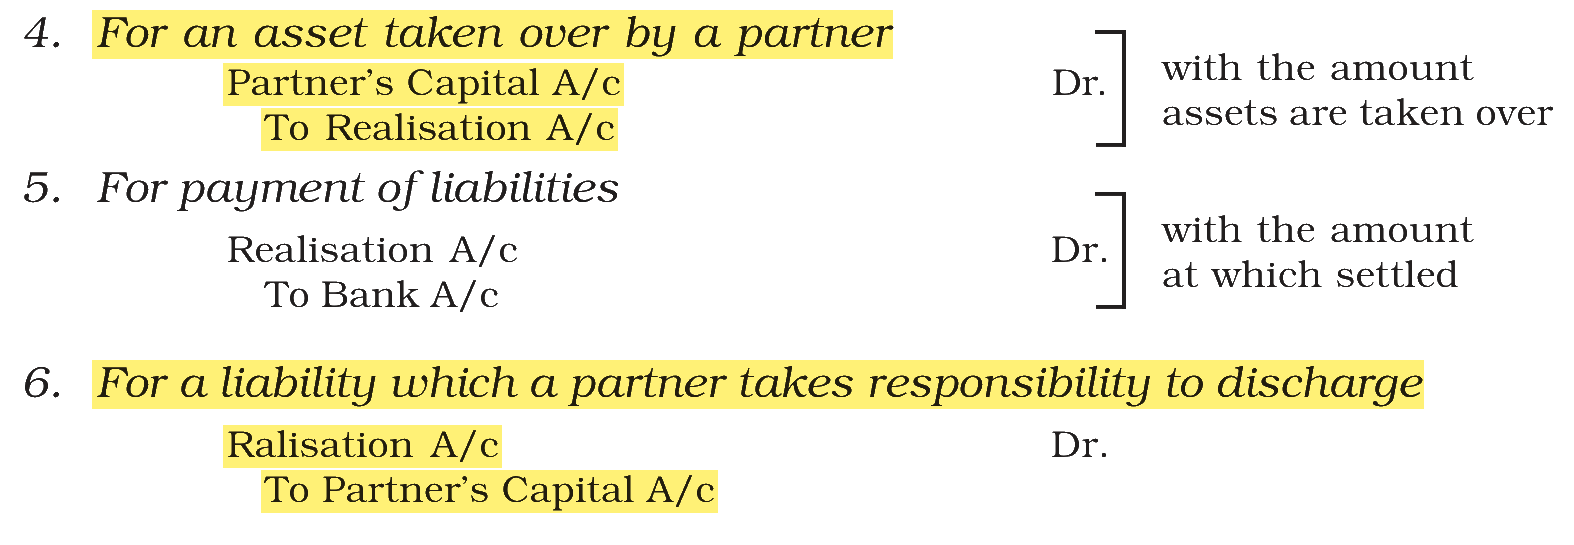
(A) Asset taken over by partner — this matches (II) Partner's capital A/c Dr To realisation A/c. The partner pays for the asset by a debit to his capital.
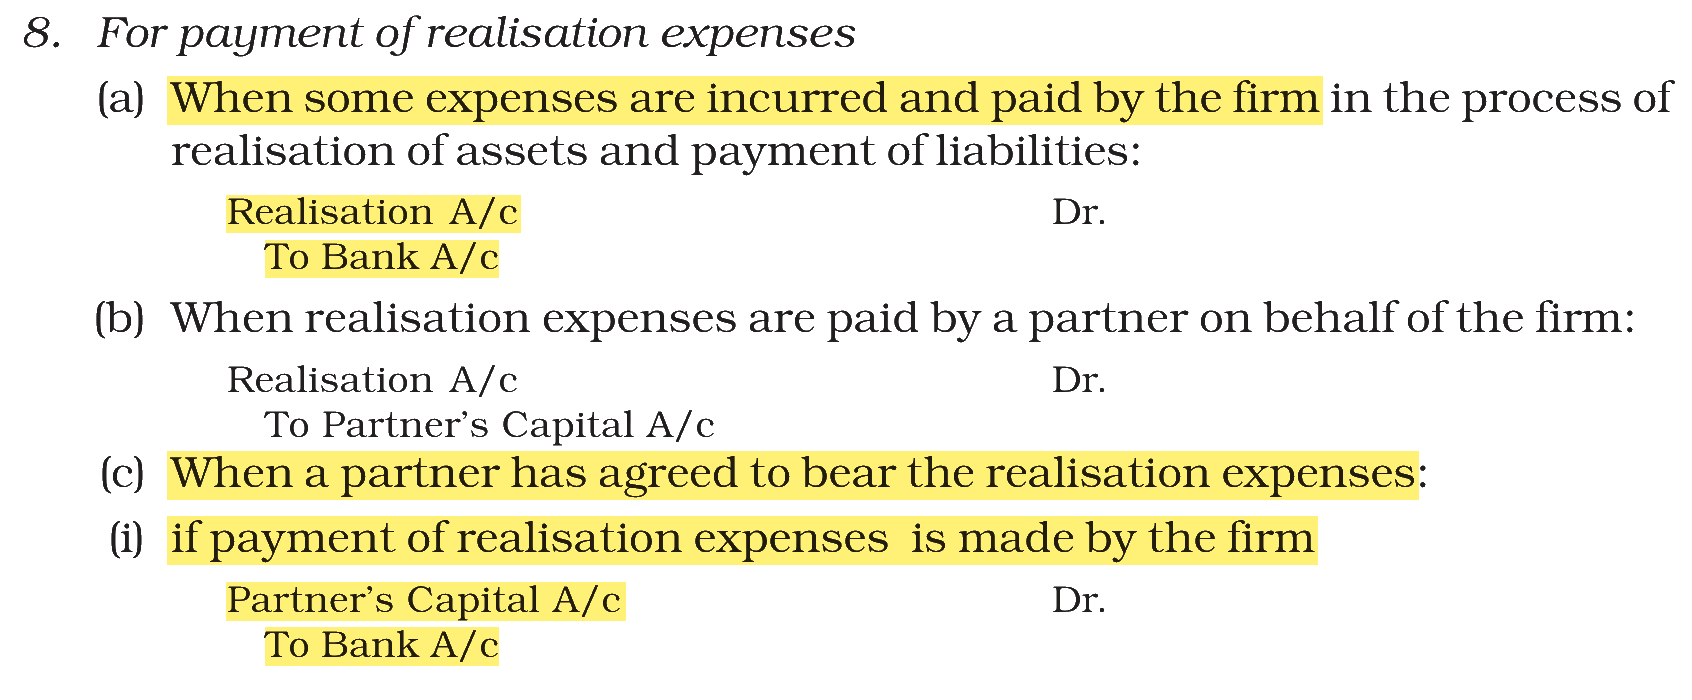
(B) Realisation expenses — this matches (IV) Realisation A/c Dr To cash A/c. The firm bears and pays its own realisation expenses.
(C) Liabilities met by partner — this matches (III) Realisation A/c Dr To partners capital A/c. The partner is credited for the liability he settles.
(D) Realisation Expenses paid on behalf of partner by firm — this matches (I) Partner's capital A/c Dr To cash A/c. The expense is the partner’s own, so it is charged to his capital, not to the Realisation Account.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|