Read the following case study and answer the question:
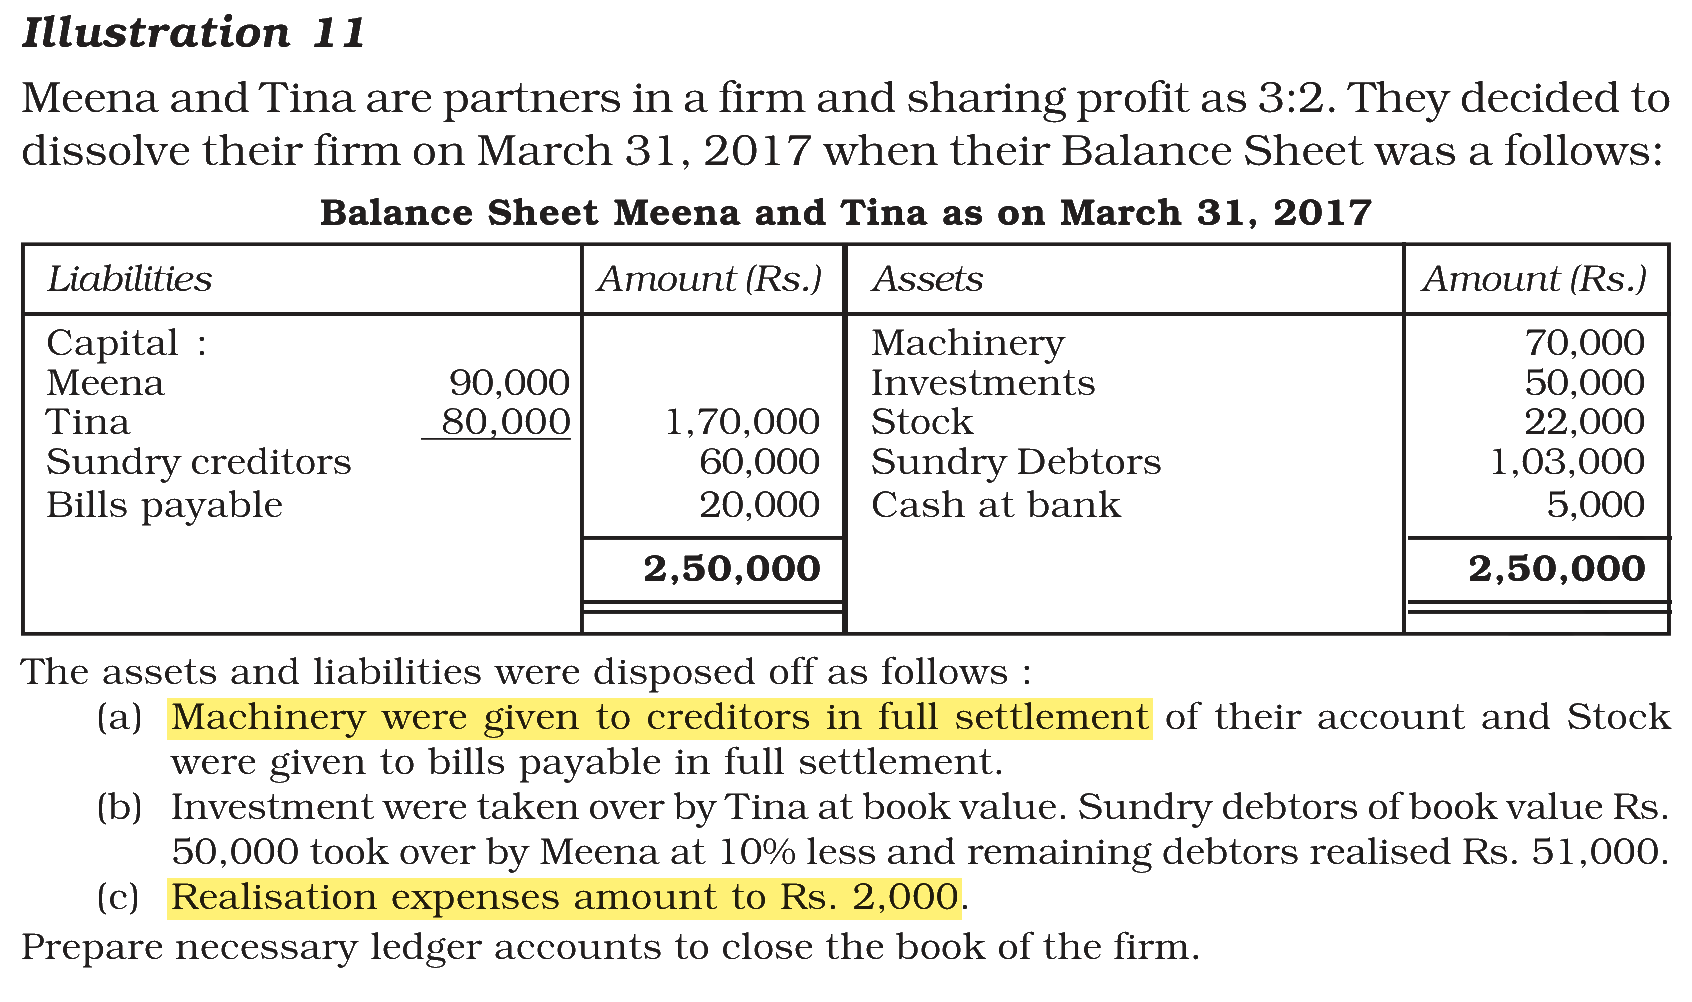
Naina and Nayantara are Partners in a firm, sharing profits in ratio 3 : 2. They decided to dissolve their firm on 31, March 2021 when their Balance-Sheet was as follows:
|
Liabilities |
Amt. (₹) |
Assets |
Amt. (₹) |
|
Capital: Naina 1,00,000 Nayantara 80,000 Creditors Bills Payable |
1,80,000 60,000 20,000 |
Machinery Investment Stock Debtors Cash at Bank |
80,000 50,000 22,000 1,03,000 5,000 |
|
|
2,60,000 |
|
2,60,000 |
The Assets and liabilities were disposed off as follows:
(a) Machinery was given to creditors in full settlement of their amount and stock was given to Bills Payable in full settlement.
(b) Investment were taken over by Nayantara at book value.
(c) Debtors of book value ₹50,000 taken over by Naina at 10% less and remaining debtors realised ₹51,000.
(d) Realisation expenses amounted to ₹5,000.
Amount of Profit/Loss on Realisation is:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → ₹ 34,000 Loss
The Realisation Account is debited with the assets transferred and the expenses paid, and credited with the liabilities transferred and what the assets fetch. A debit balance is a loss on realisation.
Debit side:
Machinery ₹80,000 + Investment ₹50,000 + Stock ₹22,000 + Debtors ₹1,03,000 = ₹2,55,000
Add: Realisation expenses = ₹5,000
Total = ₹2,60,000
Credit side:
Creditors = ₹60,000
Bills payable = ₹20,000
Nayantara’s Capital (investment) = ₹50,000
Naina’s Capital (debtors, ₹50,000 less 10%) = ₹45,000
Bank (remaining debtors) = ₹51,000
Total = ₹2,26,000
Loss on realisation = ₹2,60,000 − ₹2,26,000 = ₹34,000
The loss is shared 3 : 2, so Naina bears ₹20,400 and Nayantara ₹13,600; these two shares appear as options but are not the loss itself.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|