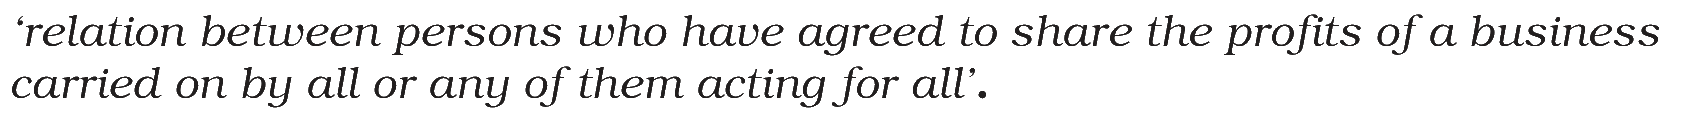Match List-I with List-II
| List-I | List-II | ||
| (A) | Intangible assets should be written off as early as possible but not exceeding its estimated life in ......... years | (I) | 4 |
| (B) | AS .....deals with intangible assets | (II) | 10 |
| (C) | In the absence of any agreement, Section ...... of the Indian Partnership Act, 1932 is applicable, which states that the retiring partner has an option to receive either interest @ 6% p.a. till the date of payment or such share of profits which has been earned with his/her money (i.e., based on capital ratio). | (III) | 26 |
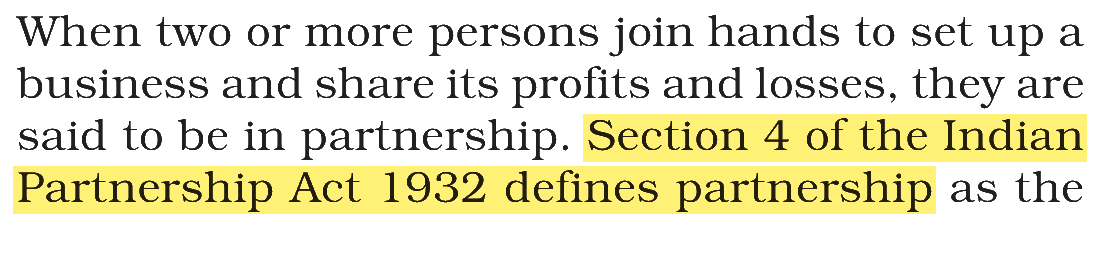
| (D) | Section ...... of the Indian Partnership Act 1932 defines partnership. | (IV) | 37 |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A) - (II), (B) - (III), (C) - (IV), (D) - (I)
Each blank is a number from the law or from an Accounting Standard.
(A) Intangible assets should be written off … not exceeding its estimated life in … years — this matches (II) 10. AS 26 limits the estimated life of an intangible asset, normally, to 10 years.
(B) AS … deals with intangible assets — this matches (III) 26. AS 26 is the Accounting Standard on Intangible Assets.
(C) Section … of the Indian Partnership Act, 1932 (retiring partner’s option of 6% interest or a share of profits) — this matches (IV) 37. Section 37 gives the outgoing partner his choice between interest and a share of profits.
(D) Section … of the Indian Partnership Act 1932 defines partnership — this matches (I) 4. The definition of partnership is in Section 4.
NCERT (2026-27 edition):
NCERT (2026-27 edition): NCERT (2026-27 edition):
|