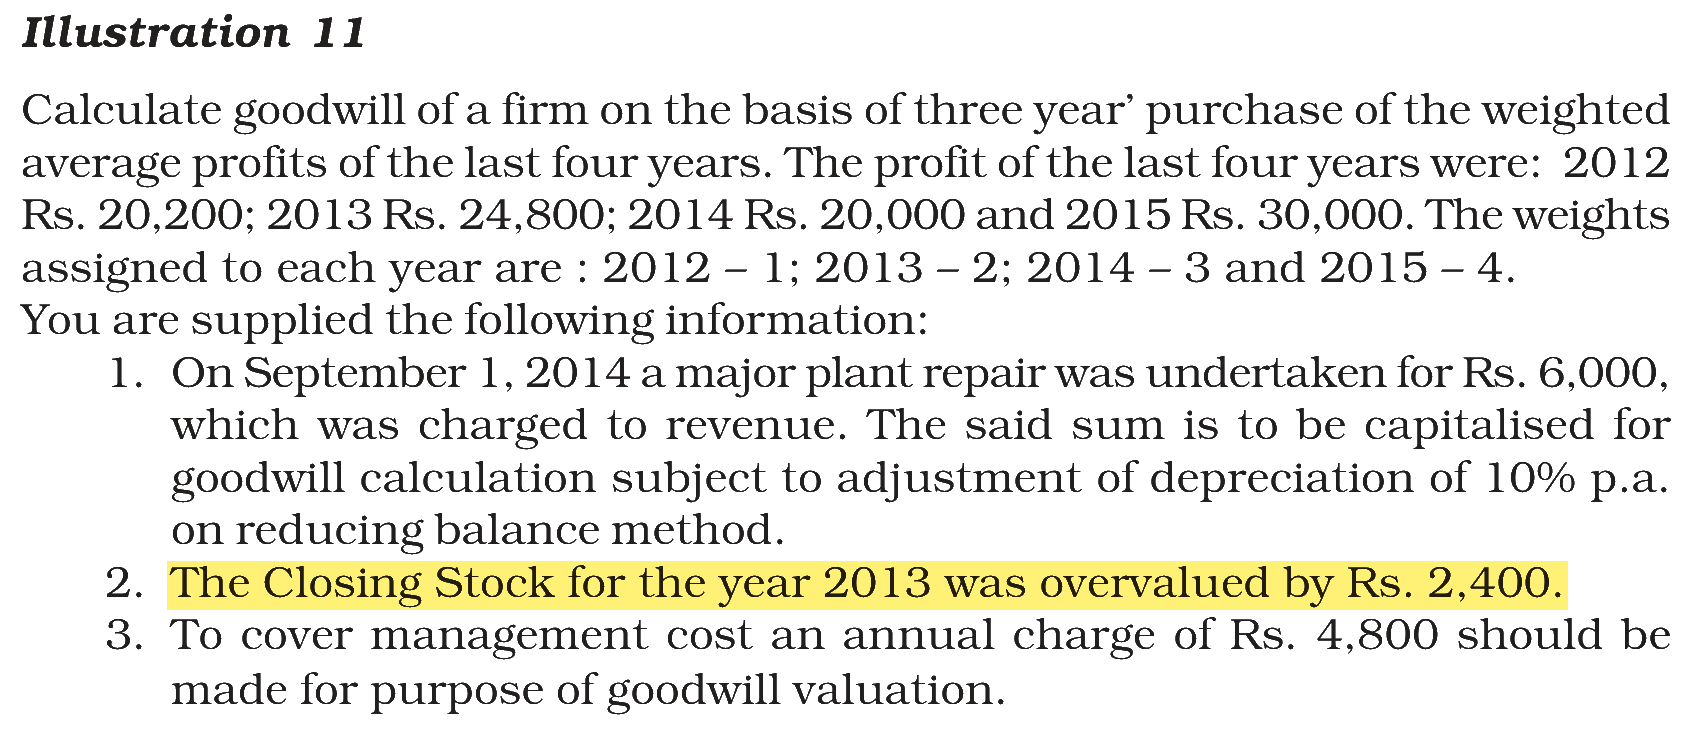
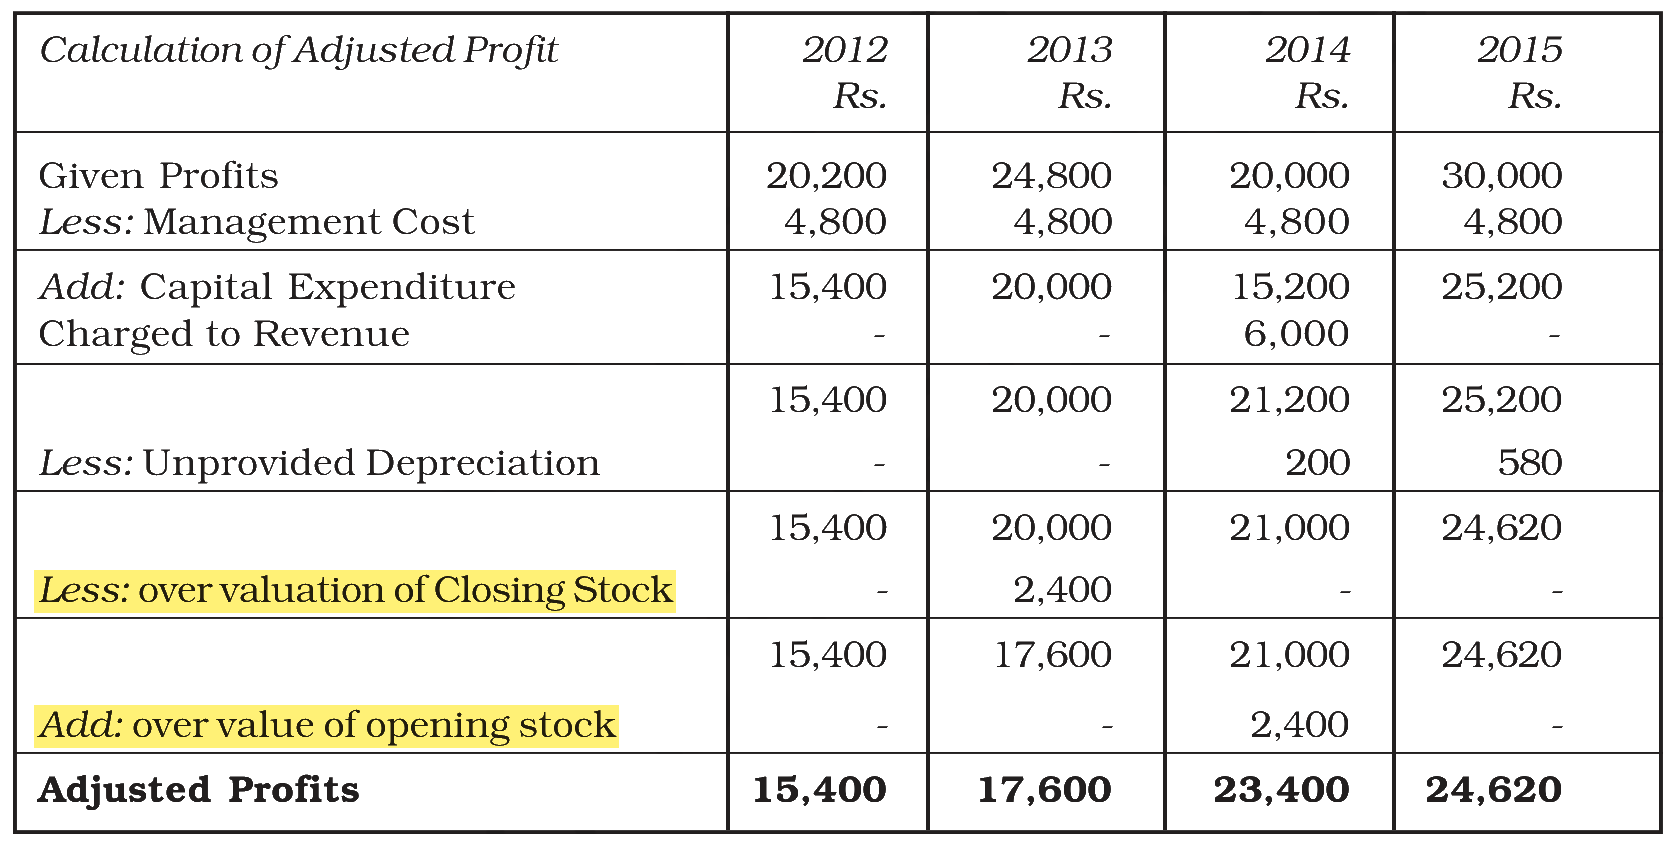
The adjustment required for overvaluation of closing stock, while calculating adjusted profit for calculating goodwill is:
(A) Reduction from concerned year's profit
(B) Reduction from next year's profit
(C) Addition to next year's profit
(D) Addition to previous year's profit
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A) and (C) only
Closing stock of one year is the opening stock of the next year. An overvalued closing stock therefore raises the profit of that year and, because the same figure becomes the opening stock, lowers the profit of the next year by the same amount.
(A) Reduction from concerned year’s profit Correct. The excess value has inflated that year’s profit, so it is deducted.
(B) Reduction from next year’s profit Incorrect. The next year’s profit is understated (its opening stock is too high), so nothing is deducted from it.
(C) Addition to next year’s profit Correct. The overvalued opening stock reduced the next year’s profit, so the amount is added back.
(D) Addition to previous year’s profit Incorrect. The previous year’s profit does not include this stock at all.
NCERT (2026-27 edition):
|