Match List-I with List-II
|
List-I |
List-II |
|
(A) Bank (fresh capital introduced) |
(I) Debit side of Partner's Current Account |
|
(B) Interest on drawings |
(II) Debit side of Partner's Capital Account |
|
(C) Bank (permanent withdrawal of capital) |
(III) Credit side of Partner's Current Account |
|
(D) Commission |
(IV) Credit side of Partner's Capital Account |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 1
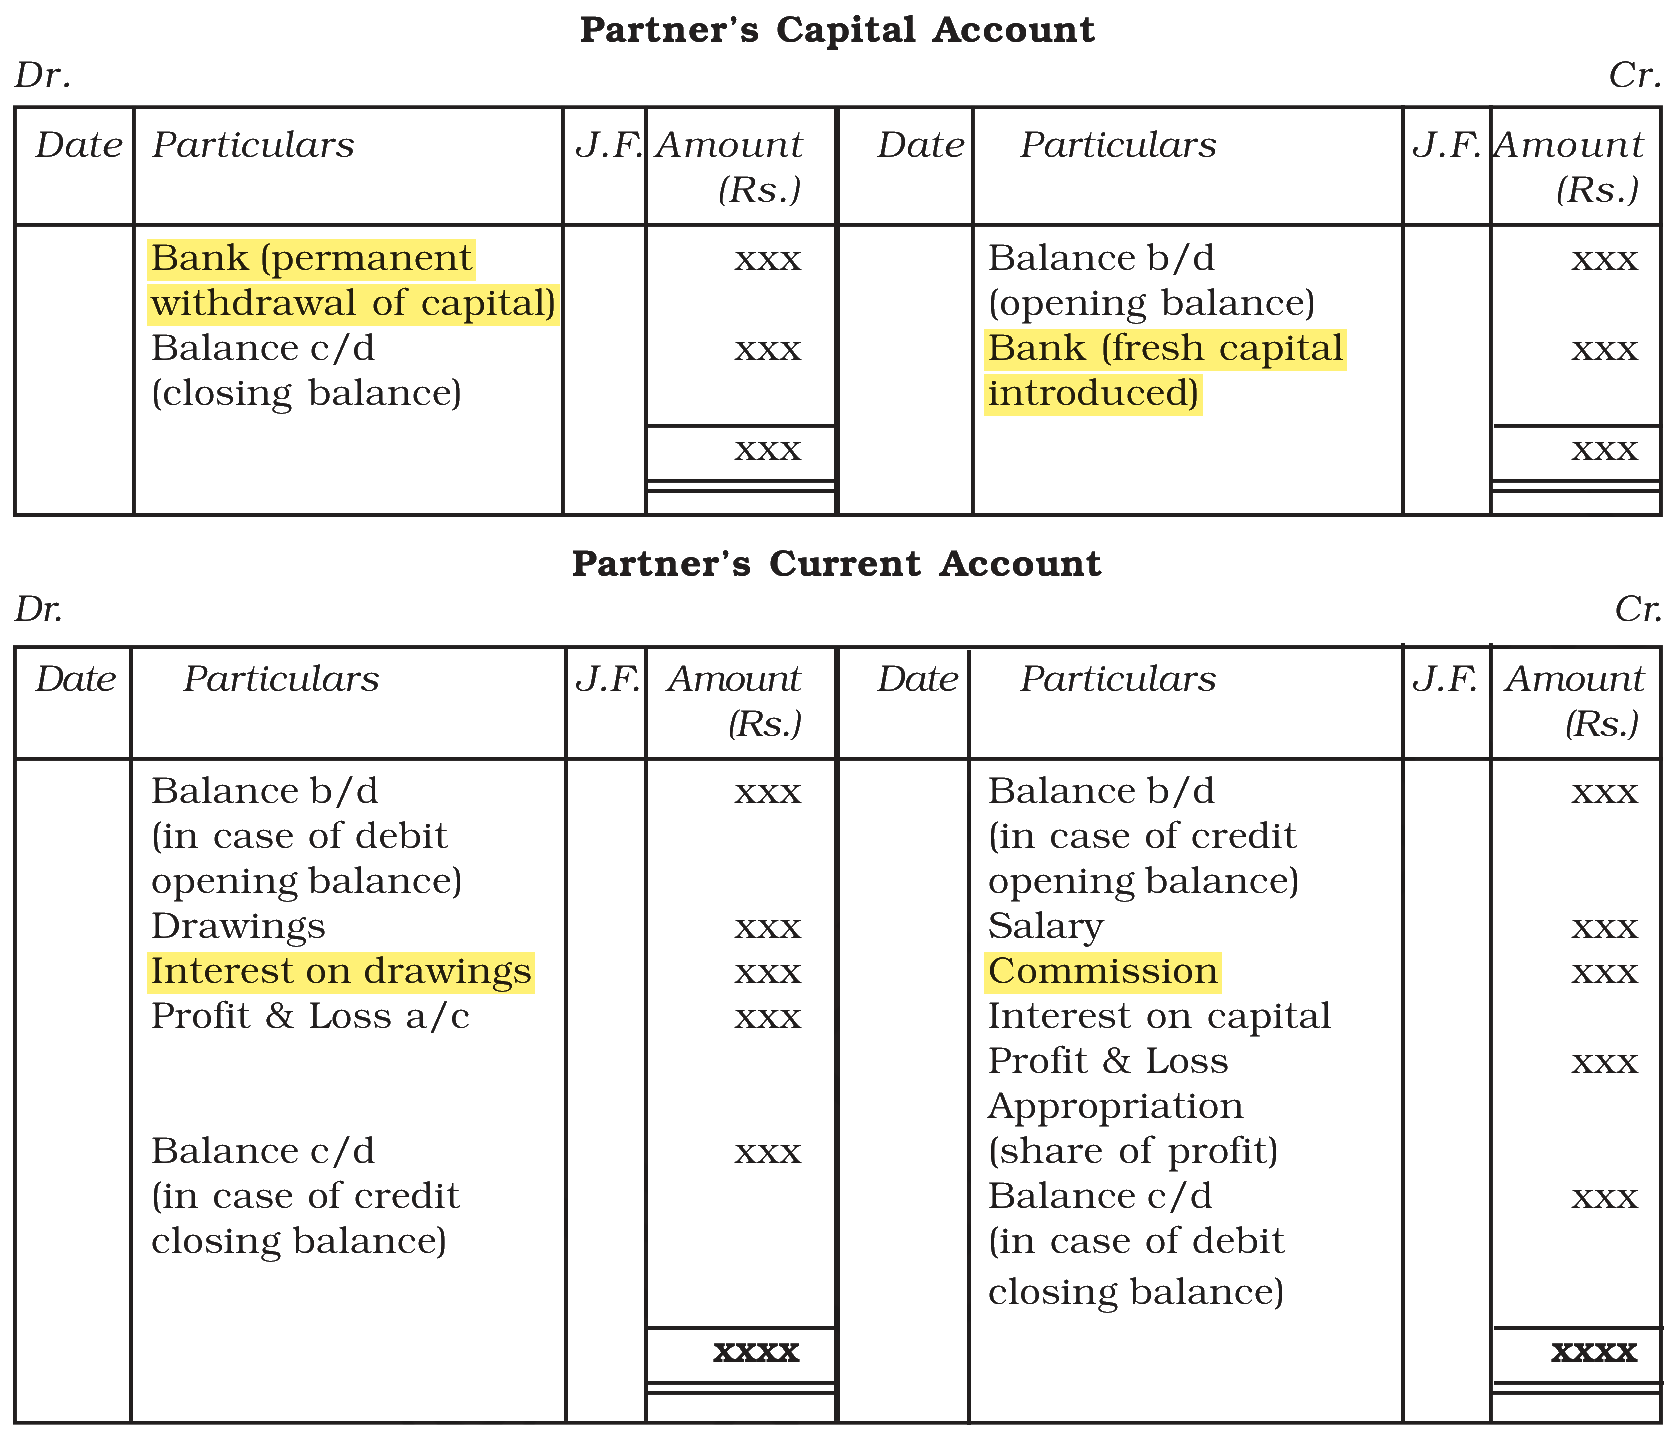
The correct answer is Option (1) → (A)-(IV), (B)-(I), (C)-(II), (D)-(III)
Under the fixed capital method the capital account records only permanent changes in capital; every other item between the partner and the firm goes to the current account.
(A) Bank (fresh capital introduced) — this matches (IV) Credit side of Partner’s Capital Account. Fresh capital is a permanent addition, so it is credited to the capital account.
(B) Interest on drawings — this matches (I) Debit side of Partner’s Current Account. It is a charge on the partner, recorded in the current account.
(C) Bank (permanent withdrawal of capital) — this matches (II) Debit side of Partner’s Capital Account. A permanent withdrawal reduces the fixed capital.
(D) Commission — this matches (III) Credit side of Partner’s Current Account. Commission is the partner’s earning from the firm, so it is credited to the current account.
NCERT (2026-27 edition):
|