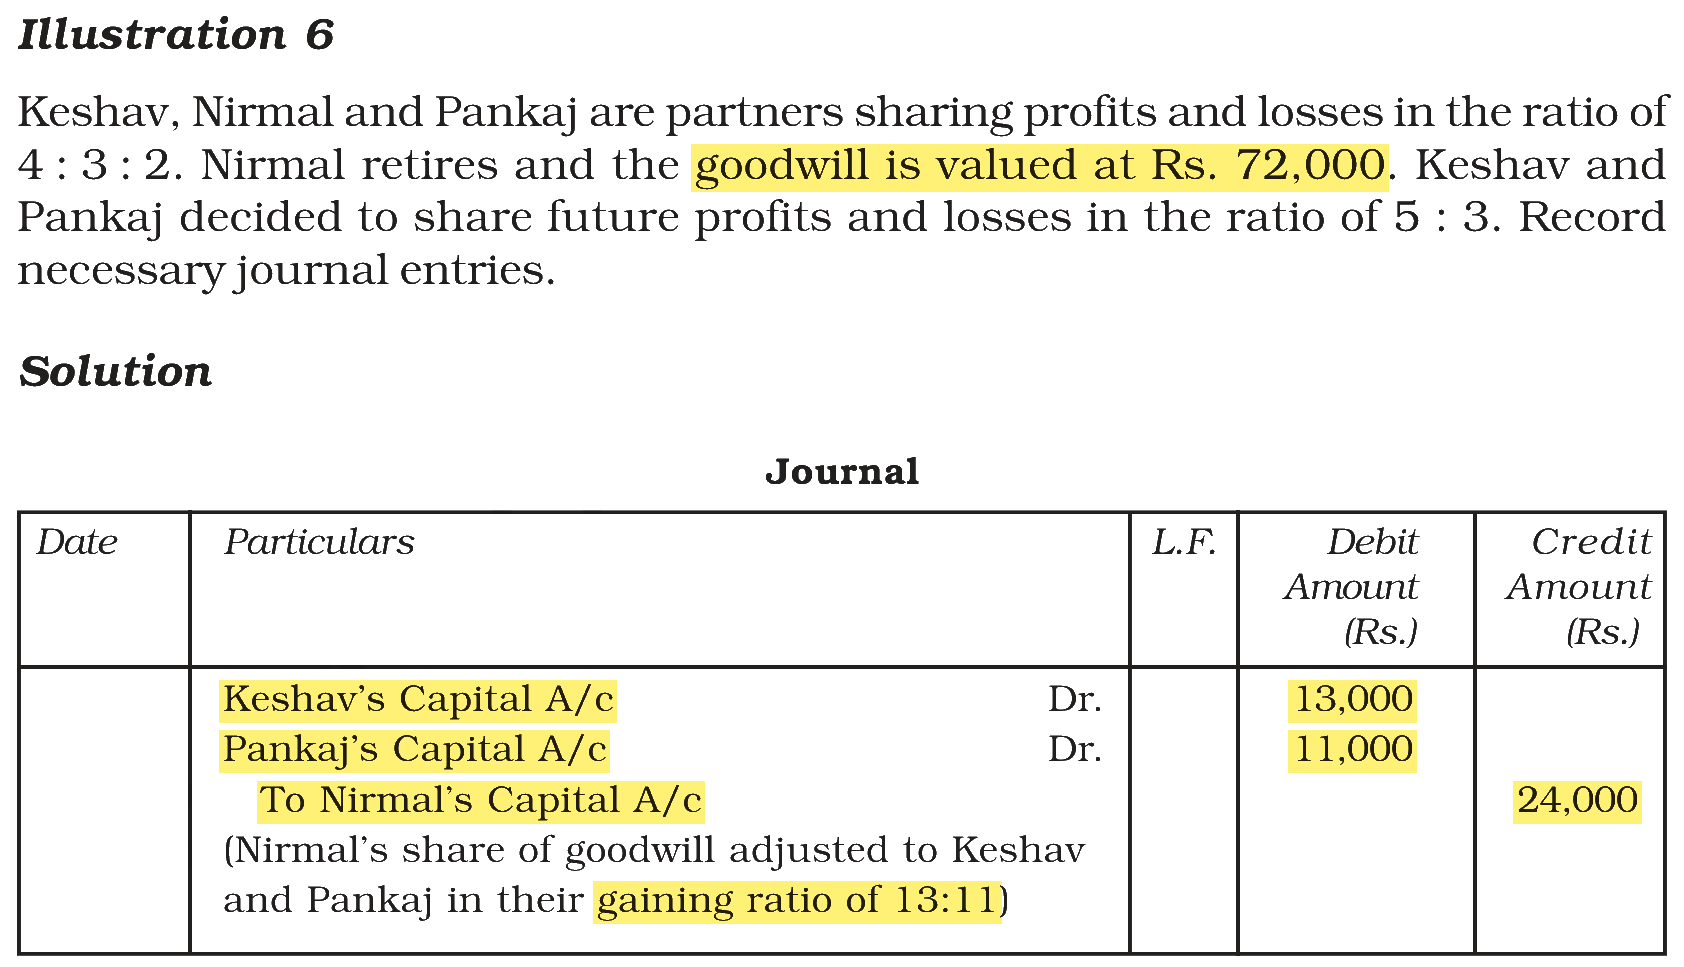
Karan, Neha and Pankaj are partners sharing profits and losses in the ratio of 4 : 3 : 2. Neha retires and goodwill of the firm is valued at Rs. 72,000. Karan and Pankaj decided to share future profits and losses in the ratio of 5 : 3. The journal entry for adjustment of goodwill will be:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Karan's Capital A/c Dr. 13,000 and Pankaj's Capital A/c Dr. 11,000, To Neha's Capital A/c 24,000
When a partner retires, the continuing partners take over her share of future profits, so they pay her for her share of goodwill. Each one pays in the proportion of what he gains, that is, in the gaining ratio (new share − old share), not in the new profit sharing ratio.
Neha's share of goodwill:
Neha's share = 3/9
Neha's share of goodwill = Rs. 72,000 × 3/9 = Rs. 24,000
Gaining ratio (common denominator 72):
Karan: new 5/8 = 45/72, old 4/9 = 32/72
Karan's gain = 45/72 − 32/72 = 13/72
Pankaj: new 3/8 = 27/72, old 2/9 = 16/72
Pankaj's gain = 27/72 − 16/72 = 11/72
Gaining ratio = 13 : 11
Amount each gaining partner pays:
Karan = Rs. 24,000 × 13/24 = Rs. 13,000
Pankaj = Rs. 24,000 × 11/24 = Rs. 11,000
In the book’s version Keshav and Nirmal stand for Karan and Neha; the figures and the entry are the same.
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|