Read the following information to answer.
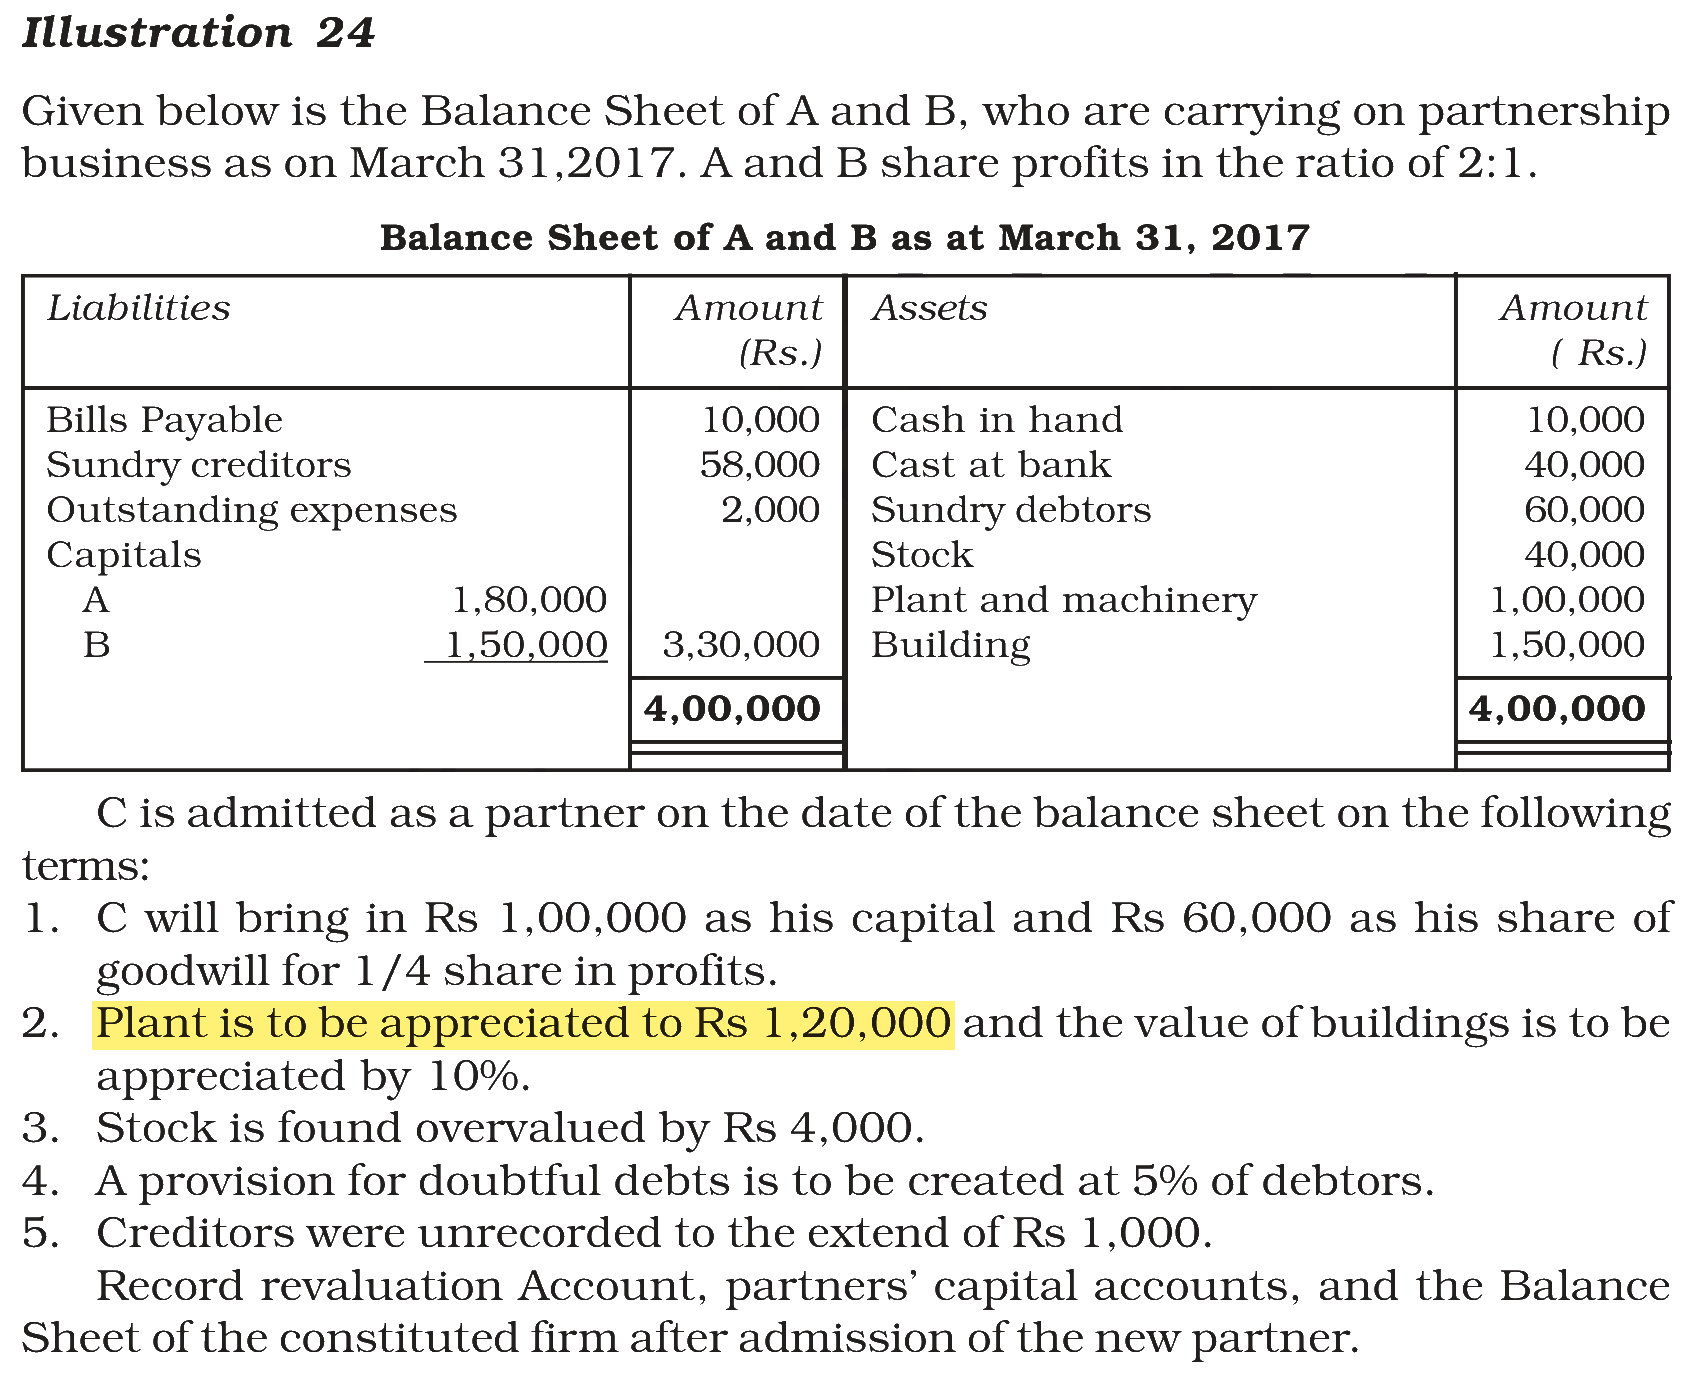
A and B are two partners, dealing in manufacturing steel, sharing profits in the ratio of 2 : 1. They enjoying a buoyant demand of its products as economic growth is about 7% - 8% and the demand for steel is growing. It is planned to set up a new steel plant to encash on the increasing demand. It is estimated that they will require about Rs. 1,00,000. So they admitted, C as a partner. On the date of admission Balance sheet is as follows.
Balance Sheet of A and B
| Liabilities | Rs. | Assets | Rs. |
|---|---|---|---|
| Bills Payable | 10,000 | Cash in hand | 10,000 |
| Sundry creditor | 58,000 | Cash at bank | 40,000 |
| Outstanding Expenses | 2,000 | Sundry Debtors | 60,000 |
| Capital | 3,30,000 | Stock | 40,000 |
| A - 1,80,000 | Plant and Machinery | 1,00,000 | |
| B - 1,50,000 | Building | 1,50,000 | |
| 4,00,000 | 4,00,000 |
Other information :
1. C will bring in Rs. 1,00,000 as capital and Rs. 60,000 as his share of goodwill for \( \displaystyle\frac{1}{4} \) share in profit.
2. Plant is to be appreciated to Rs. 1,20,000 and the value of building is to be appreciated by 10%.
3. Stock is found overvalued by Rs. 4,000.
4. A provision for doubtful debts is to be created at 5% of debtors.
5. Creditors were unrecorded to the extent of Rs. 1,000.
On the basis of above case study, answer the following :
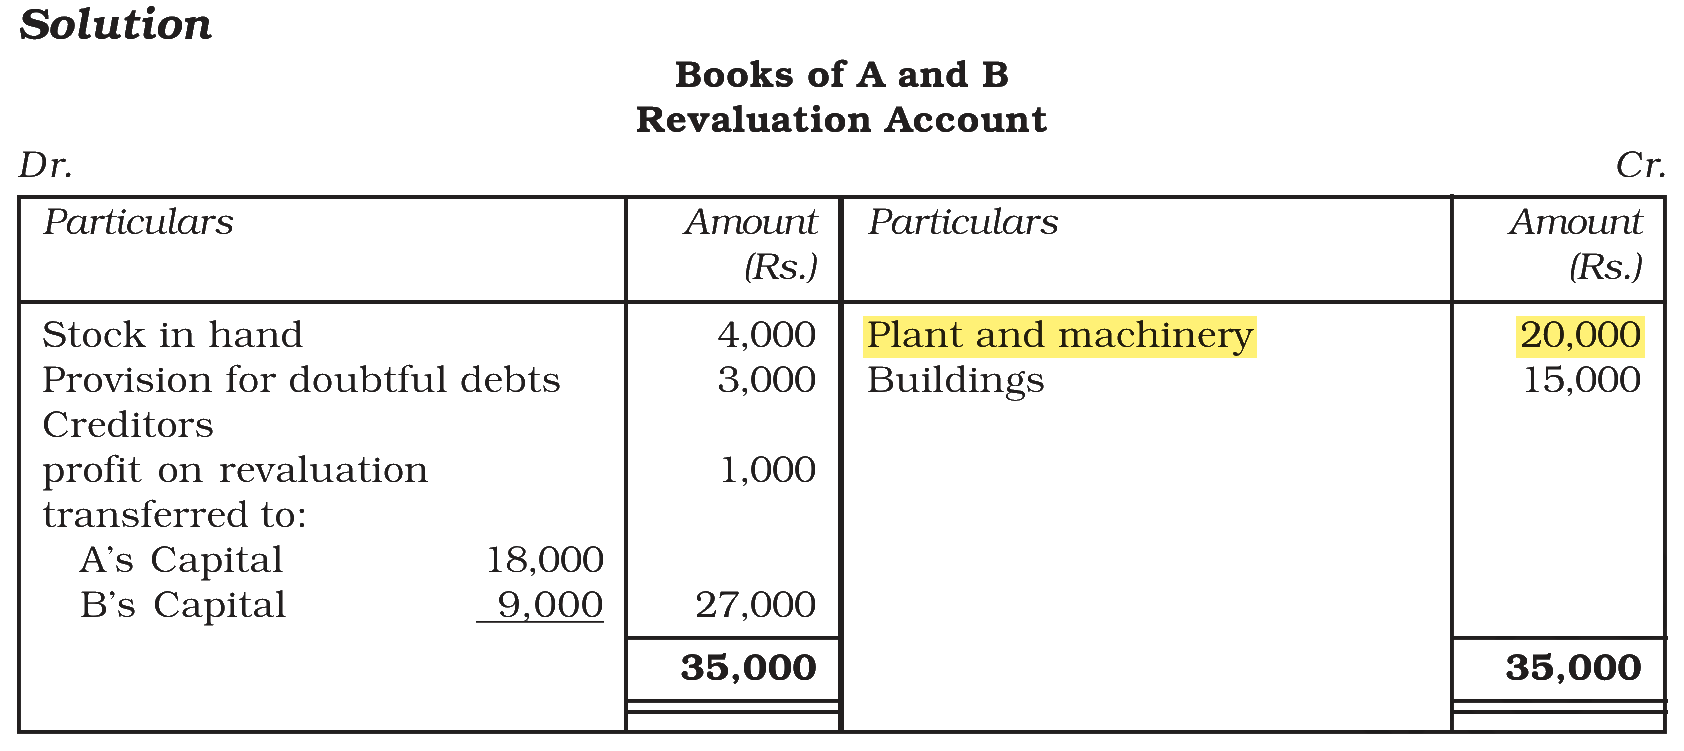
Plant and Machinery to be shown in Revaluation Account :
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Rs. 20,000
The Revaluation Account records only the change in the value of an asset, not its full new value. A rise in the value of plant is a gain, so the increase is credited to the Revaluation Account.
Revised value of plant and machinery = Rs. 1,20,000
Book value = Rs. 1,00,000
Increase credited to Revaluation Account = Rs. 1,20,000 − Rs. 1,00,000 = Rs. 20,000
The new value of Rs. 1,20,000 is the figure shown in the balance sheet after admission, not in the Revaluation Account.
NCERT (2026-27 edition):
|