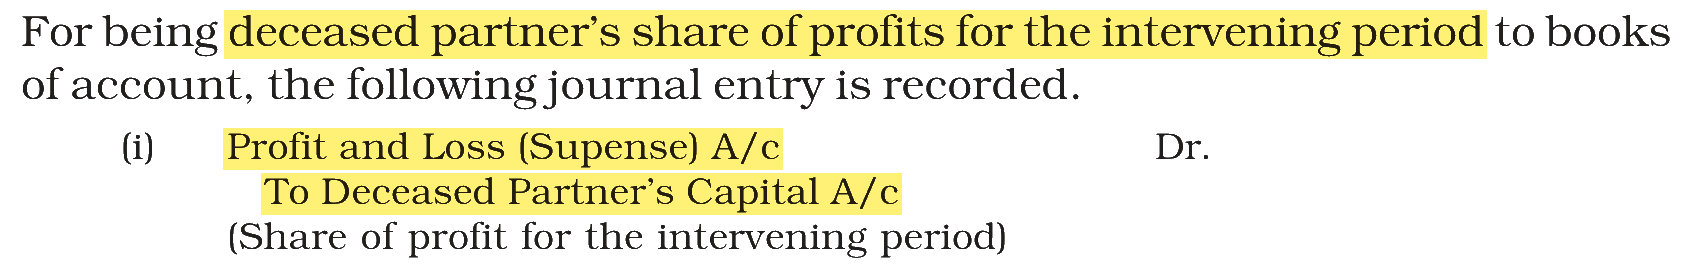
In case, deceased partner's share of profit is calculated during the intervening period, the following Journal Entry will be passed :-
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Profit and Loss Suspense A/c Dr., To Deceased Partner's Capital A/c
When a partner dies during the year, the books are not closed on that date. His share of profit from the last balance sheet to the date of death is estimated and credited to his capital account, and the debit goes to a temporary Profit and Loss Suspense Account:
Profit and Loss Suspense A/c Dr.
To Deceased Partner's Capital A/c
At the year end the suspense account is closed by transfer to the remaining partners in their gaining ratio, because they bear the payment.
Option (1) Remaining Partners' Capital A/c Dr. To Profit and Loss Suspense A/c — Incorrect. This is the later entry that closes the suspense account, not the entry that records the deceased partner's share.
Option (2) Old Partners' Capital A/c Dr. To Profit and Loss Suspense A/c — Incorrect. This too is a closing entry for the suspense account, and it names the wrong partners: the suspense account is closed to the gaining partners, and in any case it gives the deceased partner nothing.
Option (3) Deceased Partner's Capital A/c Dr. To Profit and Loss Suspense A/c — Incorrect. It reverses the entry: debiting the deceased partner's capital would take his share away instead of giving it to him.
NCERT (2026-27 edition):
|