Select the correct statements from the following:
(A) Realisation Account is prepared at the time of death of a partner.
(B) Revaluation Account is prepared at the time of dissolution of a firm.
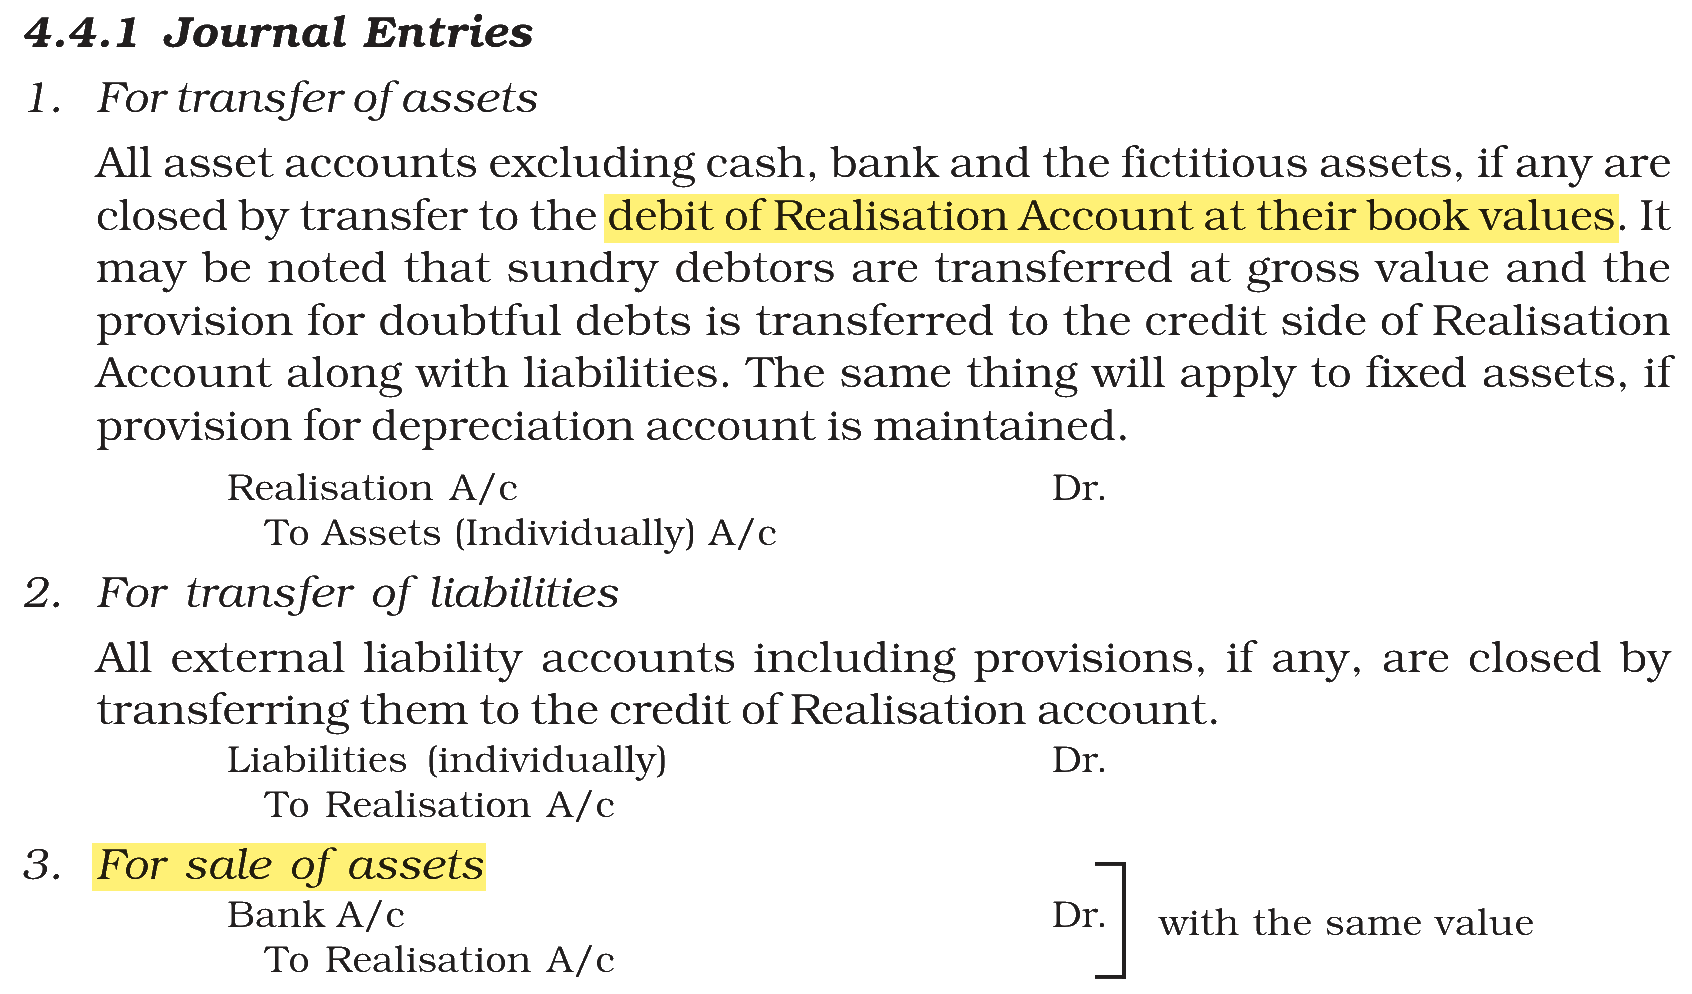
(C) At the time of dissolution, the Book Value of Assets are transferred to the Debit Side of the Realisation Account.
(D) At the time of dissolution, the Realised value of Assets are transferred to the Credit Side of the Realisation Account.
Choose a pair of correct statements from the given options below:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → (C) and (D) only
(A) Realisation Account is prepared at the time of death of a partner. Incorrect. On the death of a partner the firm goes on, so assets and liabilities are revalued through a Revaluation Account. A Realisation Account is opened only when the firm itself is dissolved.
(B) Revaluation Account is prepared at the time of dissolution of a firm. Incorrect. On dissolution the assets are actually sold and the liabilities paid, which is recorded in a Realisation Account. Revaluation is for a firm that continues.
(C) At the time of dissolution, the Book Value of Assets are transferred to the Debit Side of the Realisation Account. Correct. The assets leave the books at the values they carry there.
(D) At the time of dissolution, the Realised value of Assets are transferred to the Credit Side of the Realisation Account. Correct. What the assets fetch is credited, so the two sides together show the profit or loss on realisation.
NCERT (2026-27 edition):
|