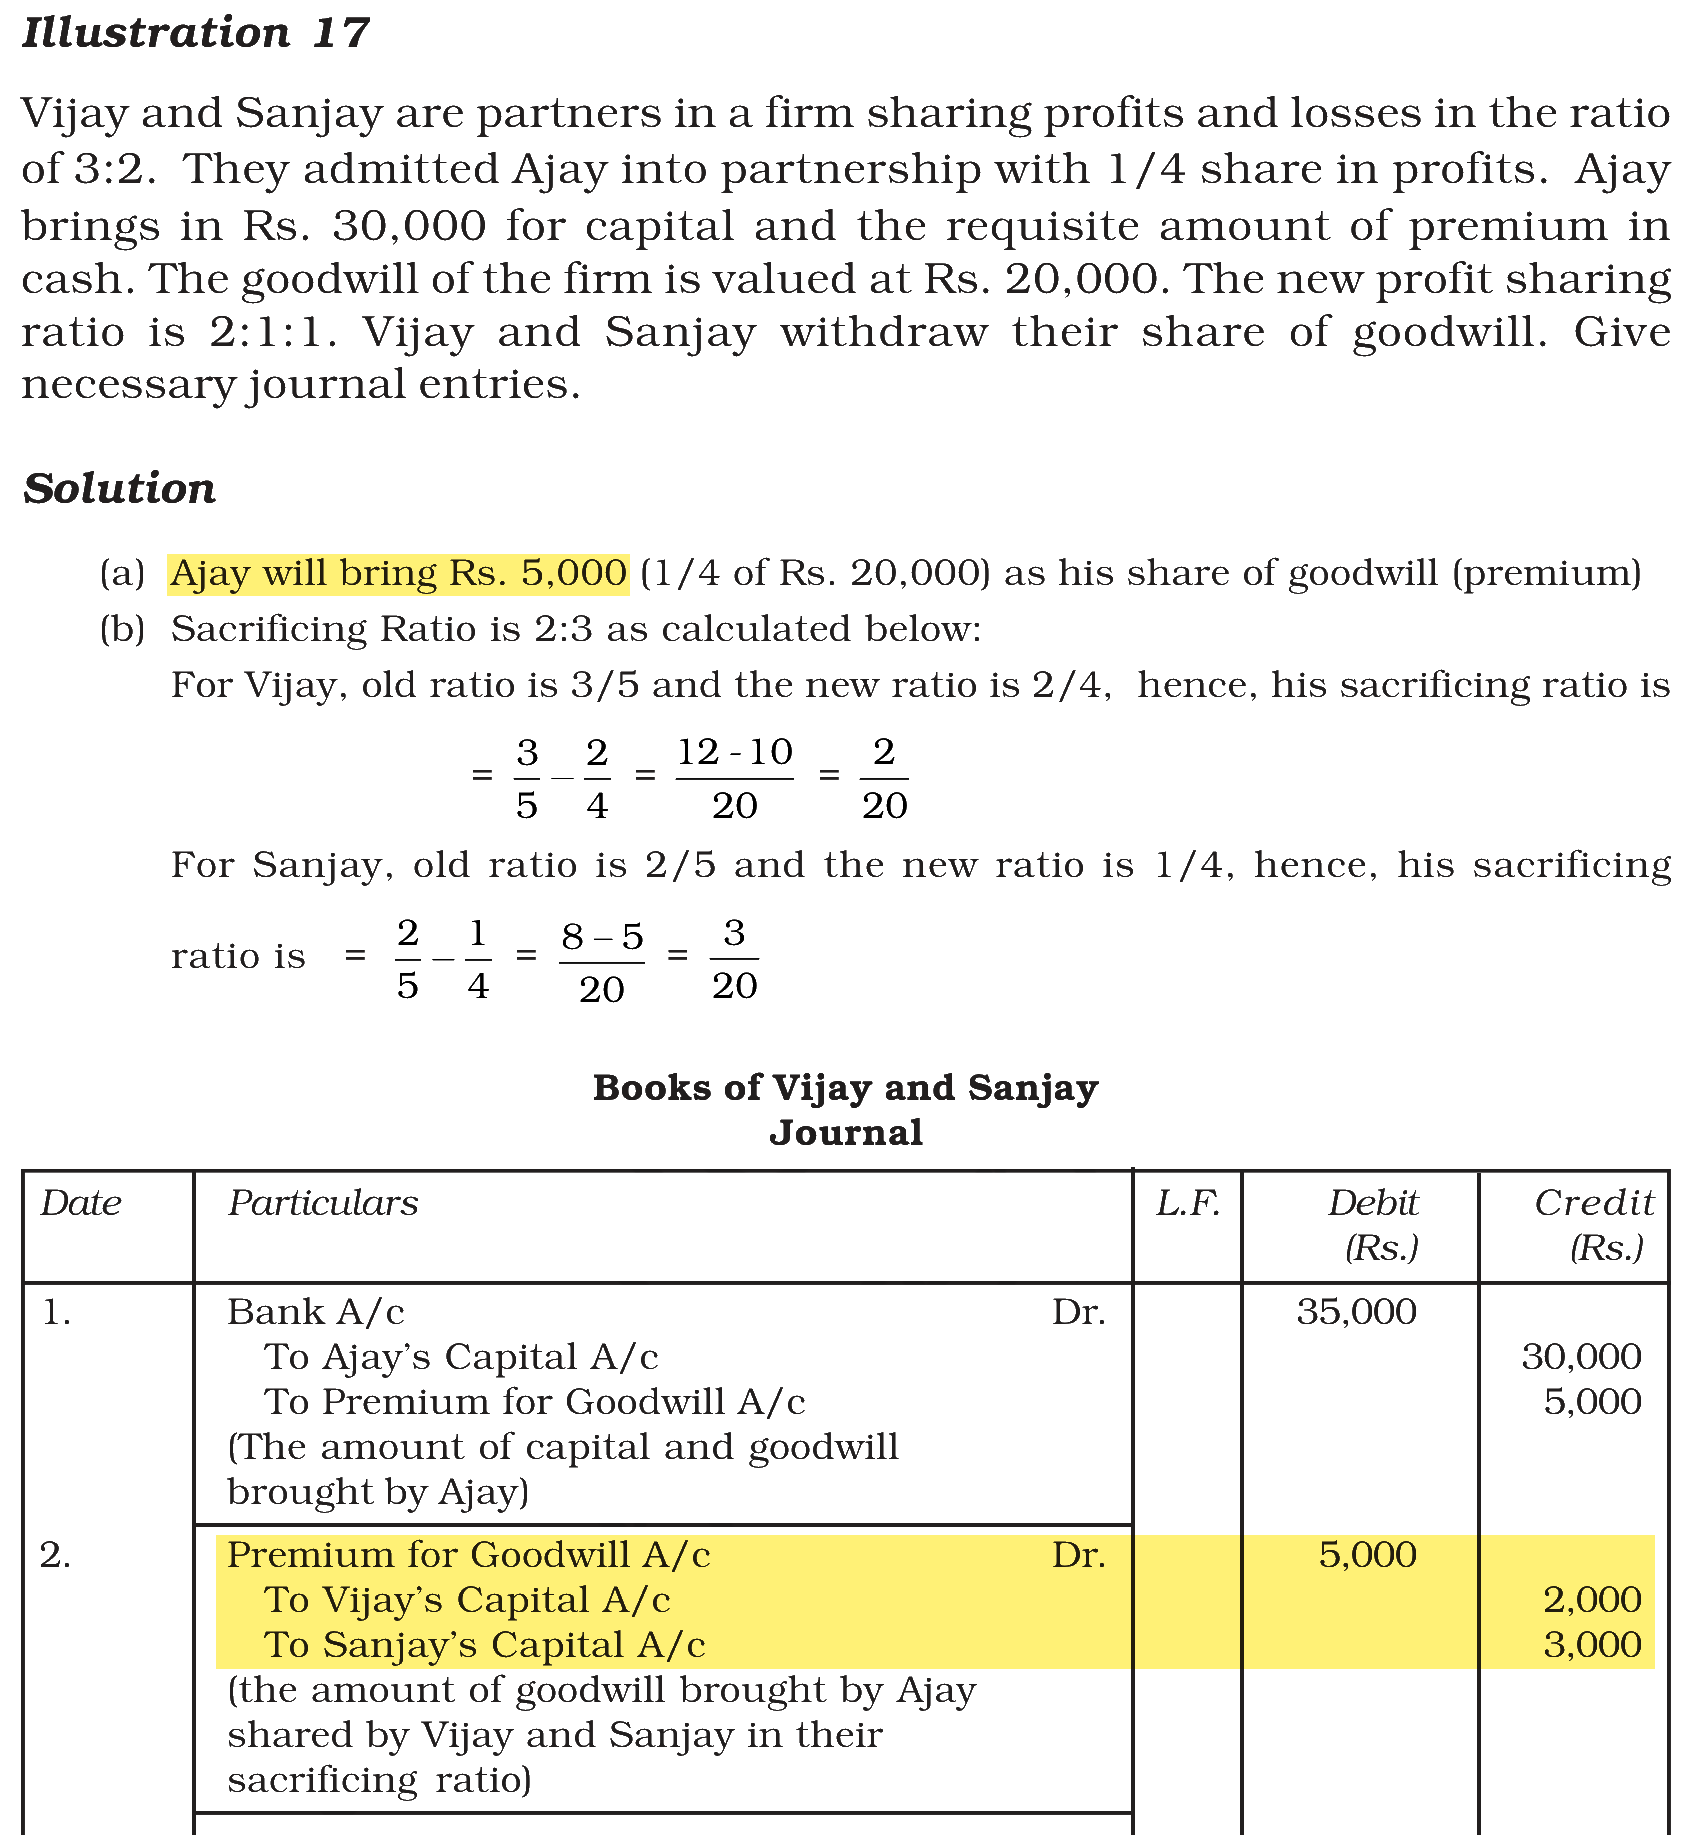
Vijay and Sanjay are partners in a firm sharing profits and losses in the ratio of 3:2. They admitted Ajay into partnership with 1/4 share in profits. Ajay brings in Rs. 30,000 for capital and the requisite amount of premium in cash. The goodwill of the firm is valued at Rs. 20,000. The new profit sharing ratio is 2:1:1. Give necessary journal entry for the adjustment of goodwill.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Premium for Goodwill A/c debited with Rs. 5,000; Vijay’s Capital A/c credited with Rs. 2,000 and Sanjay’s Capital A/c credited with Rs. 3,000
Ajay pays only for his own share of goodwill, and that premium is divided between the old partners in their sacrificing ratio.
Ajay’s share of goodwill = Rs. 20,000 × 1/4 = Rs. 5,000
Vijay’s sacrifice = 3/5 − 2/4 = 12/20 − 10/20 = 2/20
Sanjay’s sacrifice = 2/5 − 1/4 = 8/20 − 5/20 = 3/20
Sacrificing ratio = 2 : 3
Vijay’s Capital A/c Cr. = Rs. 5,000 × 2/5 = Rs. 2,000
Sanjay’s Capital A/c Cr. = Rs. 5,000 × 3/5 = Rs. 3,000
The entry:
Premium for Goodwill A/c Dr. 5,000
To Vijay’s Capital A/c 2,000
To Sanjay’s Capital A/c 3,000
The cash Ajay brings is first credited to Premium for Goodwill A/c, which is why that account is debited when the premium is passed on. The old ratio 3:2 would give 12,000 and 8,000 out of the full Rs. 20,000, but the whole goodwill is never credited, only the new partner’s 1/4.
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|