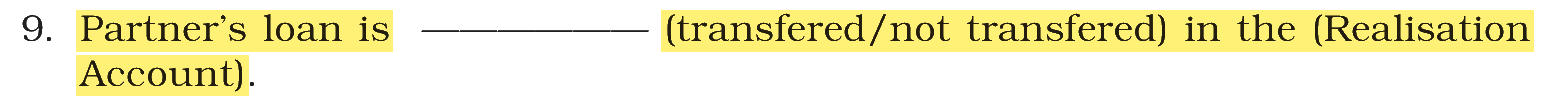Match List-I with List-II
List-I (Amount/Activity at the time of dissolution)
(A) Partner's Loan
(B) Balance of Realisation Account
(C) Realisation expenses paid
(D) Deficiency of capital account of partner
List-II (Accounting Treatment)
(I) Is capital loss for the firm
(II) Is debited to realisation account
(III) Is not recorded in the realisation account
(IV) Is transferred to partner's capital account
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → (A) - (III), (B) - (IV), (C) - (II), (D) - (I)
On dissolution, a Realisation Account is opened to find the profit or loss on selling the assets and paying the outside liabilities. Only assets and external liabilities go into it; amounts owed to partners are settled separately.
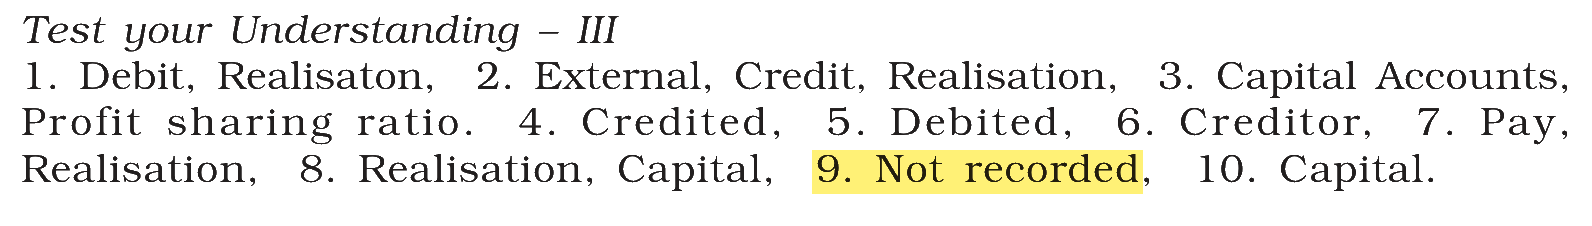
(A) Partner's Loan — this matches (III) Is not recorded in the realisation account. A partner's loan is an internal liability, owed to a partner, so it is not transferred to the Realisation Account; it is paid off directly after the outside creditors.
(B) Balance of Realisation Account — this matches (IV) Is transferred to partner's capital account. The balance is the profit or loss on realisation, and it is shared by the partners in their profit sharing ratio through their capital accounts.
(C) Realisation expenses paid — this matches (II) Is debited to realisation account. The expenses of selling assets and settling liabilities reduce the gain on realisation, so they are a debit to that account.
(D) Deficiency of capital account of partner — this matches (I) Is capital loss for the firm. A partner whose capital account shows a debit balance he cannot make good leaves the firm short of capital; the amount that cannot be recovered from him is a capital loss of the firm.
NCERT (2026-27 edition): Inability of a Partner to Contribute Towards Deficiency – “In the context of settlement of accounts among the partners there is still another important aspect to be noted, i.e., when a partner is unable to contribute towards the deficiency of his capital account (the account finally showing a debit balance), he/she is said to be insolvent, and the sum not recoverable is treated as capital loss for the firm.” Test your Understanding
Checklist to Check your Understanding
|