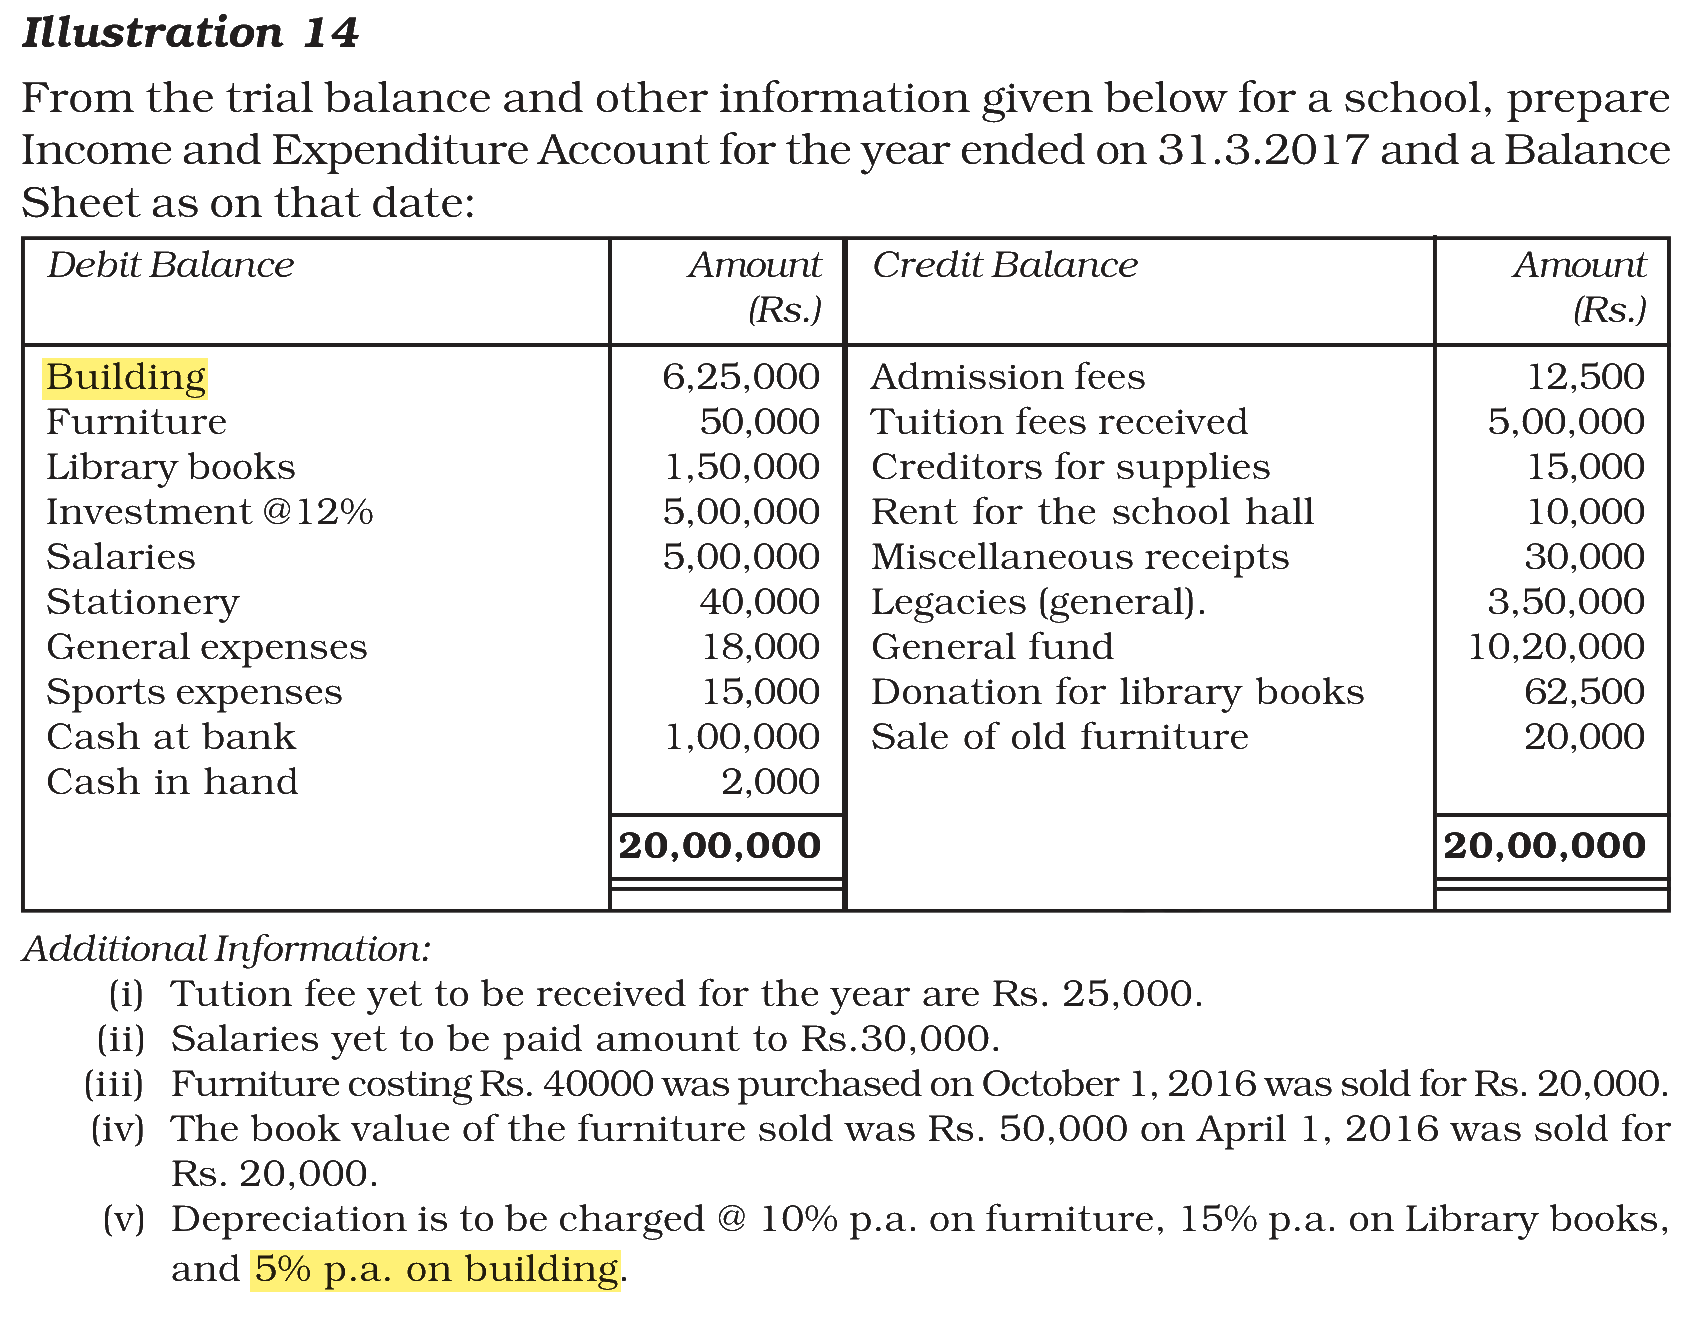
From the trial balance and other information provided by school for the year ended 31st March 2017. Answer the question.
|
Debit Balance |
Amount (₹) |
Credit Balance |
Amount (₹) |
|
Building |
6,25,000 |
Admission fees |
12,500 |
|
Furniture |
1,00,000 |
Tuition fees received |
5,00,000 |
|
Library Books |
1,50,000 |
Creditors for supplies |
15,000 |
|
Investment @12% |
5,00,000 |
Rent for the school hall |
10,000 |
|
Salaries |
5,00,000 |
Miscellaneous receipts |
30,000 |
|
Stationery |
40,000 |
Government grant |
3,50,000 |
|
General expenses |
18,000 |
General fund |
10,00,000 |
|
Sports expenses |
15,000 |
Donation for library books |
62,500 |
|
Cash at bank |
50,000 |
Sale of old furniture |
20,000 |
|
Cash in hand |
2,000 |
|
|
|
|
20,00,000 |
|
20,00,000 |
Additional Information:
i. Tuition fee yet to be received for the year are ₹25,000.
ii. Salaries yet to be paid amount to ₹30,000.
iii. Furniture costing ₹40,000 was purchased on October 1, 2016.
iv. The book value of the furniture sold was ₹50,000 on April 1, 2016.
v. Depreciation is to be charged @ 10%p.a. on furniture, 15% p.a. on Library books, and 5% p.a. on building.
The closing value of Building as on 31.3.2017 was:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → ₹ 5,93,750
Building is shown in the Balance Sheet at its value less depreciation at 5% p.a.
Building = ₹6,25,000
Less: Depreciation = ₹6,25,000 × 5/100 = ₹31,250
Closing value = ₹5,93,750
Note: This question is from the pre-rationalised NCERT book. The topic is not there in the latest NCERT book (2026-27), but it is still in the CUET 2026 syllabus, so do not skip it.
NCERT (Pre-rationalised edition):
|