Based on following case, answer question.
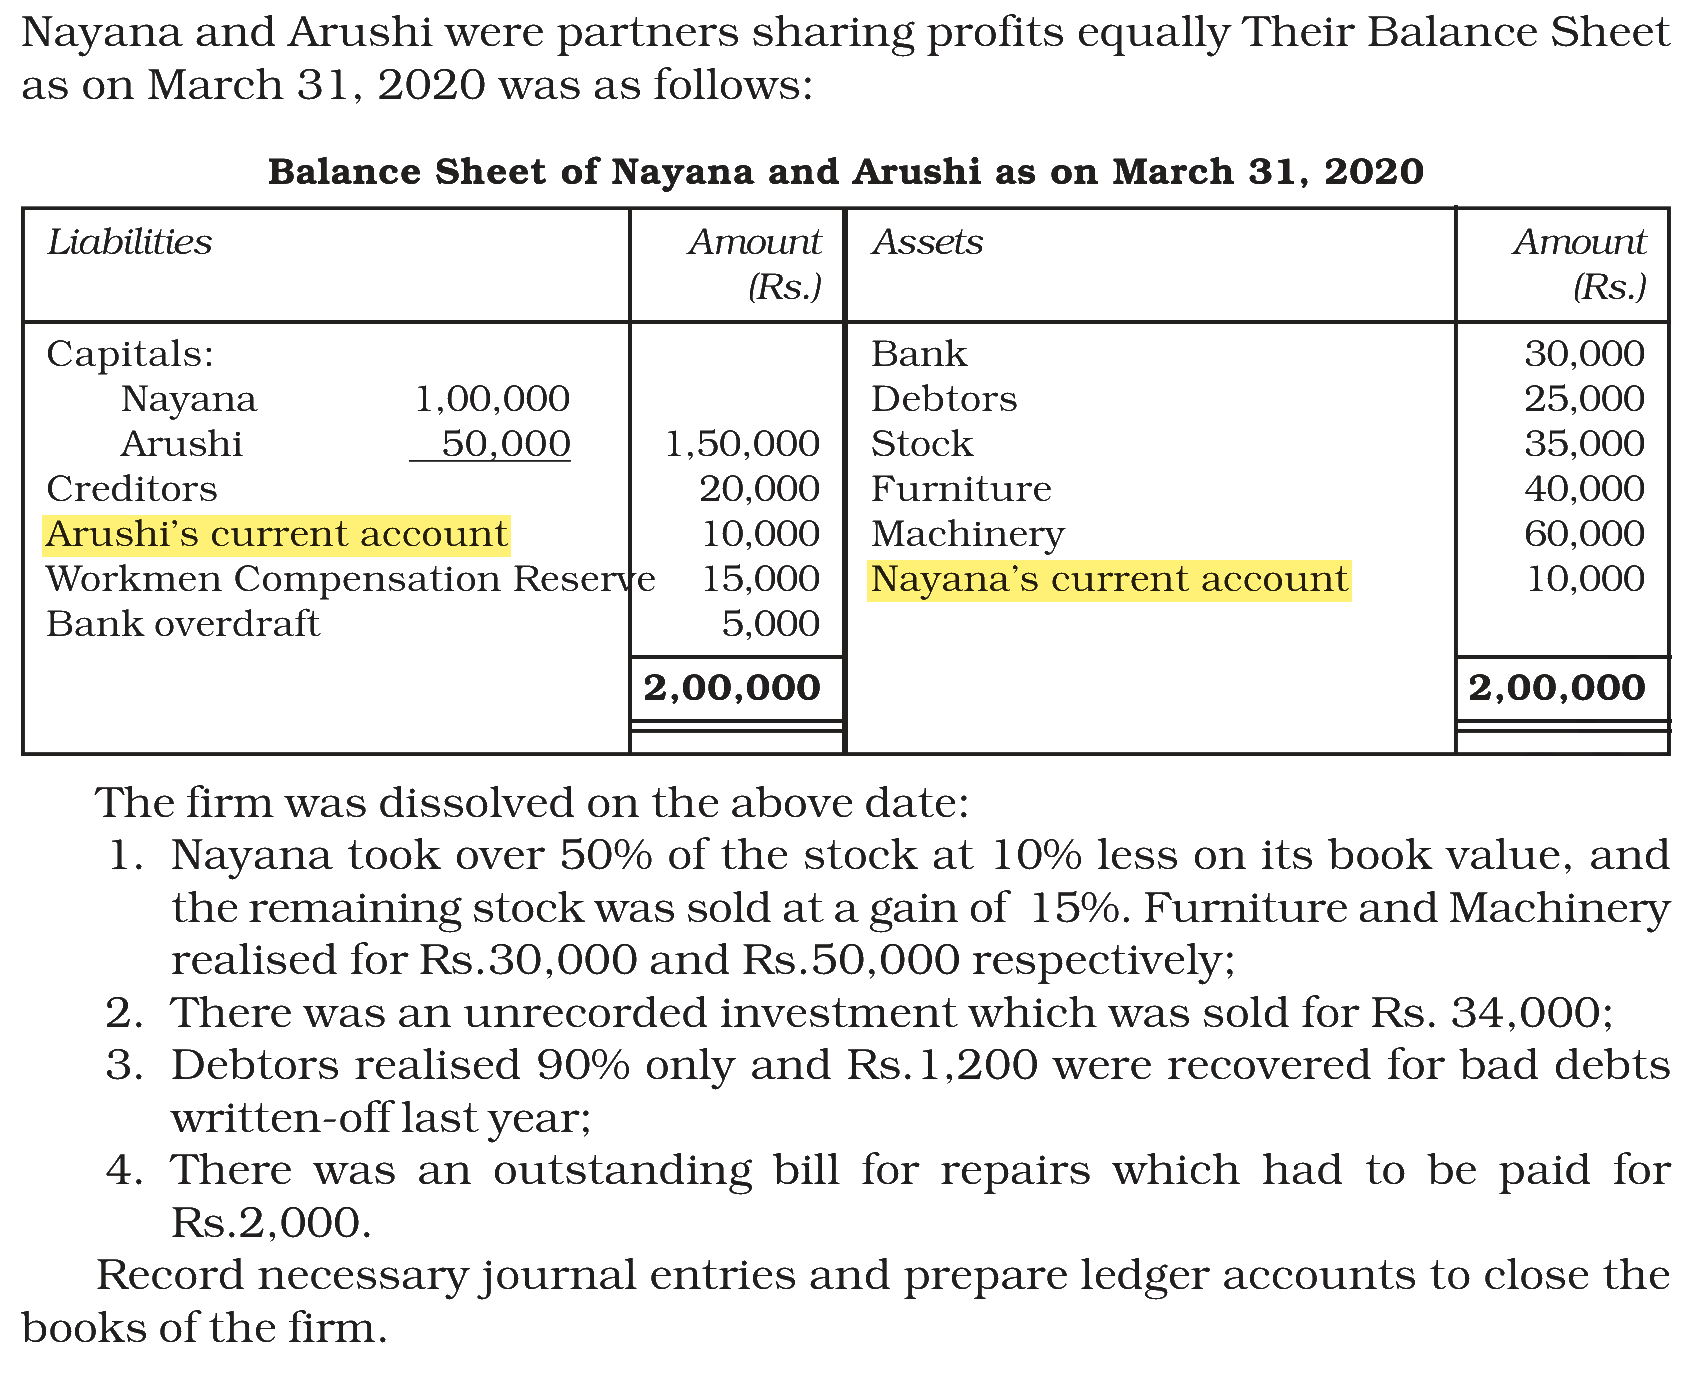
Nayana and Arushi were partners sharing profit equally. Their Balance Sheet as at March 31, 2017 was as follows:
|
Balance Sheet of Nayana and Arushi as on March 31,2017 |
|||
|
Liabilities |
Amount (₹) |
Assets |
Amount (₹) |
|
Capitals: Nayana 1,00,000 Arushi 50,000 Creditors Arushi’s Current account Workmen Compensation Reserve Bank overdraft |
1,50,000 20,000 10,000 15,000 5,000 |
Bank
Debtors Stock Furniture Machinery Nayana’s current account |
30,000
25,000 35,000 40,000 60,000 10,000 |
|
|
2,00,000 |
|
2,00,000 |
The firm was dissolved on the above date:
(1) Nayana took over 50% of the stock at 10% less on its book value, and the remaining stock was sold at a gain of 15%. Furniture and Machinery realised for ₹30,000 and ₹50,000 respectively.
(2) There was an unrecorded investment which was sold for ₹34,000
(3) Debtors realised 90% only and ₹1,200 were recovered for bad debts written-off last year.
(4) There was an outstanding bill for repairs which had to be paid for ₹2,000
Which treatment will be done to the current account of partner at the time of dissolution of firm?
Answer & explanation
Correct answer: option 1
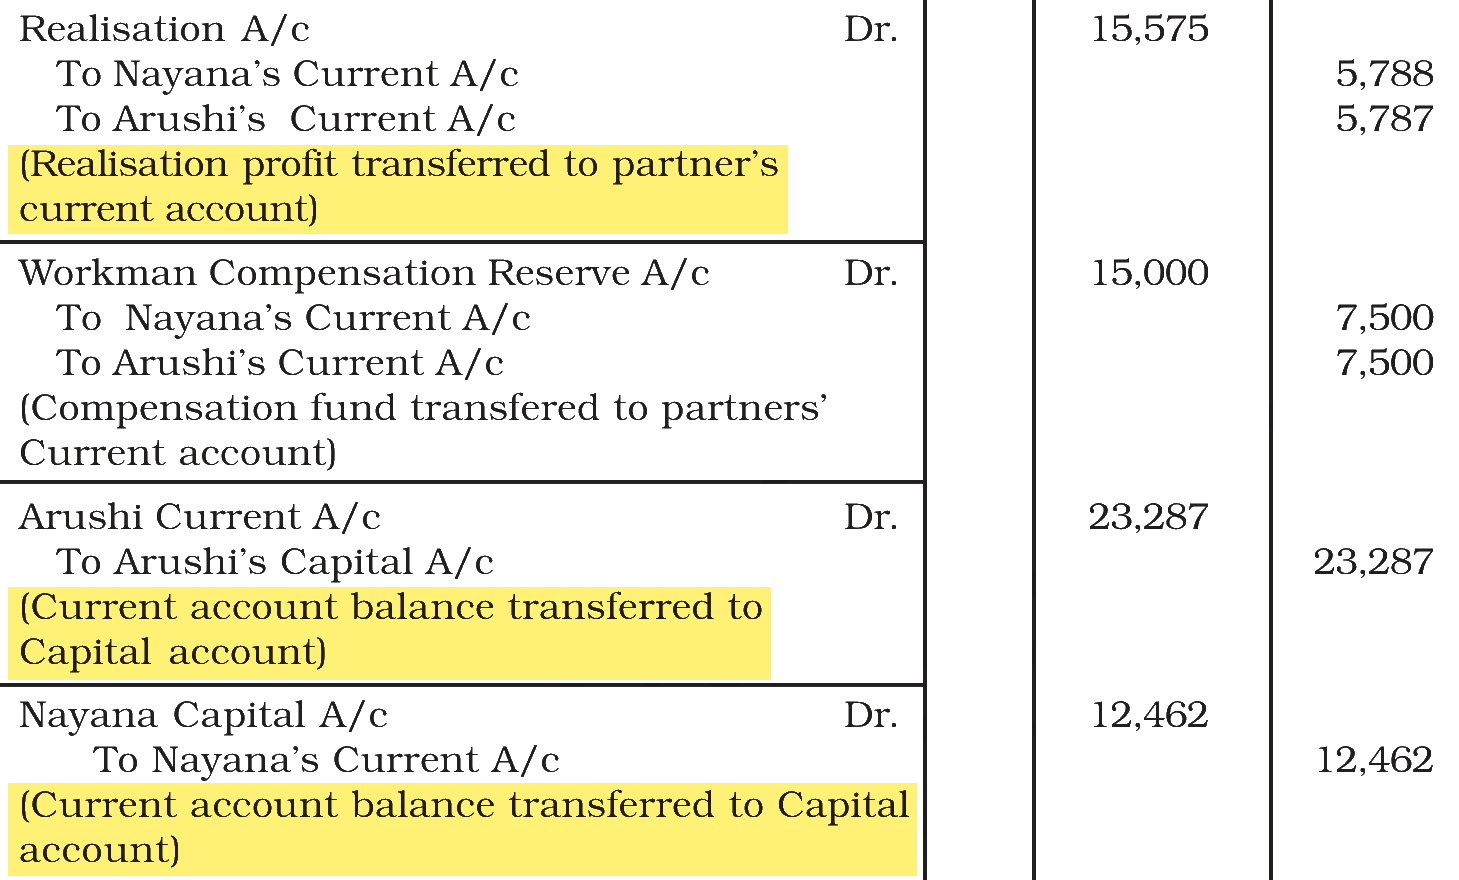
The correct answer is Option (1) → All the necessary transactions are done in partners current account and the balance will be transferred to fixed capital account of partner.
When capitals are fixed, the capital accounts are not disturbed by day-to-day items. At dissolution the realisation profit, the reserve and the stock taken over are first put through the partners’ current accounts. The balance of each current account is then transferred to the capital account, and the final amount due is settled through the capital account.
Option (2) Current account balance will be carried to partners fixed capital and then all transactions will be done in fixed capital account. — Incorrect. The current account is closed only after the adjustments have been passed through it, not before.
Option (3) Current account of partners will be settled by paying off and other transactions will be done in fixed capital account. — Incorrect. No separate cash payment is made on the current account; its balance is moved to the capital account.
Option (4) Current account and Fixed capital account are kept separate. — Incorrect. At dissolution every account is closed, so the two cannot stay separate.
Note: The book’s journal prints ₹15,575 for the realisation profit; it should read ₹11,575 (₹5,788 + ₹5,787).
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|