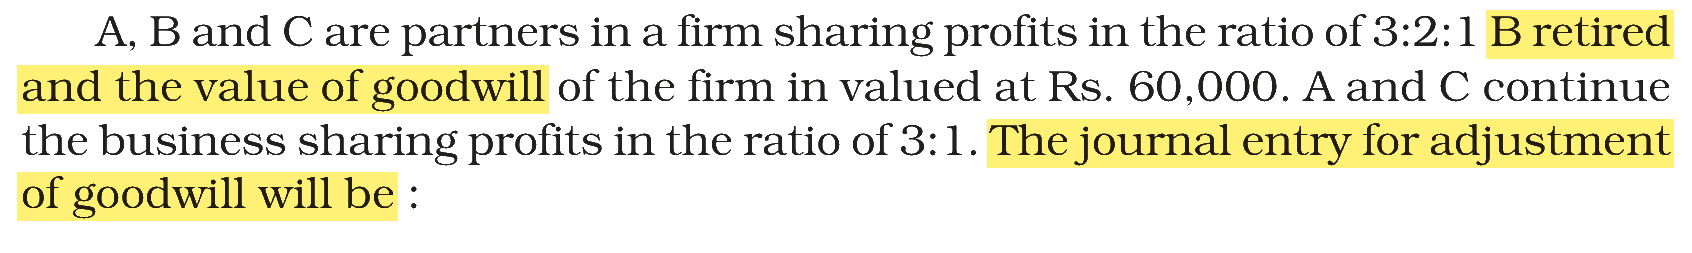Arun, Barun and Chaitanya are partners in a firm sharing profits in the ratio of 3:2:1. Arun retired and the value of goodwill of the firm is valued at Rs. 1,80,000. Barun and Chaitanya continue sharing business profits in the ratio of 2:1. The journal entry for adjustment of goodwill will be:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Barun’s Capital A/c Dr. Rs. 60,000 and Chaitanya’s Capital A/c Dr. Rs. 30,000, to Arun’s Capital A/c Rs. 90,000
On retirement, the retiring partner is paid for his share of goodwill by the partners who take over his share, in their gaining ratio. Without a Goodwill Account, the gaining partners’ capital accounts are debited and the retiring partner’s capital account is credited.
Gaining ratio:
Old shares: Arun 3/6, Barun 2/6, Chaitanya 1/6
New shares: Barun 2/3 = 4/6, Chaitanya 1/3 = 2/6
Barun’s gain = 4/6 − 2/6 = 2/6
Chaitanya’s gain = 2/6 − 1/6 = 1/6
Gaining ratio = 2 : 1
Goodwill adjustment:
Arun’s share of goodwill = Rs. 1,80,000 × 3/6 = Rs. 90,000
Barun pays Rs. 90,000 × 2/3 = Rs. 60,000
Chaitanya pays Rs. 90,000 × 1/3 = Rs. 30,000
Barun’s Capital A/c Dr. 60,000
Chaitanya’s Capital A/c Dr. 30,000
To Arun’s Capital A/c 90,000
Here the gaining ratio happens to equal the new ratio of 2 : 1, but that is not always so; always work out the gains first.
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|