Match List-I with List-II
| List-I | List-II |
| (A) Total Cost | (I) Change in total cost when an additional unit of output is produced. |
| (B) Marginal Cost | (II) Vertical summation of Average Fixed Cost (AFC) and Average Variable Cost (AVC) curves. |
| (C) Fixed Cost | (III) Explicit Costs + Implicit Costs. |
| (D) Short period Average Cost (AC) Curve | (IV) Does not change with increase or decrease in output. |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → (A)-(III), (B)-(I), (C)-(IV), (D)-(II)
A firm’s costs are looked at in total, per unit and for one more unit. In the short run, some costs stay fixed and others change with output.
| List-I | List-II | Reason |
|---|---|---|
| (A) Total Cost | (III) Explicit Costs + Implicit Costs. | Explicit costs are the payments the firm actually makes, such as wages. Implicit costs are the value of its own resources used, and the two together are its whole cost. |
| (B) Marginal Cost | (I) Change in total cost when an additional unit of output is produced. | Marginal cost is the change in total cost per unit of change in output. |
| (C) Fixed Cost | (IV) Does not change with increase or decrease in output. | This is the cost of the fixed inputs. Whatever the output, it stays the same. |
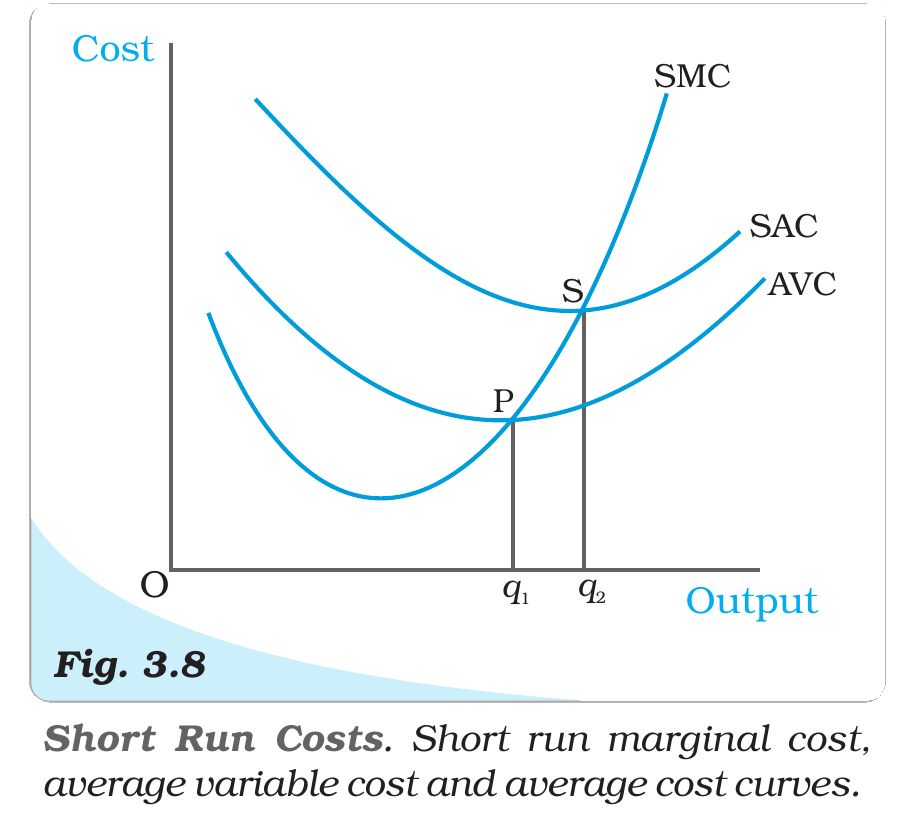
| (D) Short period Average Cost (AC) Curve | (II) Vertical summation of Average Fixed Cost (AFC) and Average Variable Cost (AVC) curves. | Short run average cost is AVC + AFC. So the height of the AC curve at each output is the two heights added. |
Note: The term ‘implicit costs’ is not in any of the NCERT books (2026-27, 2025-26, 2023-24 or pre-rationalised). The Glossary of the NCERT book speaks of ‘explicit costs and opportunity costs’ under normal profit. ‘Implicit costs’ is explained here for the benefit of the students.
NCERT (2026-27): “3.7.1 Short Run Costs We have previously discussed the short run and the long run. In the short run, some of the factors of production cannot be varied, and therefore, remain fixed. The cost that a firm incurs to employ these fixed inputs is called the total fixed cost (TFC). Whatever amount of output the firm produces, this cost remains fixed for the firm. To produce any required level of output, the firm, in the short run, can adjust only variable inputs. Accordingly, the cost that a firm incurs to employ these variable inputs is called the total variable cost (TVC). Adding the fixed and the variable costs, we get the total cost (TC) of a firm TC = TVC + TFC (3.6)… …Clearly, SAC = AVC + AFC (3.10)… …The short run marginal cost (SMC) is defined as the change in total cost per unit of change in output… …SAC curve is therefore ‘U’-shaped. It lies above the AVC curve with the vertical difference being equal to the value of AFC.… …Figure 3.8 shows the shapes of short run marginal cost, average variable cost and short run average cost curves for a typical firm.…” NCERT (2026-27), Introductory Microeconomics, Glossary: “…Normal profit The profit level that is just enough to cover the explicit costs and opportunity costs of the firm is called the normal profit.…”
|