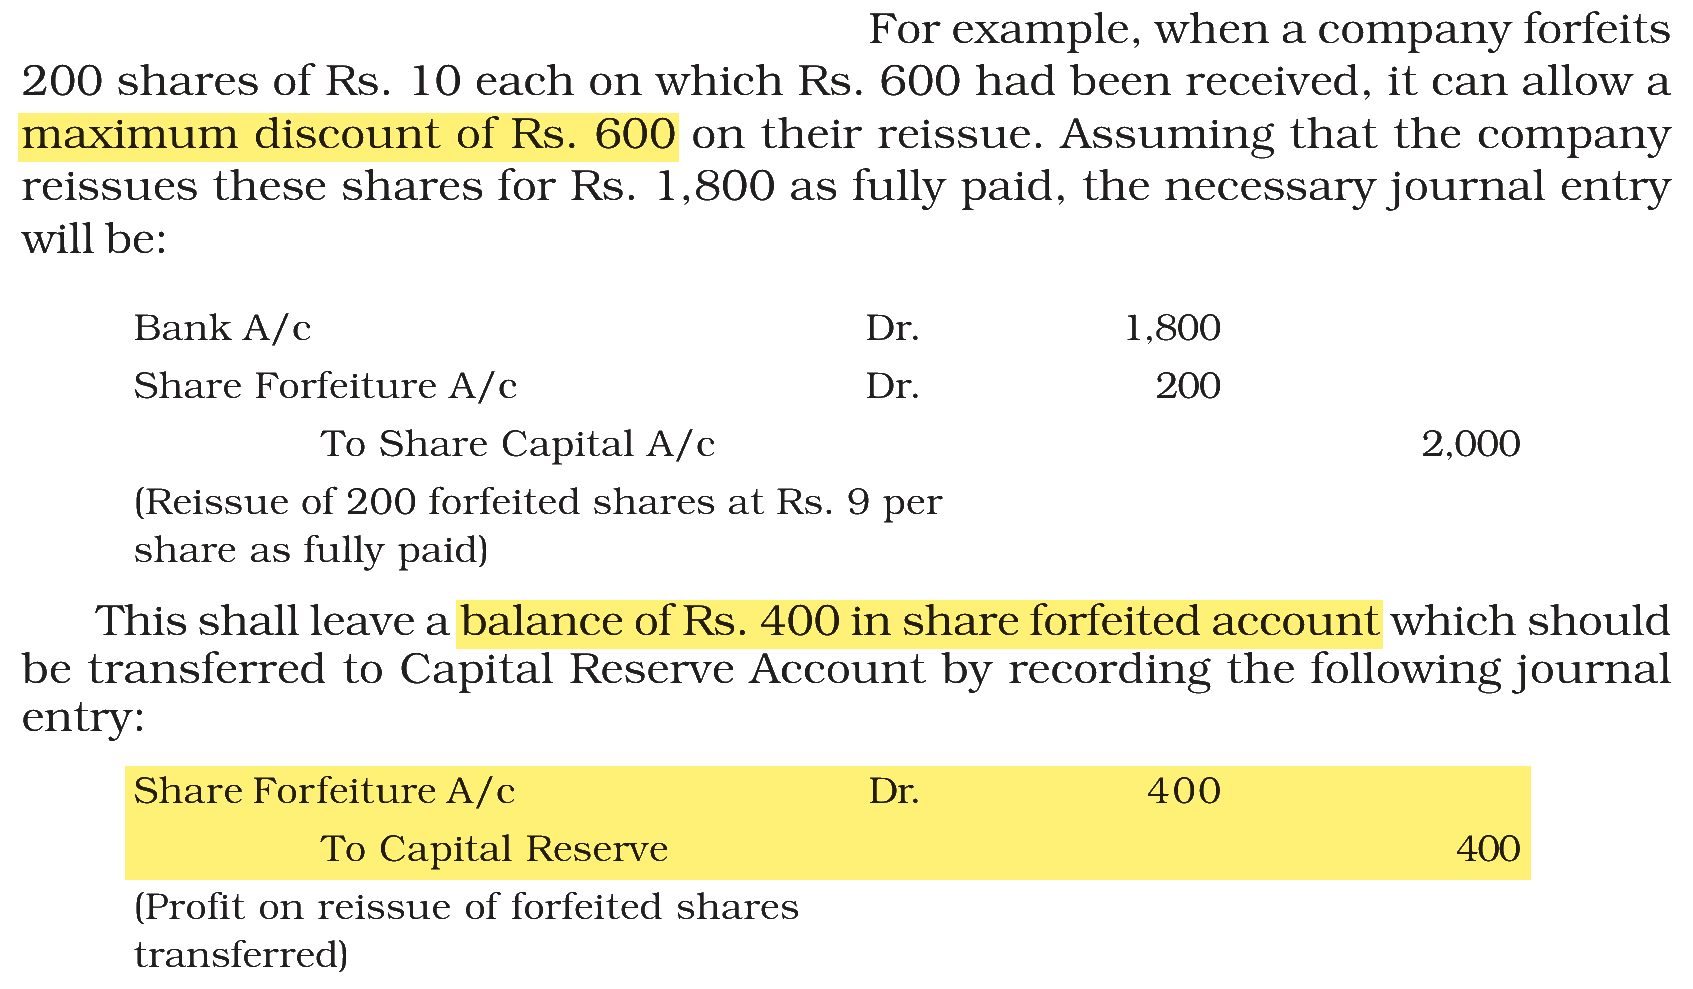
A company forfeits 200 shares of Rs. 10 each on which Rs. 600 had been received. It can allow a maximum discount of Rs. 600 on their reissue. Assuming that the company reissues these shares for Rs. 1,800 as fully paid up. What will be the journal entry for the treatment of remaining forfeited amount after adjustment of discount ?
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Share Forfeiture A/c Dr. 400, To Capital Reserve A/c 400
The discount allowed on reissue of forfeited shares is charged to the Share Forfeiture Account. Whatever is left in that account for the reissued shares is a capital profit, so it is transferred to Capital Reserve.
Amount forfeited on 200 shares = Rs. 600 (credit in Share Forfeiture A/c)
Face value of 200 shares = 200 × Rs. 10 = Rs. 2,000
Discount on reissue = Rs. 2,000 − Rs. 1,800 = Rs. 200 (within the maximum of Rs. 600)
Balance left = Rs. 600 − Rs. 200 = Rs. 400
The entry debits Share Forfeiture A/c and credits Capital Reserve A/c with Rs. 400.
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|