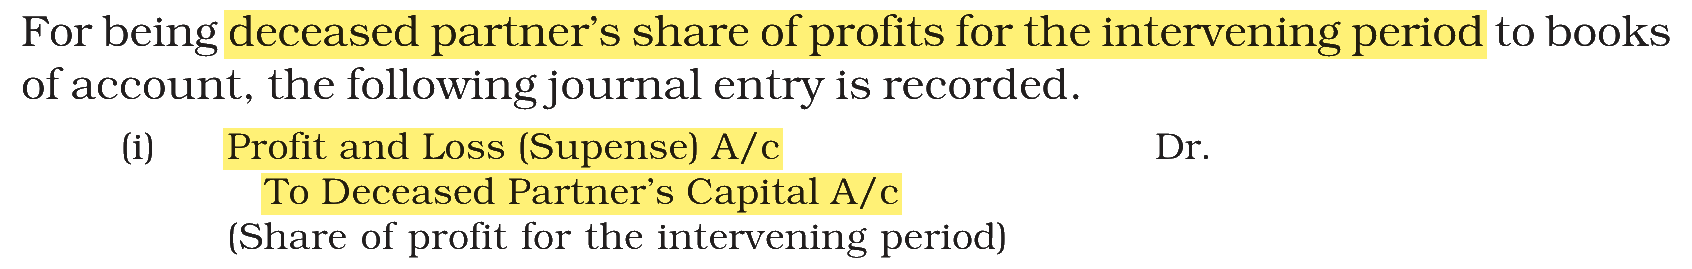
Which account is to be debited to transfer the share of profit of deceased partner for the intervening period?
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Profit and Loss Suspense account
The deceased partner is entitled to his share of profit from the date of the last balance sheet to the date of death (the intervening period). The books are not closed on that date, so the amount is credited to his capital account and debited to Profit and Loss Suspense Account. This account is later closed by transfer to the gaining partners’ capital accounts in their gaining ratio.
Option (1) Profit and Loss account — Incorrect. The Profit and Loss Account for the year is not prepared on the date of death, so the share cannot be charged to it then.
Option (3) Deceased Partner's Capital account — Incorrect. The deceased partner’s capital account is credited with his share, not debited.
Option (4) Surviving Partner Current account — Incorrect. The surviving partners are charged only later, when the suspense account is closed in the gaining ratio.
NCERT (2026-27 edition):
|