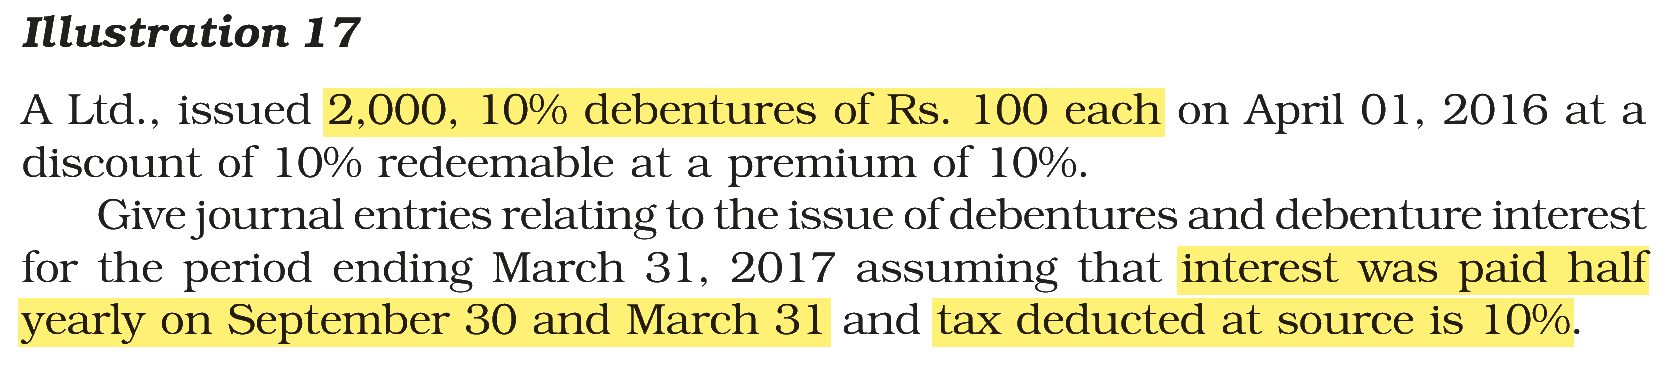
DINKAR Ltd., issued 2,000, 10% debentures of Rs. 100 each on April 01, 2024 at a premium of 10% and redeemable at a premium of 10%. Debenture interest was paid half yearly on September 30 and March 31 and tax deducted at source is 10% for the period ending March 31, 2025. Journal entry for Debenture interest transferred to profit and loss account for the period ending March 31, 2025 will be:
Answer & explanation
Correct answer: option 2
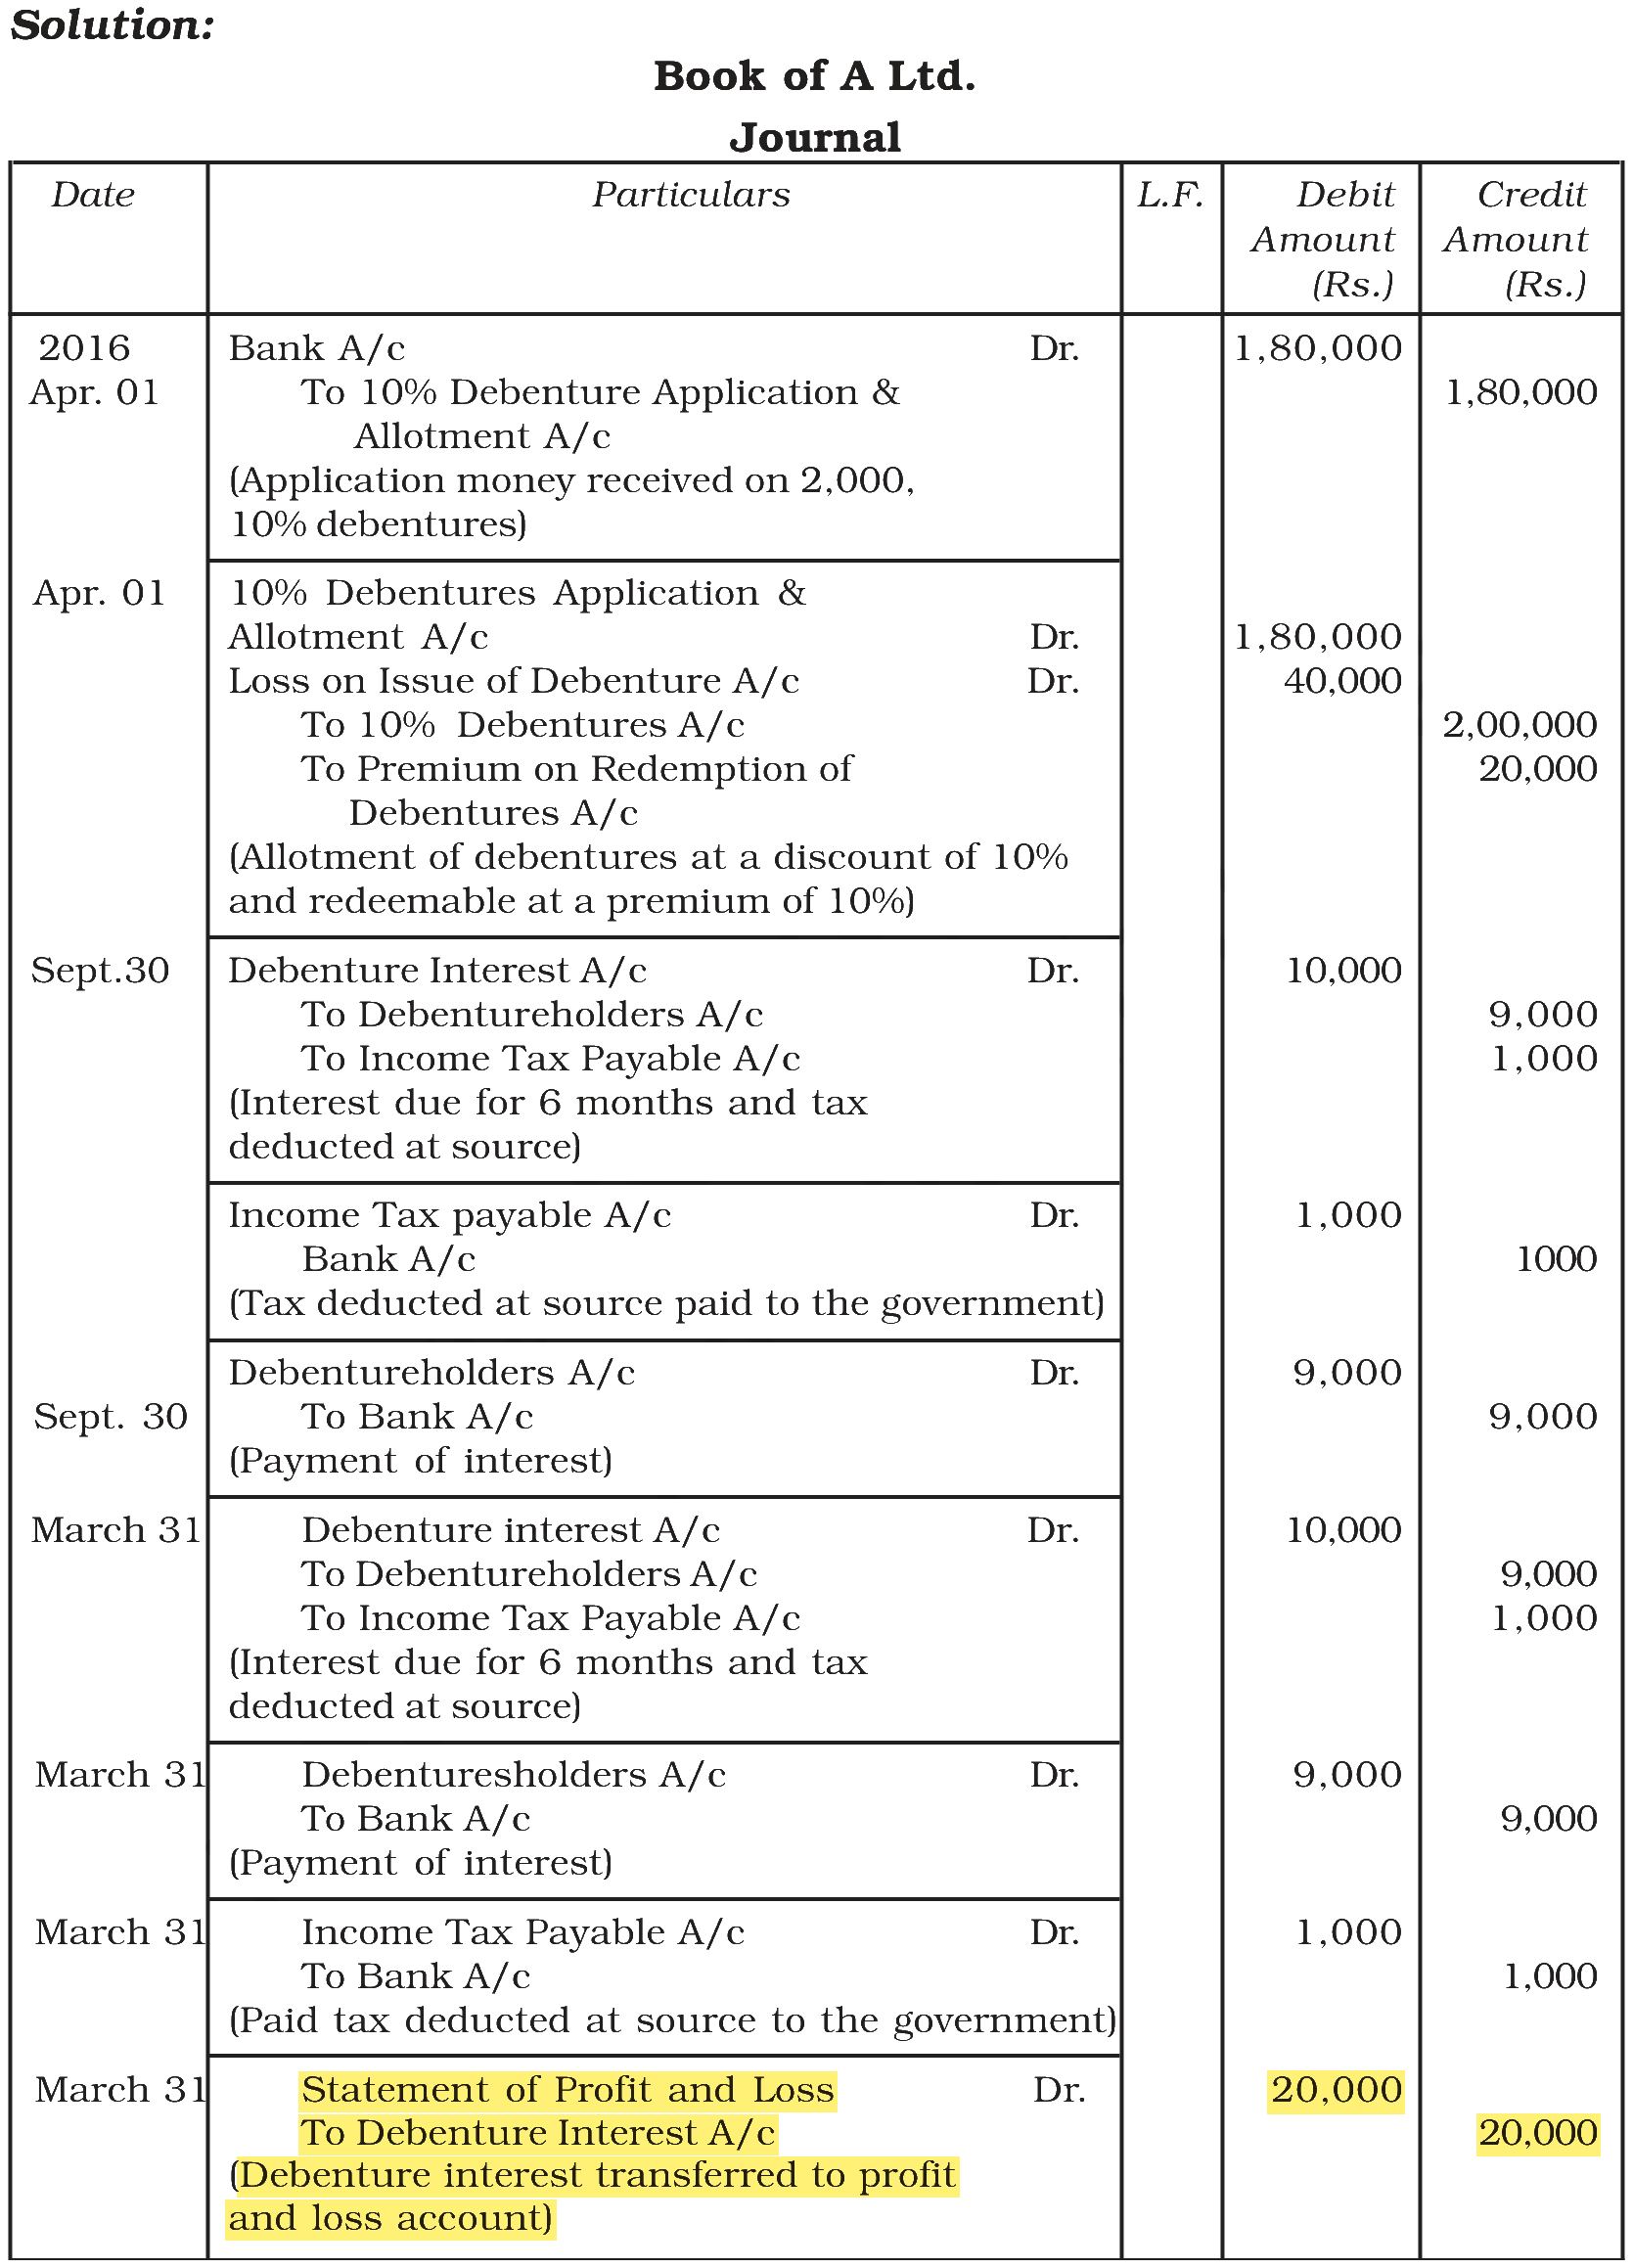
The correct answer is Option (2) → Statement of Profit and Loss Dr. Rs. 20,000, To Debenture Interest A/c Rs. 20,000
Debenture interest is always worked out on the face value, whatever the issue price, so the premium on issue does not change it. At the end of the year the whole interest for the year is transferred to the Statement of Profit and Loss.
Face value = 2,000 × Rs. 100 = Rs. 2,00,000
Interest for the year = Rs. 2,00,000 × 10/100 = Rs. 20,000 (two half-yearly instalments of Rs. 10,000)
Entry: Statement of Profit and Loss Dr. Rs. 20,000, To Debenture Interest A/c Rs. 20,000
The tax deducted at source of 10% (Rs. 2,000 for the year) is handled when the interest is paid: it is credited to Income Tax Payable A/c and only the net amount goes to the debentureholders. It does not reduce the interest expense, so it has no place in the transfer entry.
The book’s version of this question issues the debentures at a discount of 10%, hence the loss-on-issue entry in its solution; NTA’s question issues them at a premium of 10%. The interest of Rs. 20,000 and the transfer entry are the same either way.
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|