Match List – I with List – II.
|
List - I |
List - II |
|
(A) Increase in assets at the time of retirement |
(I) Debit side of Realisation Account |
|
(B) Asset taken over by the partner at the time of dissolution of the firm |
(II) Credit side of Revaluation Account |
|
(C) Unrecorded Liability at the time of admission of the partner |
(III) Credit side of Realisation Account |
|
(D) Remuneration paid for realization of assets |
(IV) Debit side of Revaluation Account |
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → (A)-(II), (B)-(III), (C)-(IV), (D)-(I)
Two accounts are at work here. The Revaluation Account is used on admission and retirement: gains on its credit side, losses on its debit side. The Realisation Account is used on dissolution: assets and payments on its debit side, liabilities and amounts received on its credit side.
(A) Increase in assets at the time of retirement — this matches (II) Credit side of Revaluation Account. A rise in the value of an asset is a gain.
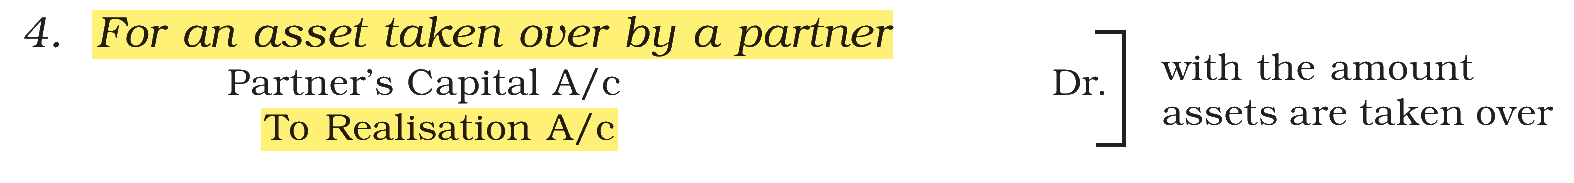
(B) Asset taken over by the partner at the time of dissolution of the firm — this matches (III) Credit side of Realisation Account. The entry is Partner’s Capital A/c Dr. To Realisation A/c, because the partner “pays” for the asset.
(C) Unrecorded Liability at the time of admission of the partner — this matches (IV) Debit side of Revaluation Account. A liability brought into the books is a loss.
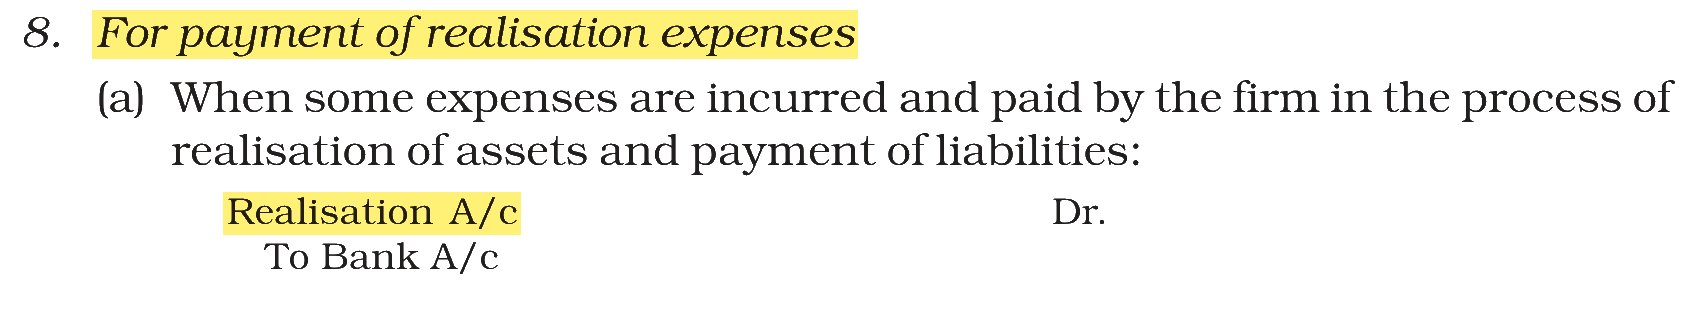
(D) Remuneration paid for realization of assets — this matches (I) Debit side of Realisation Account. It is a realisation expense: Realisation A/c Dr. To Bank (or to the partner’s capital).
NCERT (2026-27 edition): NCERT (2026-27 edition):
NCERT (2026-27 edition):
|