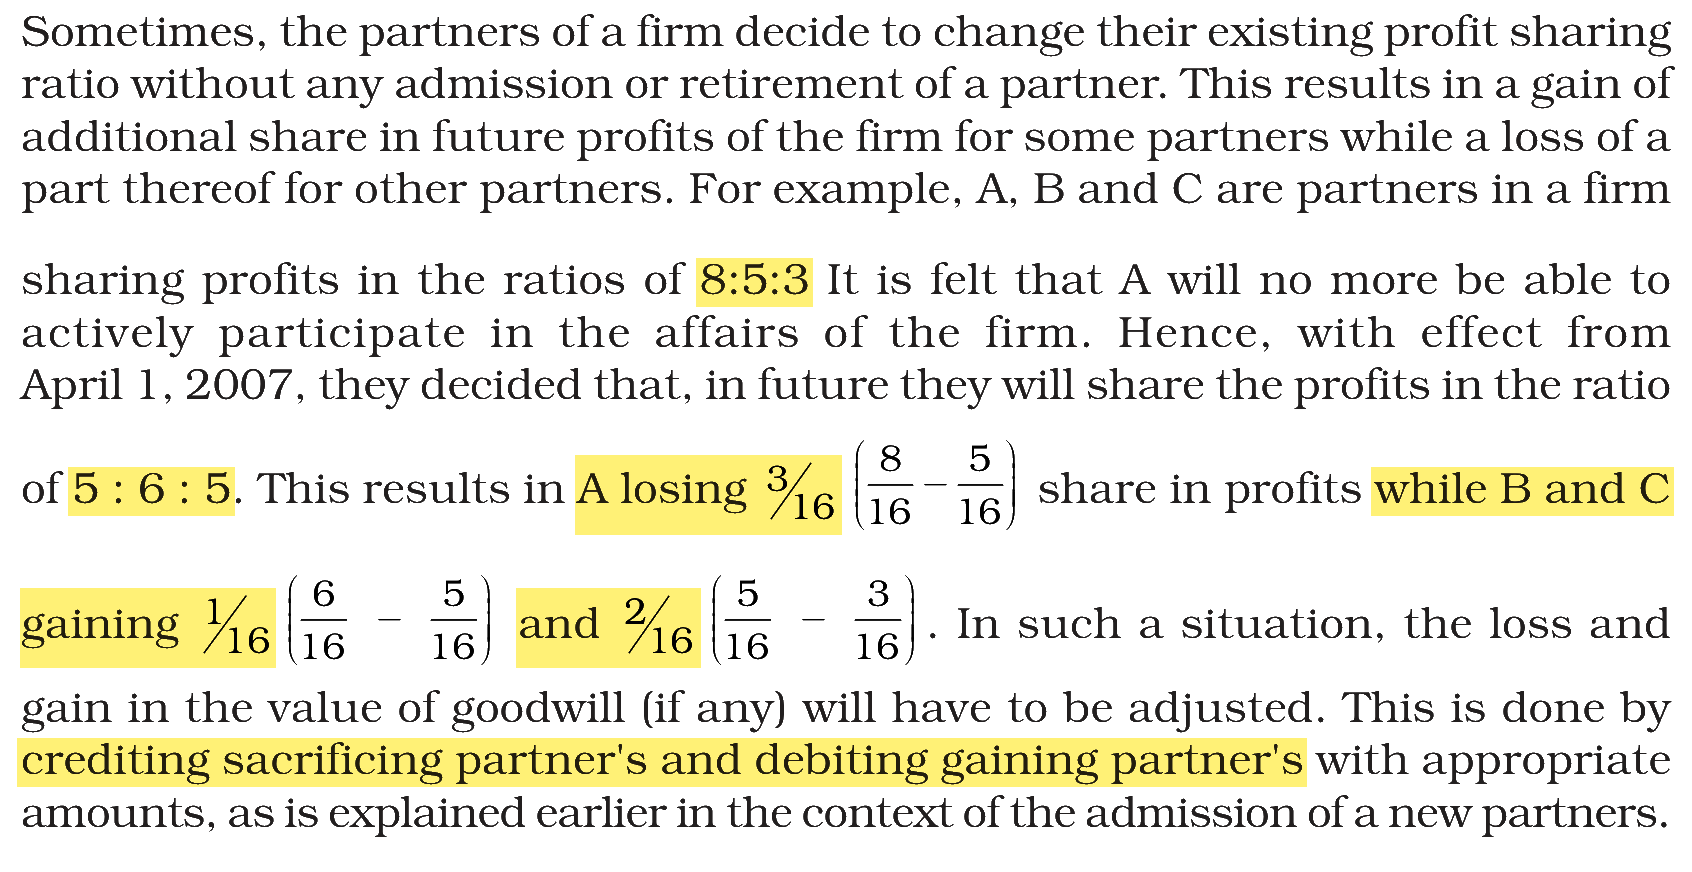
A, B and C are partners in a firm sharing profits in the ratio of 8:5:3. It is felt that A will no more be able to actively participate in the affairs of the firm so, with effect from April 1, 2025, they decided that, in future they will share the profits in the ratio of 5:6:5.
The goodwill of the firm is valued at Rs. 64,000 and goodwill was not to appear in the books. Choose the correct journal entry for adjustment of goodwill A/c:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → B’s Capital A/c Dr. Rs. 4,000 and C’s Capital A/c Dr. Rs. 8,000, To A’s Capital A/c Rs. 12,000
When partners change their profit sharing ratio, the partner who gives up a share is compensated by the partners who gain it. Goodwill is not to appear in the books, so the adjustment is made through the capital accounts: gaining partners are debited and the sacrificing partner is credited, each with his share of goodwill for the change.
A: 8/16 − 5/16 = 3/16 sacrifice
B: 5/16 − 6/16 = 1/16 gain
C: 3/16 − 5/16 = 2/16 gain
A is credited Rs. 64,000 × 3/16 = Rs. 12,000
B is debited Rs. 64,000 × 1/16 = Rs. 4,000
C is debited Rs. 64,000 × 2/16 = Rs. 8,000
B's Capital A/c Dr. 4,000
C's Capital A/c Dr. 8,000
To A's Capital A/c 12,000
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|