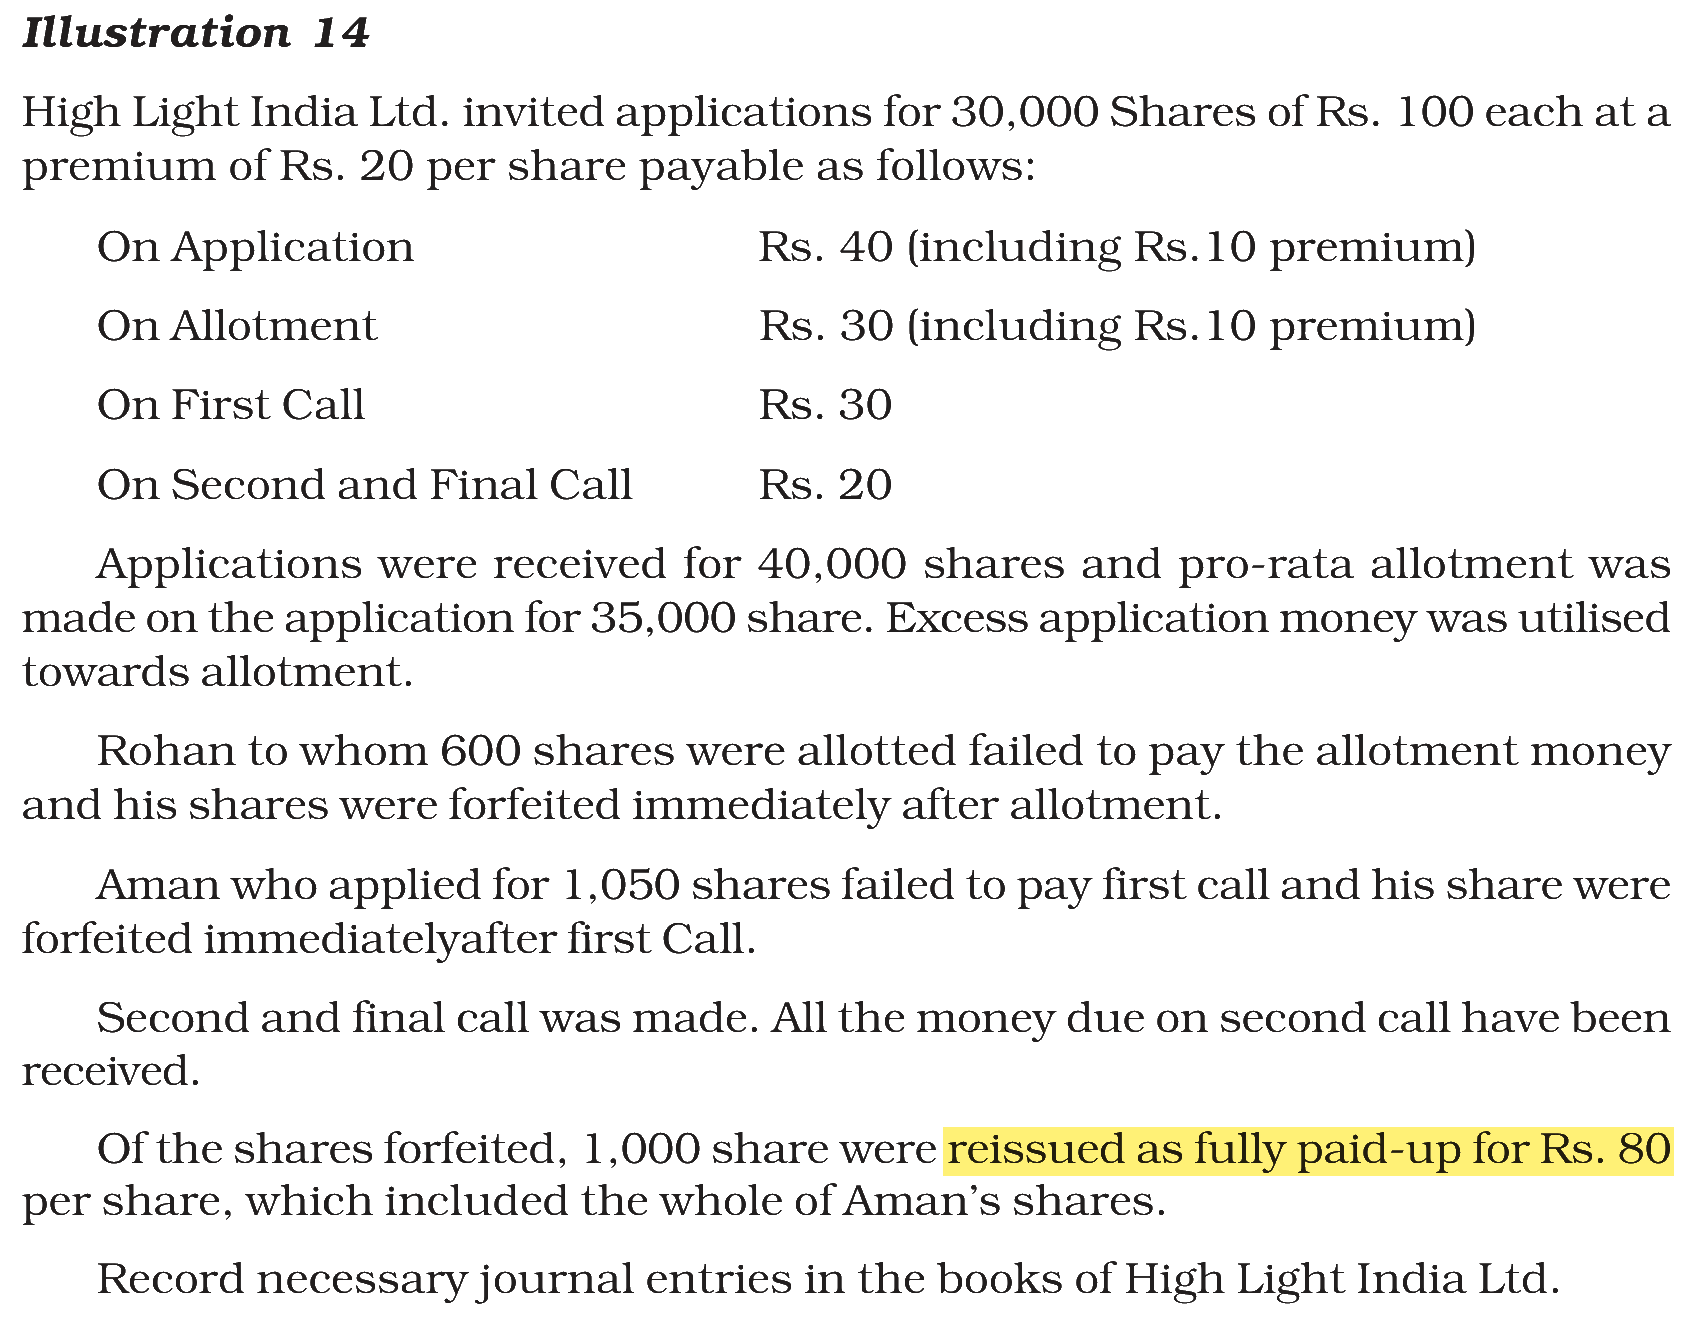
High Light India Ltd. invited applications for 30,000 shares of ₹100 each at a premium of ₹ 20 per share payable as follows :
| On Applications | ₹40 (including ₹10 premium) |
| On Allotment | ₹30 (including ₹10 premium) |
| On First Call | ₹30 |
| On Second and Final Call | ₹20 |
Applications were received for 40,000 shares and pro-rata allotment was made to the applicants for 35,000 shares. Excess application money was utilised towards allotment.
Rohan to whom 600 shares were allotted failed to pay the allotment money and his shares were forfeited immediately after allotment.
Aman who applied for 1,050 shares failed to pay first call and his shares were forfeited immediately after first call.
Second and final call was made. All the money due on second call has been received.
Of the shares forfeited 1,000 shares were reissued as fully paid-up for ₹80 per share, which include the whole of Aman's shares.
Answer the question on the basis of the information given.
State the treatment of profit on the shares reissued.
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Credit Capital Reserve by ₹28,667
On reissue, the forfeited amount on the reissued shares, less the discount allowed, is a capital profit and goes to Capital Reserve.
Rohan applied for 600 × 35,000/30,000 = 700 shares and paid 700 × ₹40 = ₹28,000
Forfeited on Rohan’s 600 shares = ₹30,000 + ₹6,000 − ₹14,000 = ₹22,000
Aman was allotted 1,050 × 30,000/35,000 = 900 shares; forfeited = 900 × ₹50 = ₹45,000
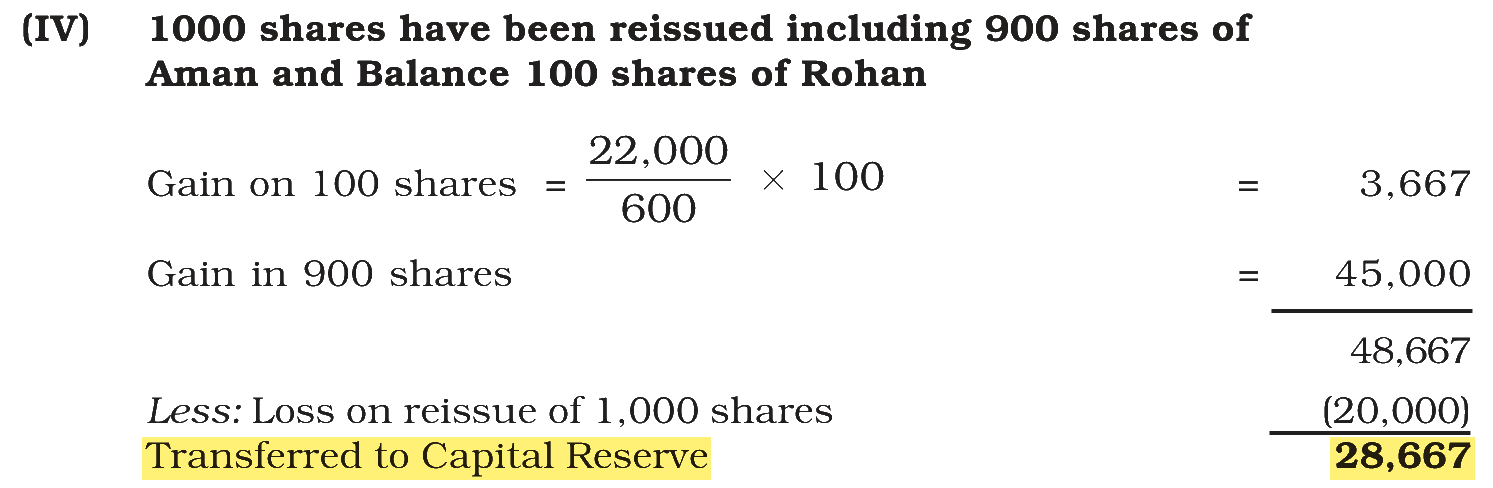
Shares reissued = 900 (Aman) + 100 (Rohan)
Forfeited amount on them = ₹45,000 + ₹22,000 × 100/600 = ₹45,000 + ₹3,667 = ₹48,667
Discount on reissue = 1,000 × (₹100 − ₹80) = ₹20,000
Capital Reserve = ₹48,667 − ₹20,000 = ₹28,667
The balance of ₹18,333 on Rohan’s other 500 shares stays in the Share Forfeiture Account until those shares are reissued.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition): |