Read the following information provided by a school and attempt Question:
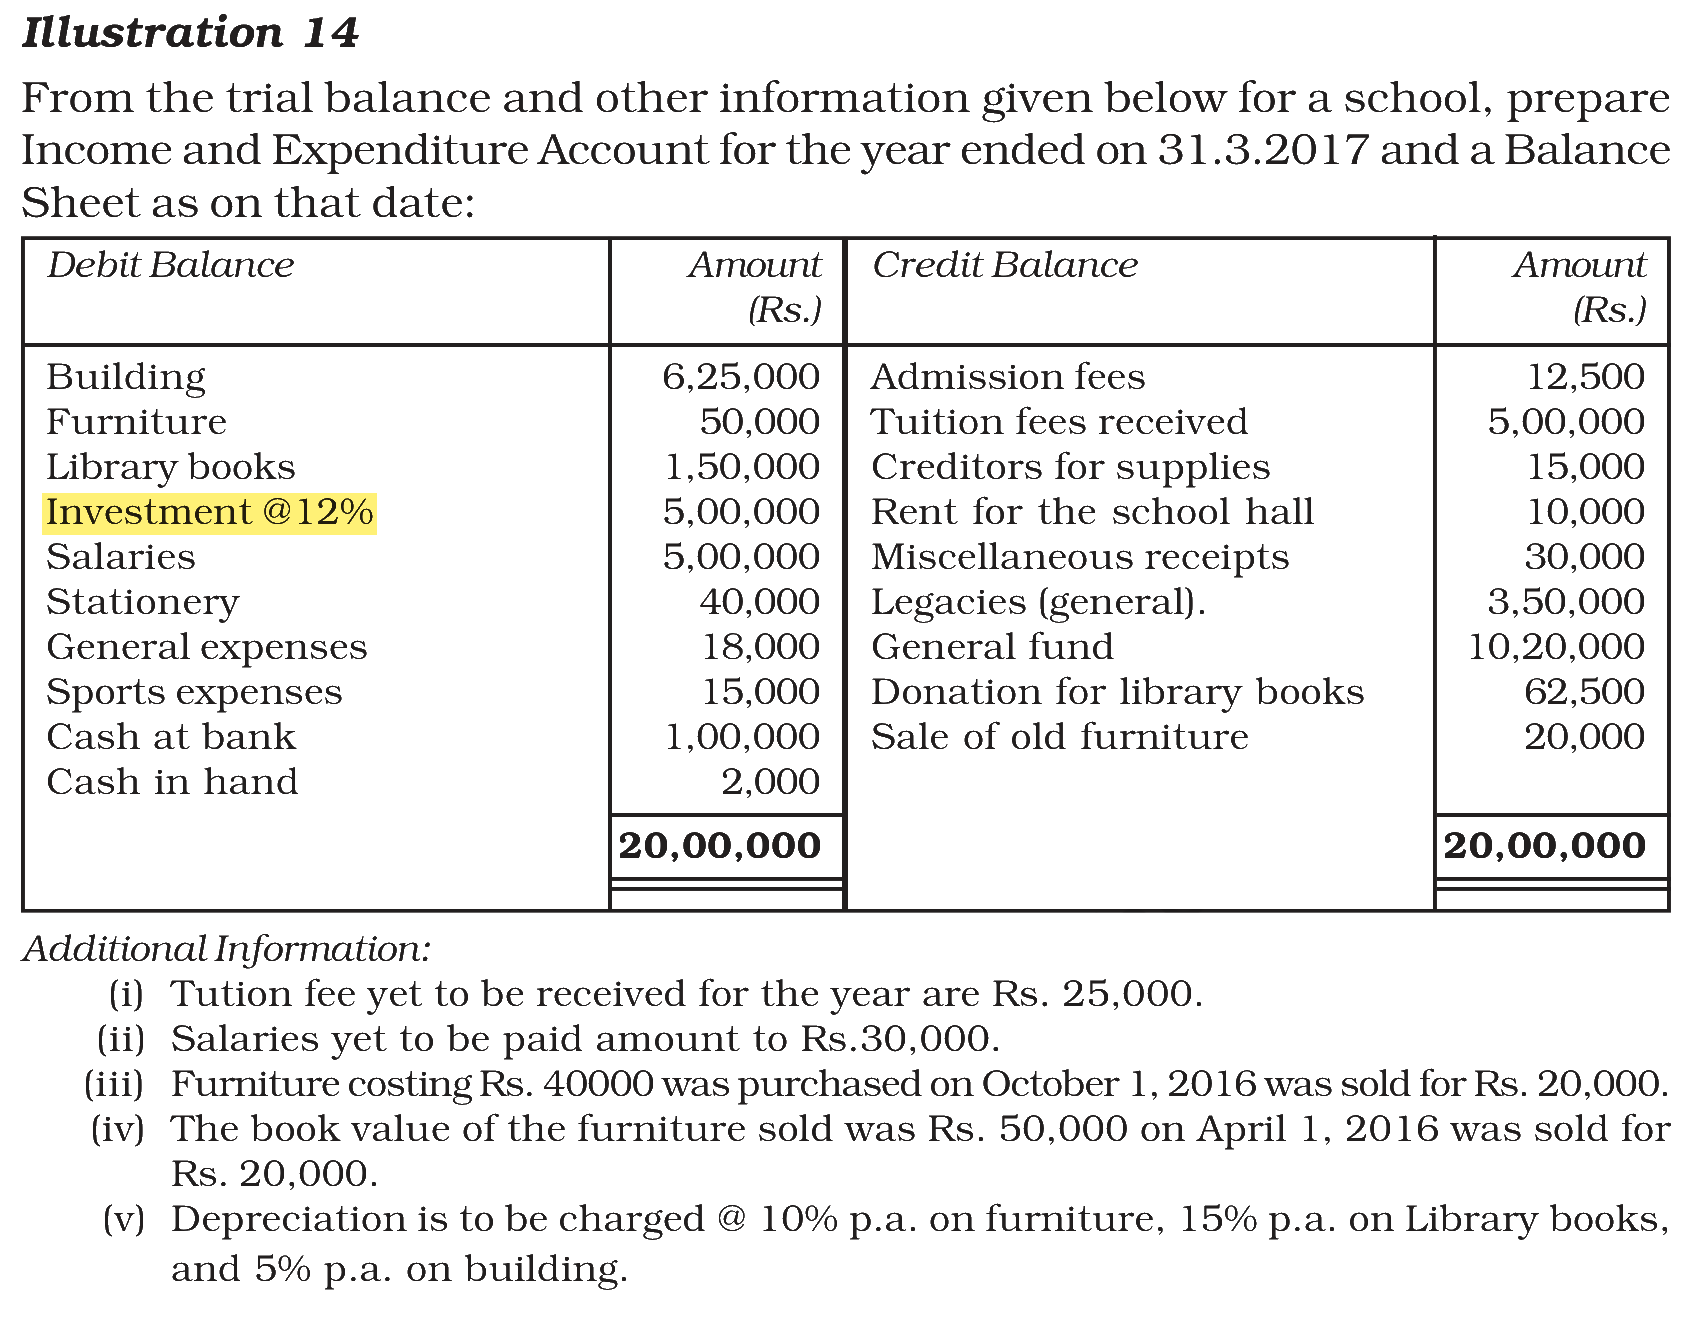
The Trial Balance of a school as on 31.3.2017 is
|
Debit Balance |
Amount (₹) |
Credit Balance |
Amount (₹) |
|
Building |
6,25,000 |
Admission fees |
12,500 |
|
Furniture |
50,000 |
Tuition fees received |
5,00,000 |
|
Library books |
1,50,000 |
Creditors for supplies |
15,000 |
|
Investment @12% (1.4.16) |
5,00,000 |
Rent for the school hall |
10,000 |
|
Salaries |
5,00,000 |
Miscellaneous receipts |
30,000 |
|
Stationery |
40,000 |
Legacies (general) |
3,50,000 |
|
General expenses |
18,000 |
General fund |
10,00,000 |
|
Sports expenses |
15,000 |
Donation for library books |
62,500 |
|
Cash at bank |
1,00,000 |
Sale of old furniture |
20,000 |
|
Cash in hand |
2,000 |
|
|
|
|
20,00,000 |
|
20,00,000 |
Additional Information:
The book value of the furniture sold was ₹50,000 on April 1, 2016 was sold for ₹20,000.
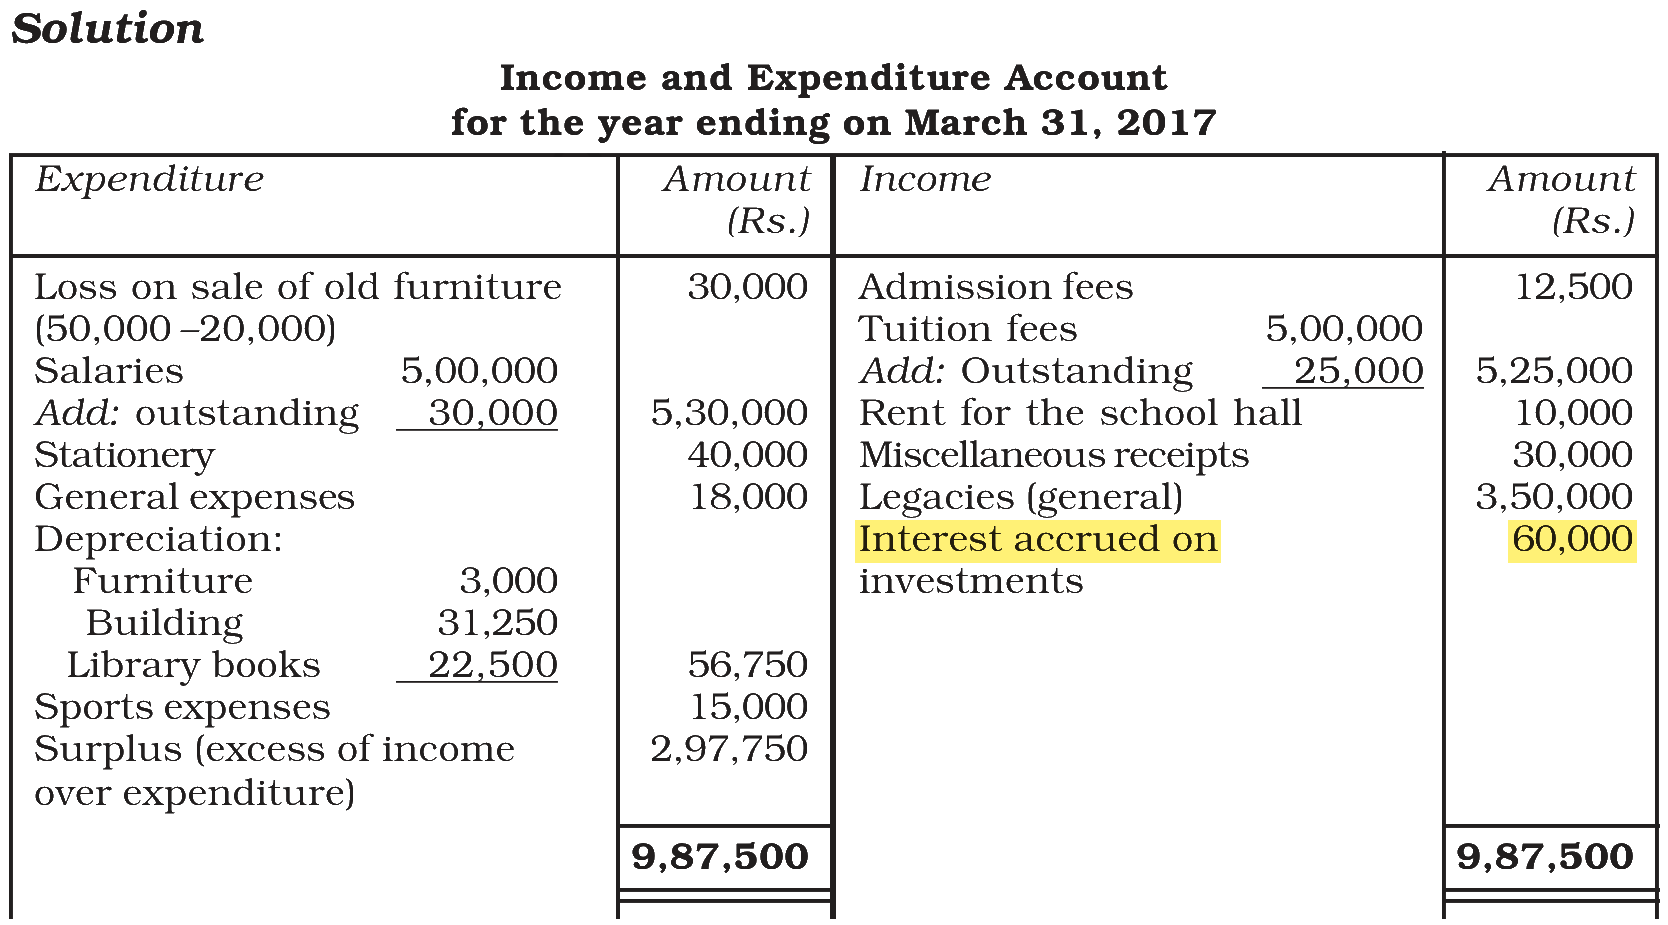
What amount of Interest on investment will be credited to Income and Expenditure account.
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → ₹60,000
The trial balance shows Investment @12% (1.4.16) of ₹5,00,000, held for the whole year up to 31.3.2017. No interest received appears in the trial balance, so the whole year’s interest is accrued.
Interest for the year:
= ₹5,00,000 × 12/100
= ₹60,000
The Income and Expenditure Account is prepared on the accrual basis, so the full ₹60,000 is credited to it, and the same amount is shown as interest accrued on the assets side of the Balance Sheet.
Note: This question is from the pre-rationalised NCERT book. The topic is not there in the latest NCERT book (2026-27), and it is also out of the CUET 2026 syllabus.
NCERT (Pre-rationalised edition):
|