Read the following information carefully and answer the next five questions.
G, K and B were partners running a partnership for last 10 years, sharing profit and loss in the ratio of 5:3:2. Post Covid, their firm was affected badly and started incurring losses. On 31st March,2023 they all decided to dissolve the firm due to continuous losses. Their capital balances were ₹4,00,000, ₹3,00,000 and ₹2,00,000 respectively. Firm had liabilities ₹80,000, cash balance ₹40,000, other sundry assets ₹8,50,000 and P&L A/c constituted the rest. Assets realised at 80% and liabilities were paid in full. There was unrecorded liability of ₹50,000 which was settled at ₹40,000. Realisation expenses amounted to ₹30,000 being paid by G on behalf of the firm.
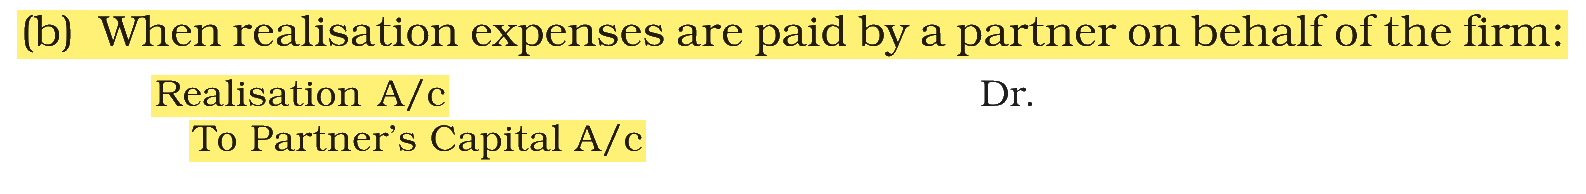
The entry for realisation expenses in the above case study will be-
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Realisation A/c Dr. To G's Capital A/c
Realisation expenses are the firm’s expense, so they are always debited to the Realisation Account. Here G paid them on the firm’s behalf, so the firm now owes G that amount and his capital account is credited:
Realisation A/c Dr. 30,000
To G’s Capital A/c 30,000
Realisation A/c Dr. To Cash A/c would be the entry only if the firm itself had paid the expenses.
NCERT (2026-27 edition):
|