A & B were partners in a partnership firm. Due to the ill health of B they decided to dissolve the firm. The position of assets and liabilities on the date of dissolution was:
| LIABILITIES | AMOUNT (₹) | ASSETS | AMOUNT (₹) |
| Loan by B | 20,000 | Goodwill | 30,000 |
| Capitals | Furniture | 40,000 | |
| A 1,00,000 | Building | 90,000 | |
| B 1,40,000 | 2,40,000 | Debtors | 50,000 |
| Cash | 50,000 | ||
| 2,60,000 | 2,60,000 |
It was agreed that following transactions will take place:
a) A wanted to start the business in sole proprietorship so he took building and furniture at 10% less than book value.
b) All the debtors proved good except a person C who did not pay ₹10,000
Following items appear on the Debit side of Realisation A/C except:
A. Transfer of Assets
B. Payment of liabilities
C. Provisions
D. Realisation expenses
E. Asset taken over by partner
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → C & E only
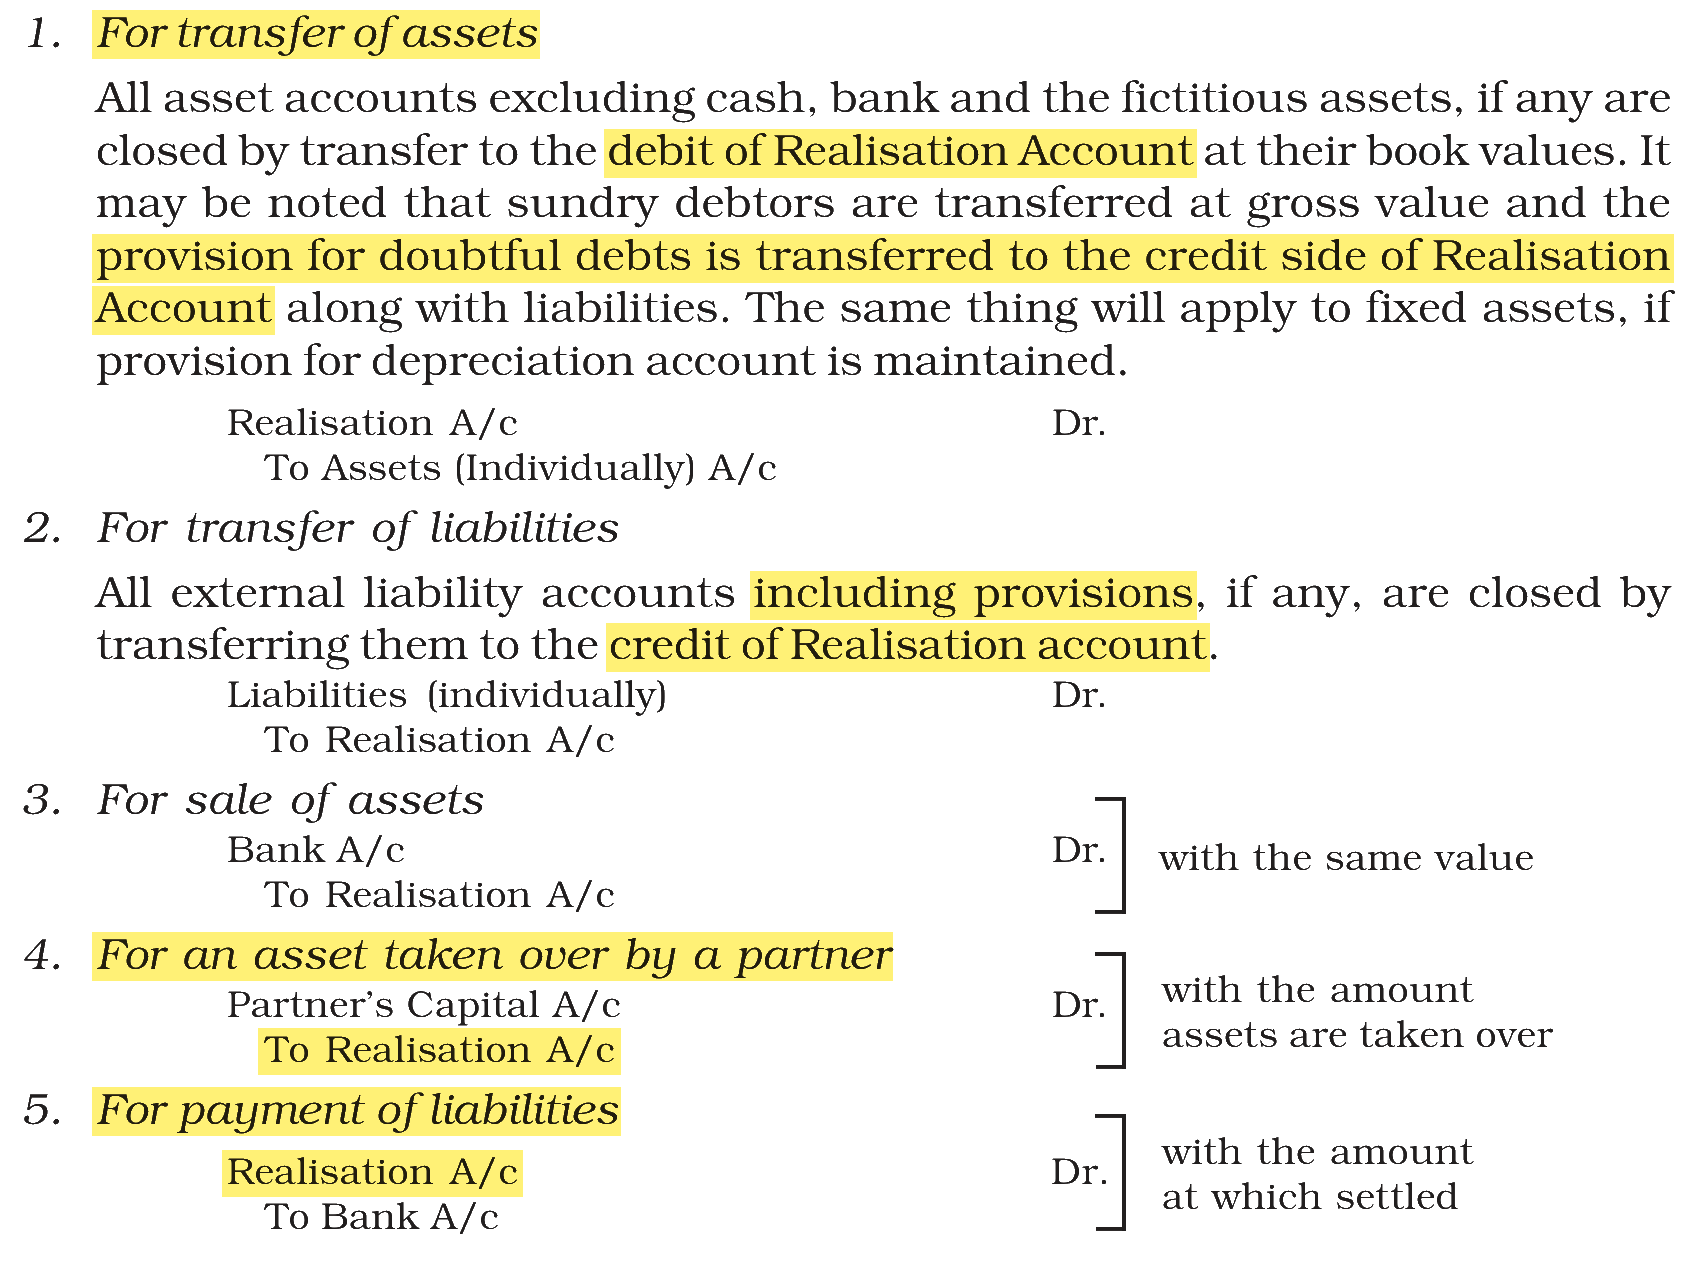
The Realisation Account is debited with the assets transferred to it and with every payment the firm makes in closing down. It is credited with liabilities and provisions transferred to it and with everything the firm receives or recovers.
(A) Transfer of assets — debit side (Realisation A/c Dr. To Assets).
(B) Payment of liabilities — debit side (Realisation A/c Dr. To Bank).
(C) Provisions — credit side; they are transferred along with the liabilities.
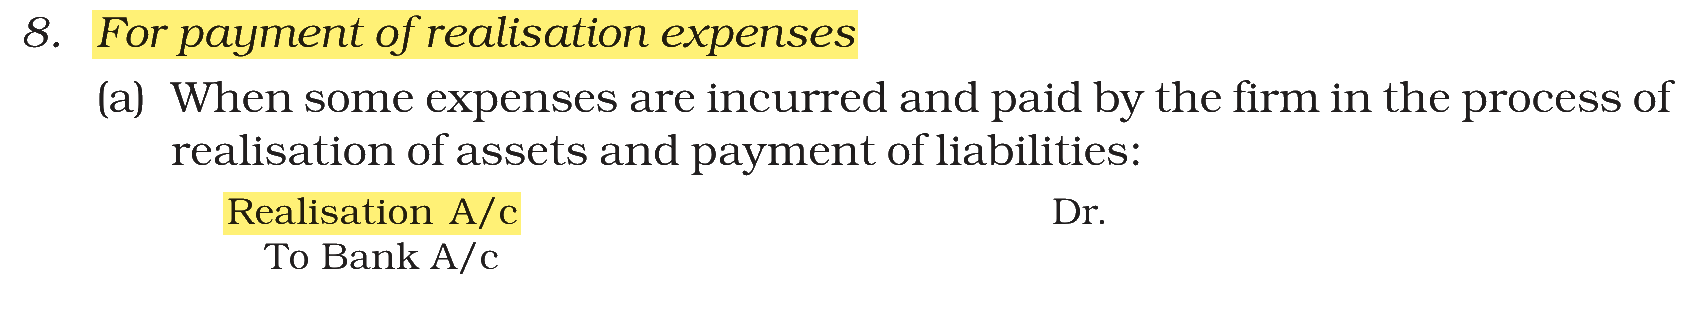
(D) Realisation expenses — debit side (Realisation A/c Dr. To Bank).
(E) Asset taken over by a partner — credit side (Partner’s Capital A/c Dr. To Realisation A/c).
NCERT (2026-27 edition):
|