In case a company issued shares of face value Rs 100 in consideration of a building purchased for Rs 10,80,000, at the following issue prices. Match List-I with List-II.
List-I (Issue price of share)
(A) Rs. 120
(B) Rs. 90
(C) Rs. 125
(D) Rs. 150
List-II (No. Of shares to be issued)
(I) 7,200
(II) 8,640
(III) 12,000
(IV) 9,000
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A) - (IV), (B) - (III), (C) - (II), (D) - (I)
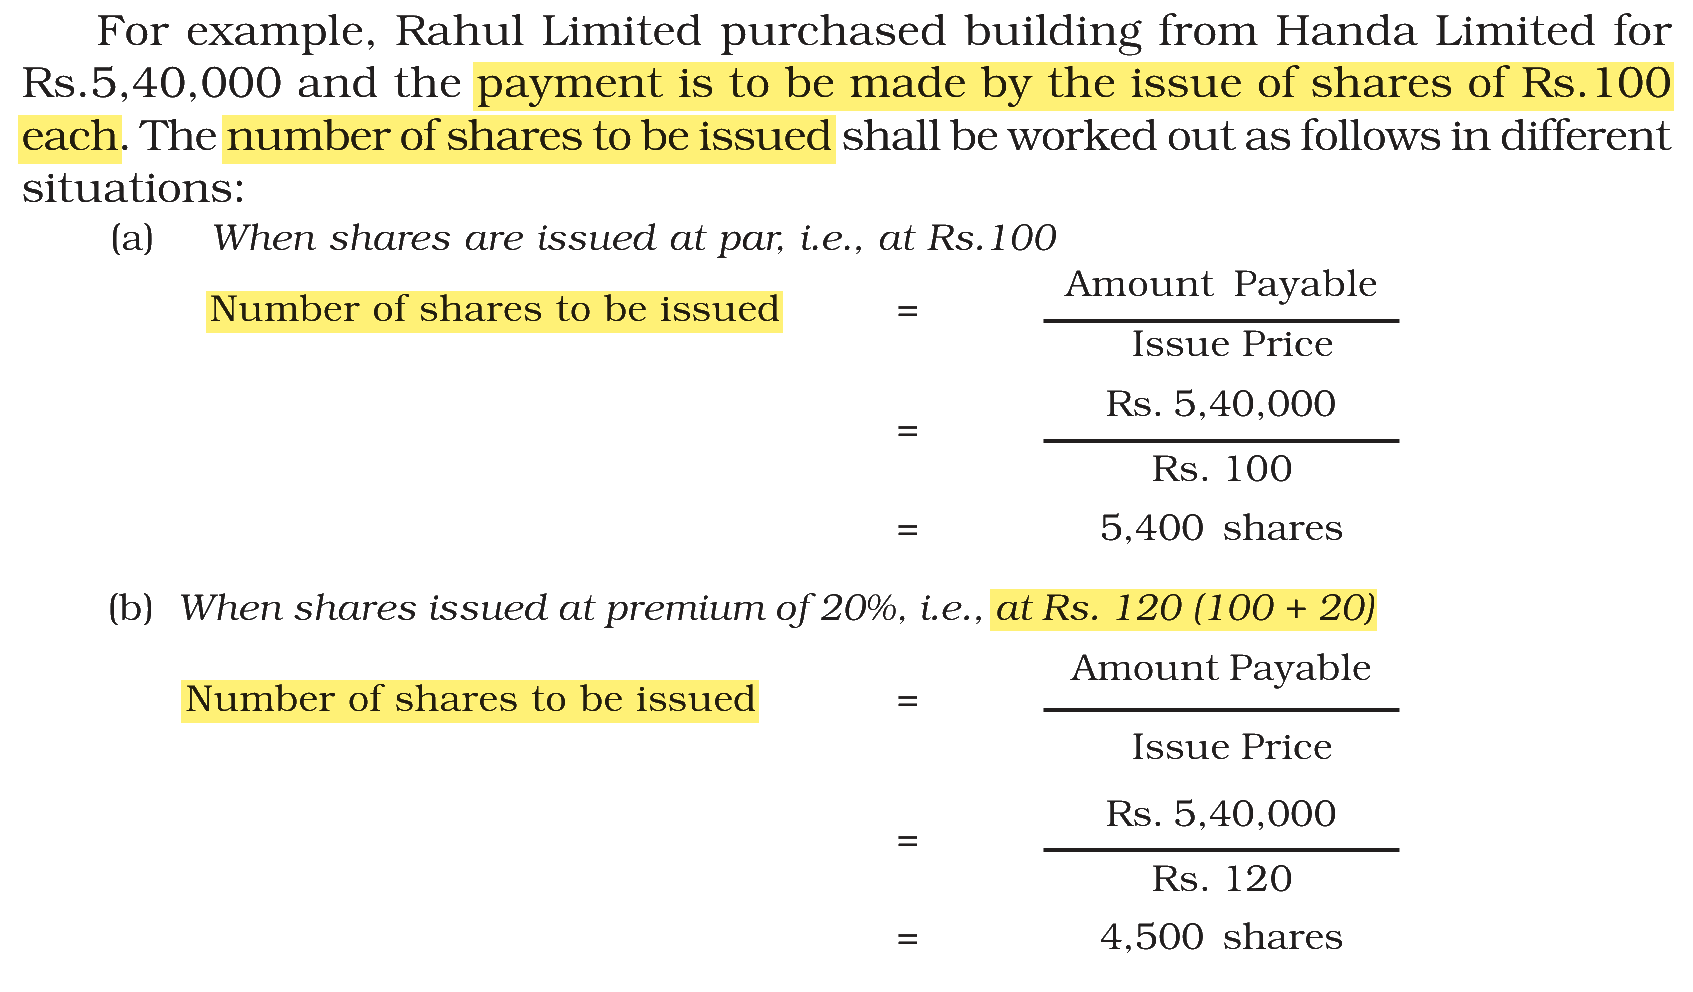
When shares are issued to a vendor for an asset, the number of shares = purchase price ÷ issue price per share. The face value of Rs. 100 decides only whether the issue is at par, a premium or a discount.
(A) Rs. 120 — this matches (IV) 9,000.
10,80,000 ÷ 120 = 9,000 shares
Shares issued at a premium of Rs. 20
(B) Rs. 90 — this matches (III) 12,000.
10,80,000 ÷ 90 = 12,000 shares
Shares issued at a discount of Rs. 10
(C) Rs. 125 — this matches (II) 8,640.
10,80,000 ÷ 125 = 8,640 shares
Shares issued at a premium of Rs. 25
(D) Rs. 150 — this matches (I) 7,200.
10,80,000 ÷ 150 = 7,200 shares
Shares issued at a premium of Rs. 50
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|