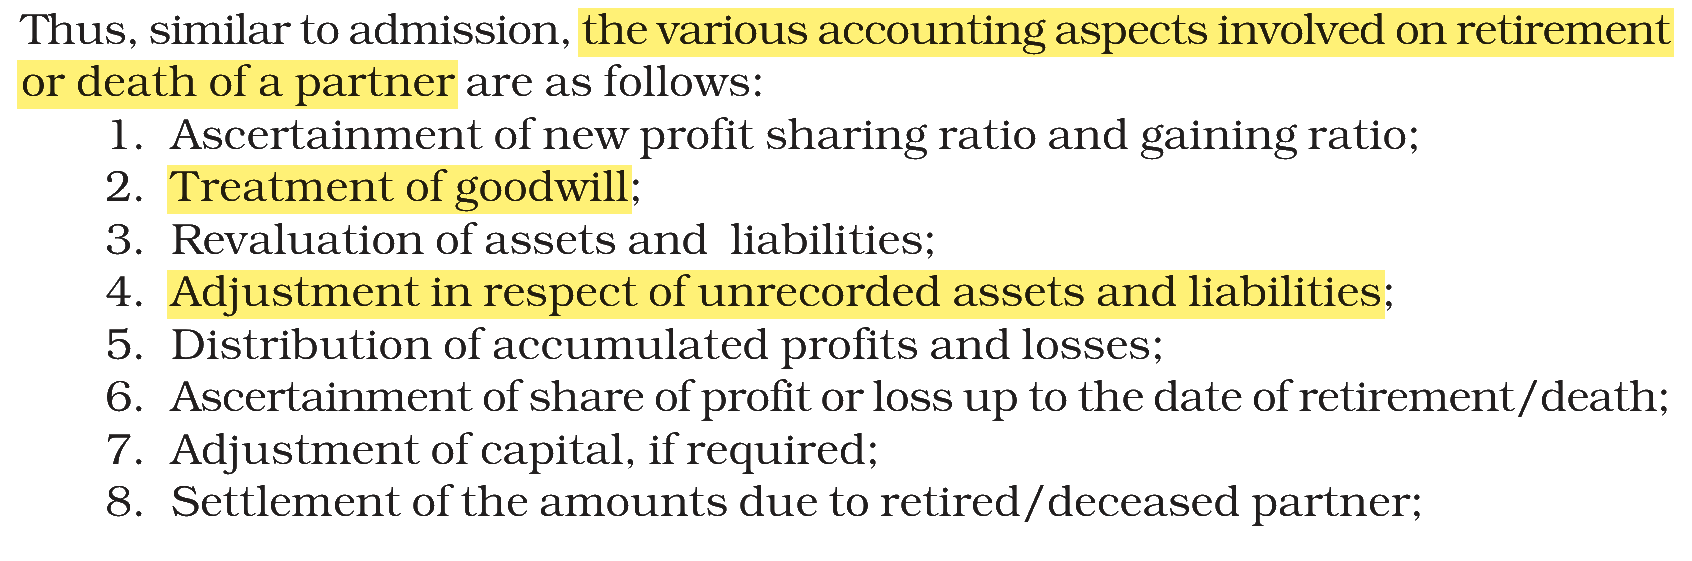
Various accounting aspects involved on death of a partner are as follows:
(A) Adjustment in respect of unrecorded assets and liabilities
(B) Treatment of goodwill
(C) Preparation of Realization A/c
(D) Preparation of Executor's loan A/c
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A), (B) and (D) only
On the death of a partner the firm usually continues with the remaining partners, so the work is the same as on retirement, except that the amount due is settled with the deceased partner’s executors.
(A) Adjustment in respect of unrecorded assets and liabilities Correct. Unrecorded assets and liabilities are brought into the books so that the deceased partner gets his fair share.
(B) Treatment of goodwill Correct. Goodwill is treated, as his share of goodwill is part of what is due to him.
(C) Preparation of Realization A/c Incorrect. A Realisation Account is prepared when the firm itself is dissolved and its assets sold; the death of a partner does not dissolve the firm here.
(D) Preparation of Executor’s loan A/c Correct. The amount due is transferred to the executors’ account; if it is not paid at once, it is kept as the executor’s loan.
NCERT (2026-27 edition):
NCERT (2026-27 edition): NCERT (2026-27 edition): |