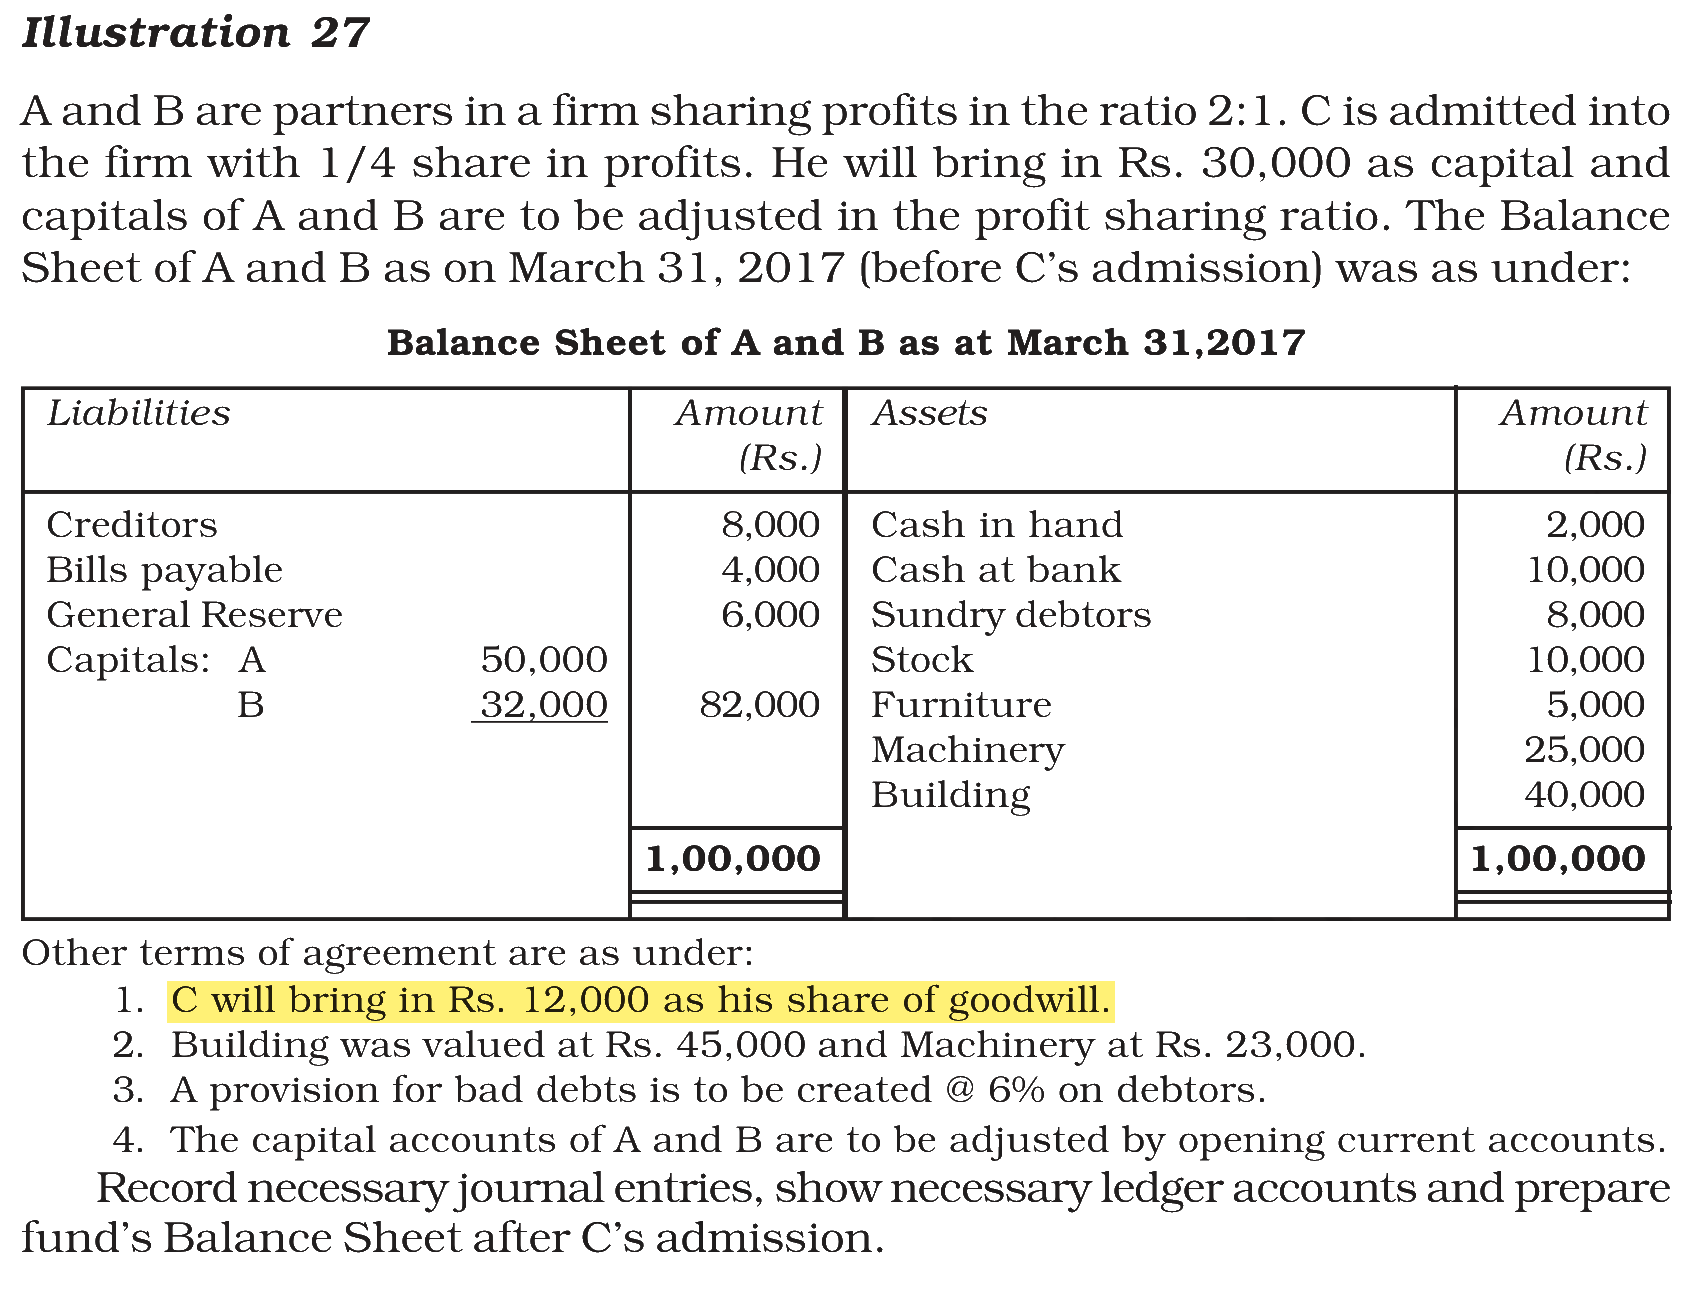
A and B are partners in a firm sharing profits in the ratio 2 : 1. C is admitted into the firm with 1/4 share in profits. He will bring in ₹30,000 as capital and capitals of A and B are to be adjusted in the profit sharing ratio. The balance sheet of A and B as on March 31, 2017 (before C's admission ) was as under :
Balance Sheet of A and B as at March 31,2017
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
| Creditors | 8,000 | Cash in hand | 2,000 |
| Bills payable | 4,000 | Cash at Bank | 10,000 |
| General Reserve | 6,000 | Sundry Debtors | 8,000 |
| Capital : A 50000 B 32000 |
82,000 | Stock | 10,000 |
| Furniture | 5,000 | ||
| Machinery | 25,000 | ||
| Building | 40,000 | ||
| 1,00,000 | 1,00,000 |
Other terms of agreement are as under :
1. C will bring in ₹12,000 as his share of goodwill.
2. Building was valued at ₹45,000 and Machinery at ₹23,000
3. A provision for bad debts is to be created @ 6% on debtors.
4. The capital accounts A and B are to be adjusted by opening current accounts.
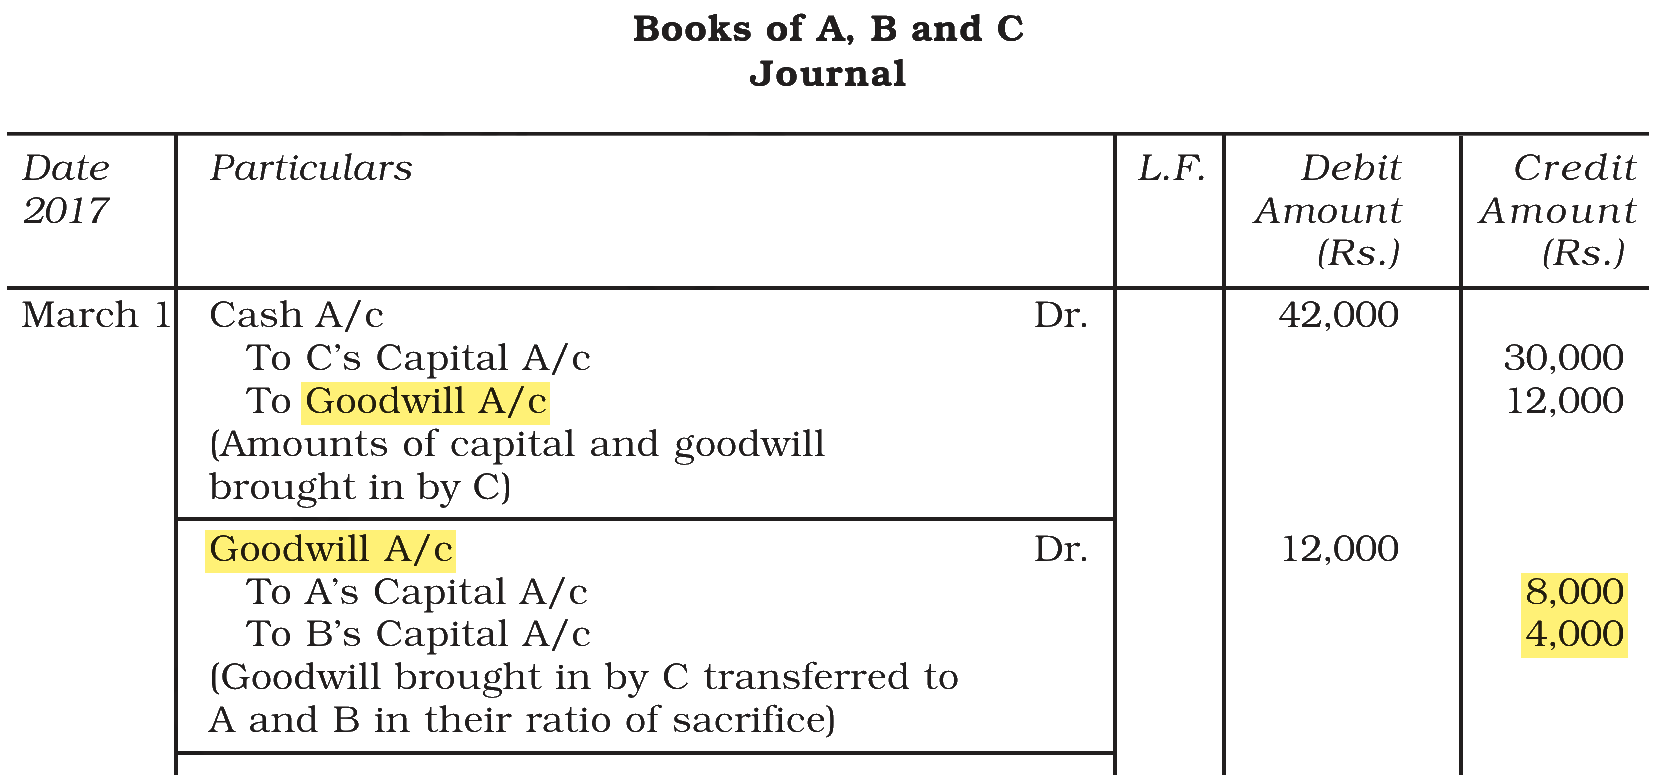
Journal entry for adjustment of Goodwill brought by new partner C.
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → a) Cash A/C Dr 12,000 To Goodwill/Premium A/C 12,000; b) Goodwill/Premium A/C Dr 12,000 To A’s Capital A/C 8,000 To B’s Capital A/C 4,000
Goodwill brought in cash by the new partner is first received (entry a) and then credited to the old partners who sacrificed their share, in the sacrificing ratio (entry b).
Sacrifice of each old partner (old share − new share):
A = 2/3 − 2/4 = 2/12
B = 1/3 − 1/4 = 1/12
Sacrificing ratio = 2 : 1
Goodwill shared:
A = ₹12,000 × 2/3 = ₹8,000
B = ₹12,000 × 1/3 = ₹4,000
NCERT (2026-27 edition):
|