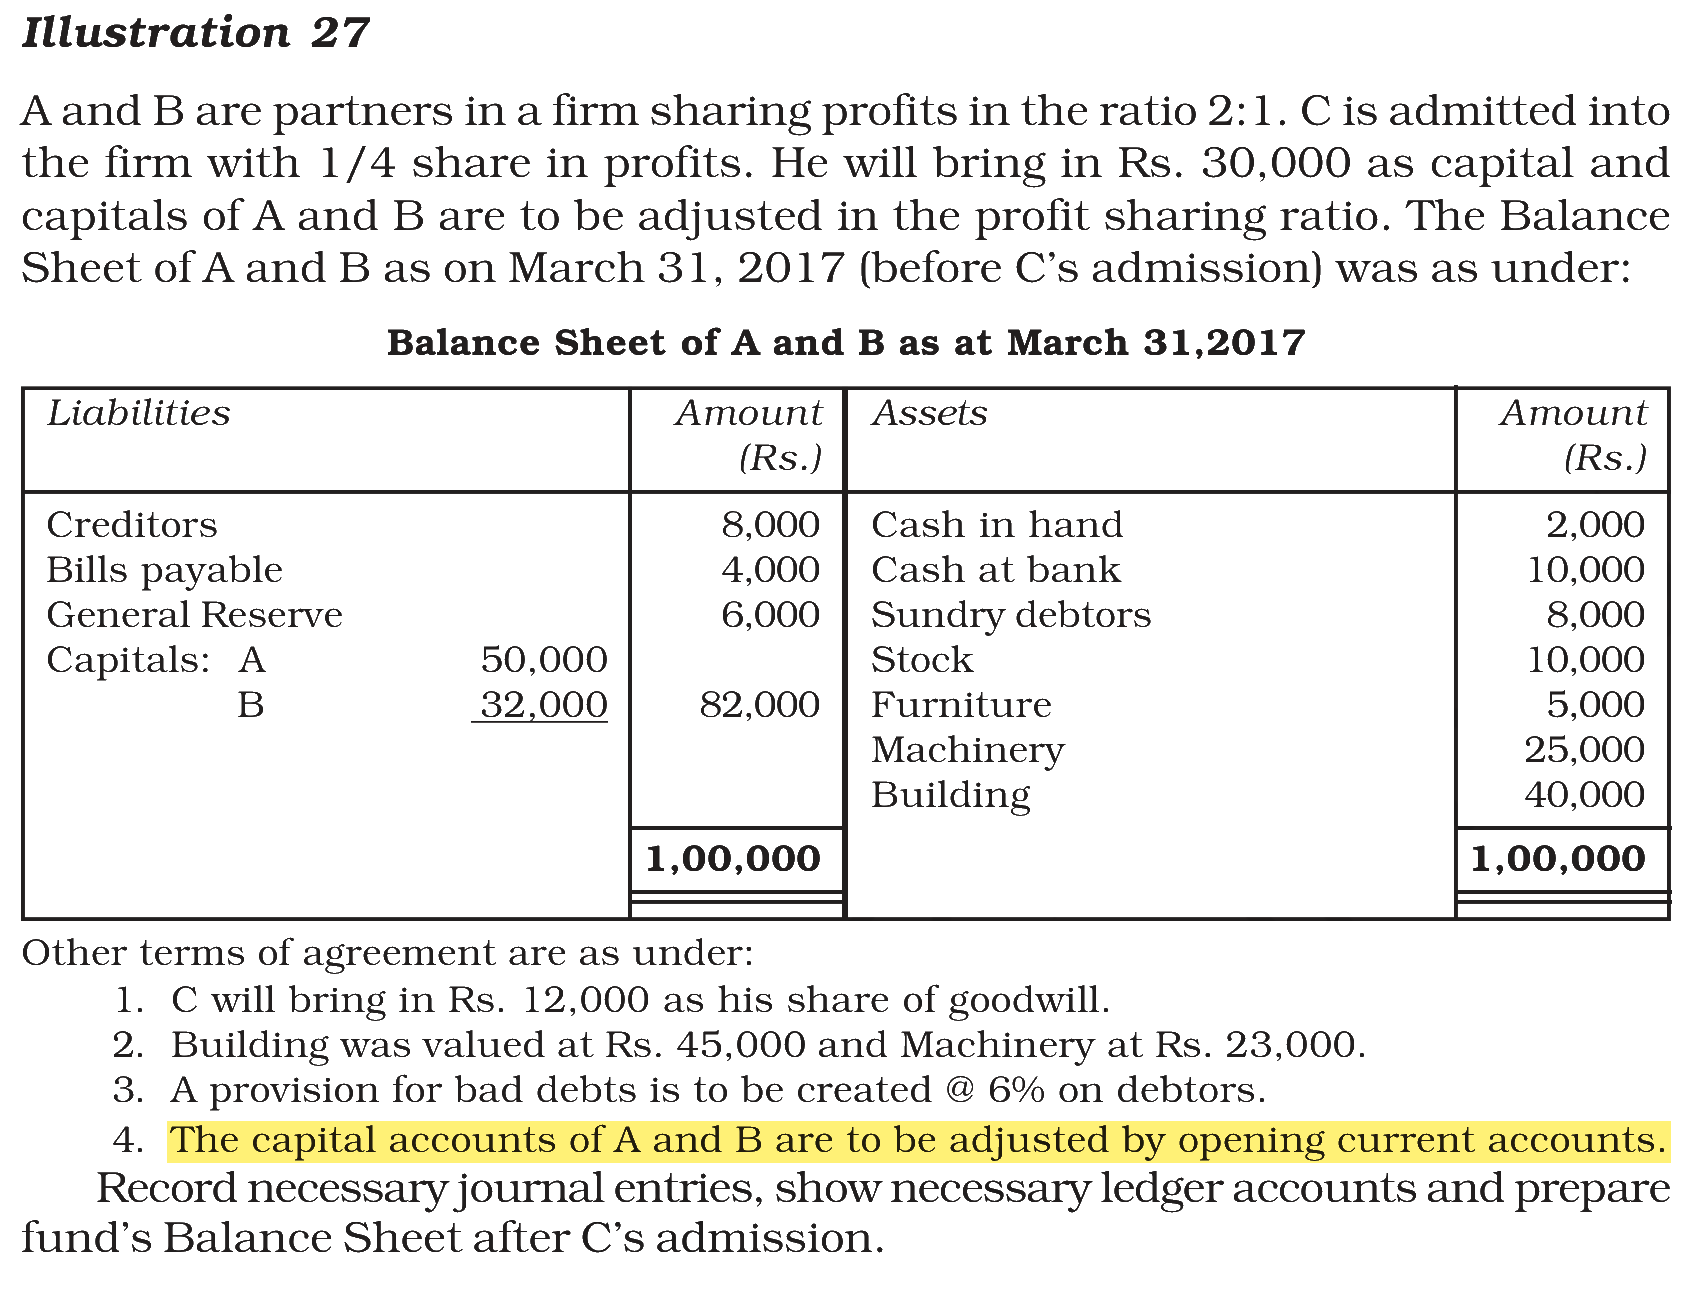
A and B are partners in a firm sharing profits in the ratio 2 : 1. C is admitted into the firm with 1/4 share in profits. He will bring in ₹30,000 as capital and capitals of A and B are to be adjusted in the profit sharing ratio. The balance sheet of A and B as on March 31, 2017 (before C's admission ) was as under :
Balance Sheet of A and B as at March 31,2017
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
| Creditors | 8,000 | Cash in hand | 2,000 |
| Bills payable | 4,000 | Cash at Bank | 10,000 |
| General Reserve | 6,000 | Sundry Debtors | 8,000 |
| Capital : A 50000 B 32000 |
82,000 | Stock | 10,000 |
| Furniture | 5,000 | ||
| Machinery | 25,000 | ||
| Building | 40,000 | ||
| 1,00,000 | 1,00,000 |
Other terms of agreement are as under :
1. C will bring in ₹12,000 as his share of goodwill.
2. Building was valued at ₹45,000 and Machinery at ₹23,000
3. A provision for bad debts is to be created @ 6% on debtors.
4. The capital accounts A and B are to be adjusted by opening current accounts.
Calculate the current account balances of A and B respectively.
Answer & explanation
Correct answer: option 2
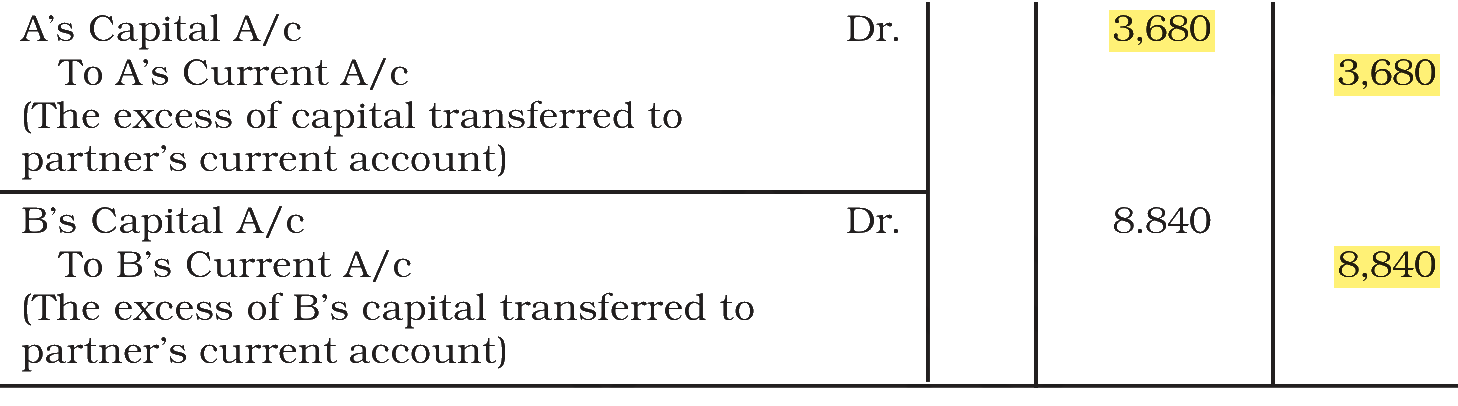
The correct answer is Option (2) → ₹3,680 and ₹8,840
The capitals of A and B are first brought to their adjusted figures (goodwill, general reserve, revaluation profit), then fixed in the new ratio; the excess over the fixed capital is moved to a current account.
New ratio = 2 : 1 : 1; C’s capital ₹30,000 for 1/4 share, so total capital = ₹1,20,000
A’s fixed capital = ₹1,20,000 × 2/4 = ₹60,000
B’s fixed capital = ₹1,20,000 × 1/4 = ₹30,000
A’s adjusted capital:
= ₹50,000 + ₹4,000 (reserve) + ₹1,680 (revaluation) + ₹8,000 (goodwill)
= ₹63,680
B’s adjusted capital:
= ₹32,000 + ₹2,000 + ₹840 + ₹4,000
= ₹38,840
Current account balances:
A = ₹63,680 − ₹60,000 = ₹3,680 (credit)
B = ₹38,840 − ₹30,000 = ₹8,840 (credit)
Note: In the NCERT solution below, the debit amount of B’s entry is printed as 8.840; it should read 8,840.
NCERT (2026-27 edition):
|