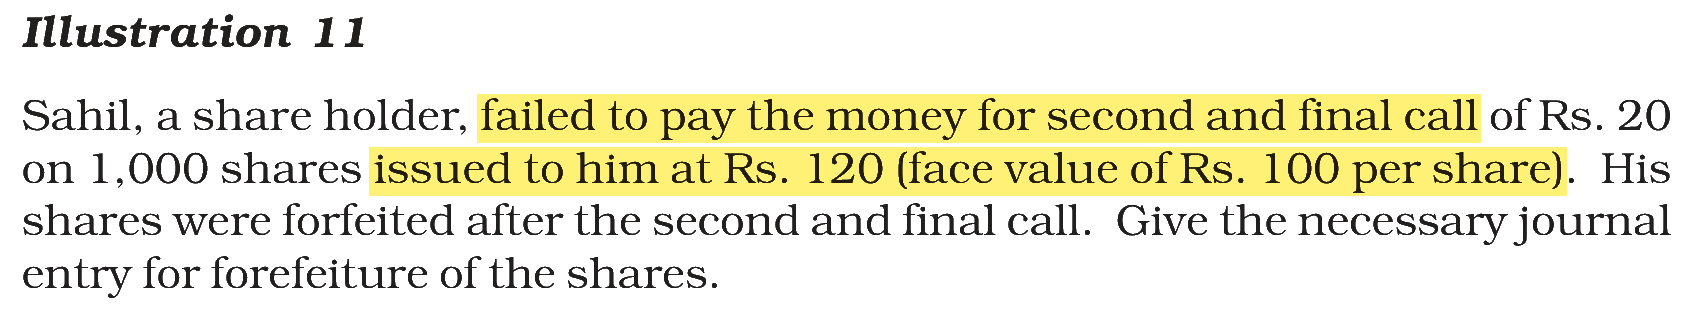
Sahil, a shareholder, failed to pay the money for second and final call of Rs. 30 on 2,000 shares issued to him at Rs. 220 (face value of Rs. 200 per share). His shares were forfeited after the second and final call. Share Forfeiture A/c will be credited with:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Rs. 3,40,000
Share Forfeiture A/c is credited with the money already received on the face value of the forfeited shares. A premium already received is not reversed, so it stays out of this figure. Only the second and final call of Rs. 30 is unpaid, so the Rs. 20 premium had already come in.
Issue price Rs. 220 = face value Rs. 200 + premium Rs. 20
Received on face value per share = Rs. 200 − Rs. 30 unpaid call = Rs. 170
Share Forfeiture A/c = 2,000 shares × Rs. 170 = Rs. 3,40,000
In the forfeiture entry, Share Capital is debited with Rs. 4,00,000 (2,000 × Rs. 200 called up), Calls in Arrears is credited with Rs. 60,000 (2,000 × Rs. 30), and the balance of Rs. 3,40,000 goes to Share Forfeiture.
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|