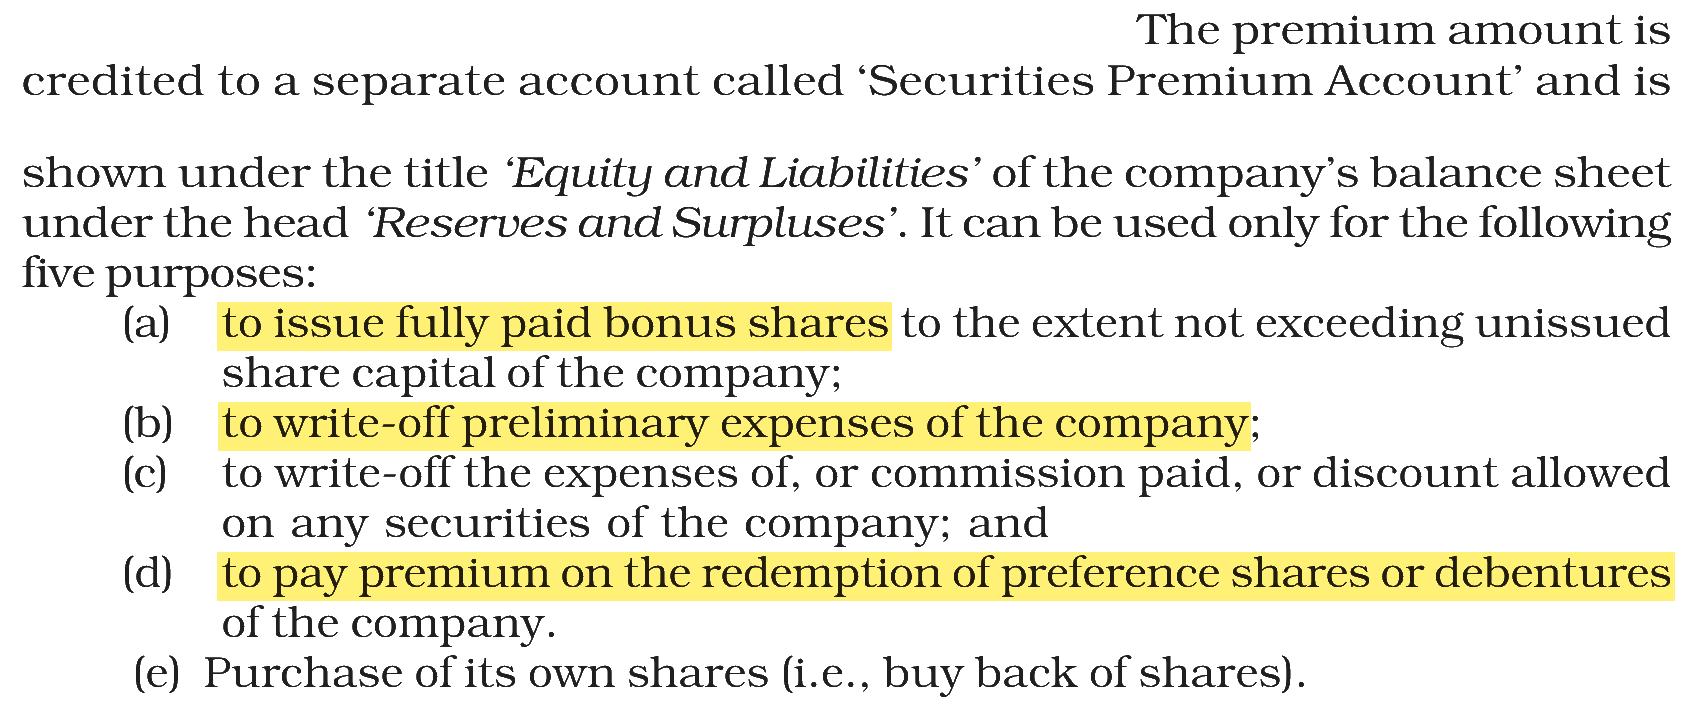
Securities Premium Reserve can be used for the following purposes.
(A) To issue fully paid bonus shares
(B) To write-off preliminary expenses of the company
(C) To pay premium on the redemption of preference shares and debentures of the company
(D) To distribute as a dividend to shareholders
(E) To write-off company losses
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → (A), (B) and (C) only
Securities premium is a capital receipt, so Section 52 of the Companies Act, 2013 allows it to be used only for set capital purposes, never as a distribution of profit.
(A) To issue fully paid bonus shares — True. Bonus shares may be issued out of it.
(B) To write-off preliminary expenses of the company — True. Writing off preliminary expenses is one of the permitted uses.
(C) To pay premium on the redemption of preference shares and debentures of the company — True. The premium payable on redemption may be met from it.
(D) To distribute as a dividend to shareholders — False. Dividend is paid out of profits; a capital receipt cannot be distributed.
(E) To write-off company losses — False. Trading losses cannot be written off against securities premium.
NCERT (2026-27 edition):
|