Match List-I with List-II.
| LIST I (Different accounts) |
LIST II (Related transaction) |
| (A) Profit and loss account | (I) Dissolution of partnership |
| (B) Profit and loss appropriation account | (II) Dissolution of firm |
| (C) Revaluation account | (III) Interest on loan to partner |
| (D) Realization account | (IV) Transfer to reserve |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A) - (III), (B) - (IV), (C) - (I), (D) - (II)
Each account in List-I has its own job in partnership accounts.
(A) profit and loss account. — this matches (III) interest on loan to partner. Interest on a loan to or from a partner is a charge or income of the business, worked out before the profit is found, so it goes through the Profit and Loss Account.
(B) profit and loss appropriation account. — this matches (IV) transfer to reserve. The appropriation account shows how the net profit is divided: partners’ salary, commission, interest on capital and any amount transferred to reserve.
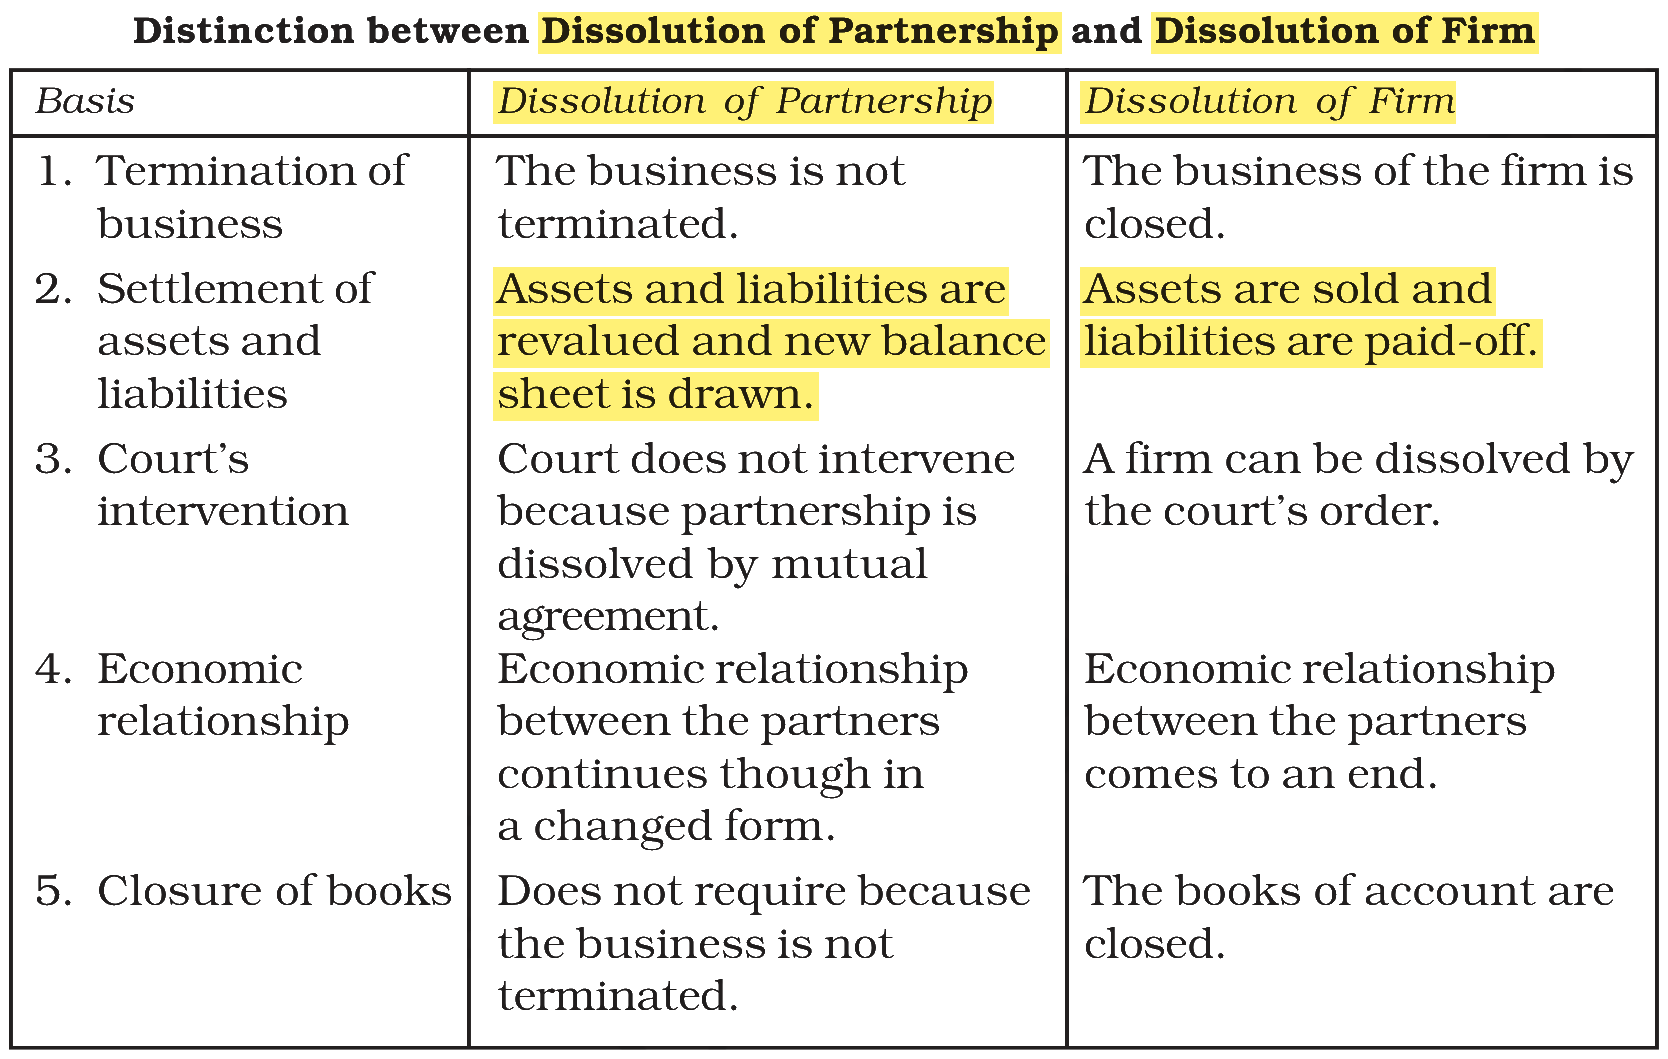
(C) revaluation account — this matches (I) dissolution of partnership. On a change in the agreement (admission, retirement, death) the partnership is dissolved but the firm goes on, so assets and liabilities are revalued through the Revaluation Account.
(D) realization account. — this matches (II) dissolution of firm. When the firm itself is dissolved, assets are sold and liabilities paid through the Realisation Account.
NCERT (2026-27 edition): NCERT (2026-27 edition): NCERT (2026-27 edition): NCERT (2026-27 edition):
|