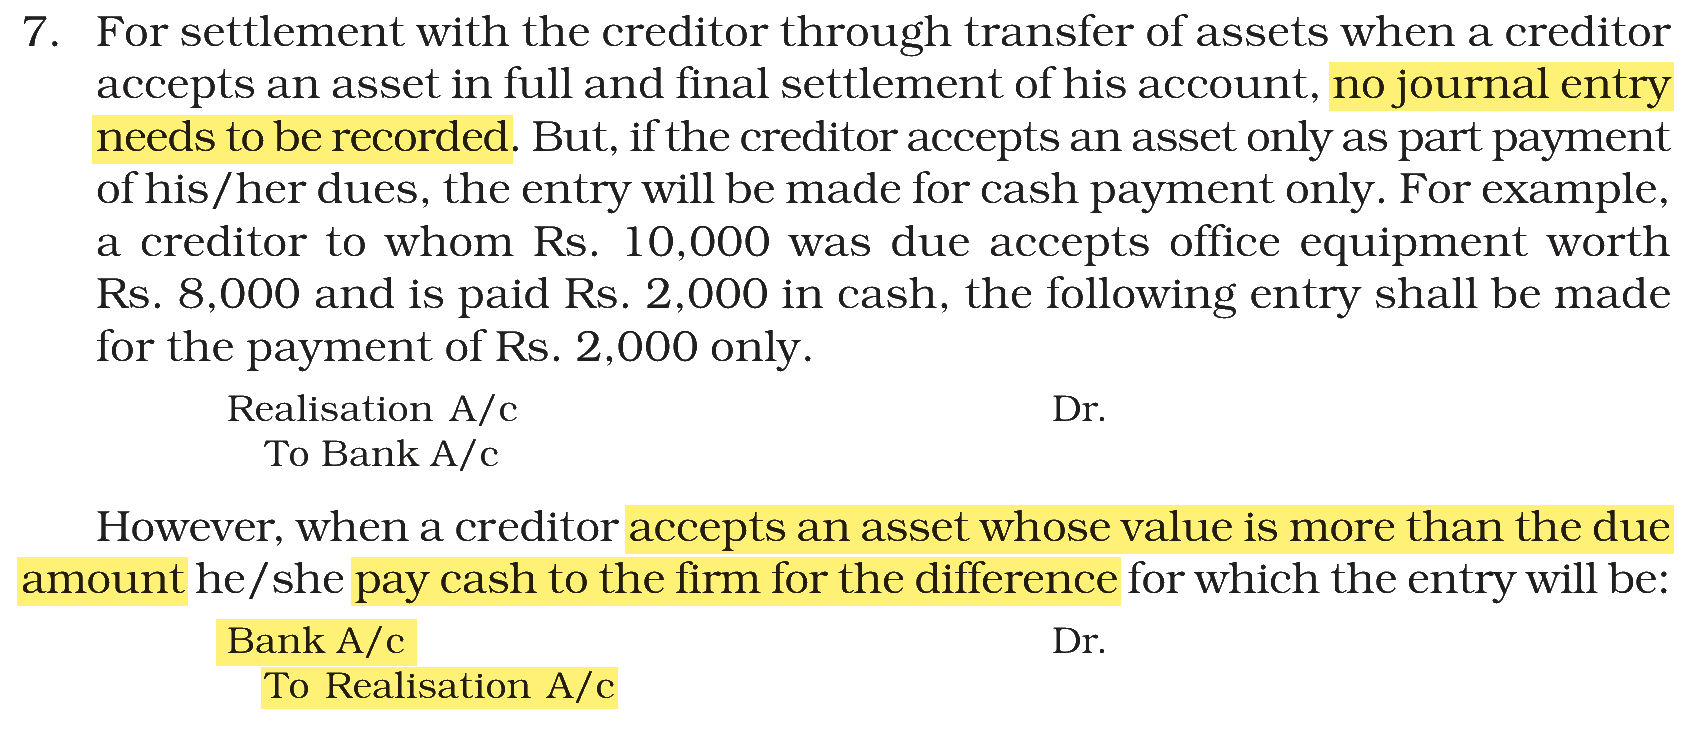
At the time of the Dissolution of the Partnership firm, “Creditors were Rs. 1,00,000. They accepted buildings valued at Rs. 1,20,000 and paid cash to the firm Rs. 30,000”.
Necessary journal entry would be :
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Cash A/c Dr. Rs. 30,000, to Realisation A/c Rs. 30,000
When a creditor takes over an asset in settlement of his dues, the transfer of the asset itself needs no entry, since both the asset and the creditor are already in the Realisation Account. Here the building is worth more than what is owed to the creditors, so the creditors pay cash to the firm for the difference, and only that cash is recorded:
Cash A/c Dr. 30,000
To Realisation A/c 30,000
Cash comes in, so Cash A/c is debited. Realisation A/c is credited because this cash is part of what the assets finally bring in.
NCERT (2026-27 edition):
|