On dissolution of a firm, partner's spouse loan account is transferred to:
Answer & explanation
Correct answer: option 1
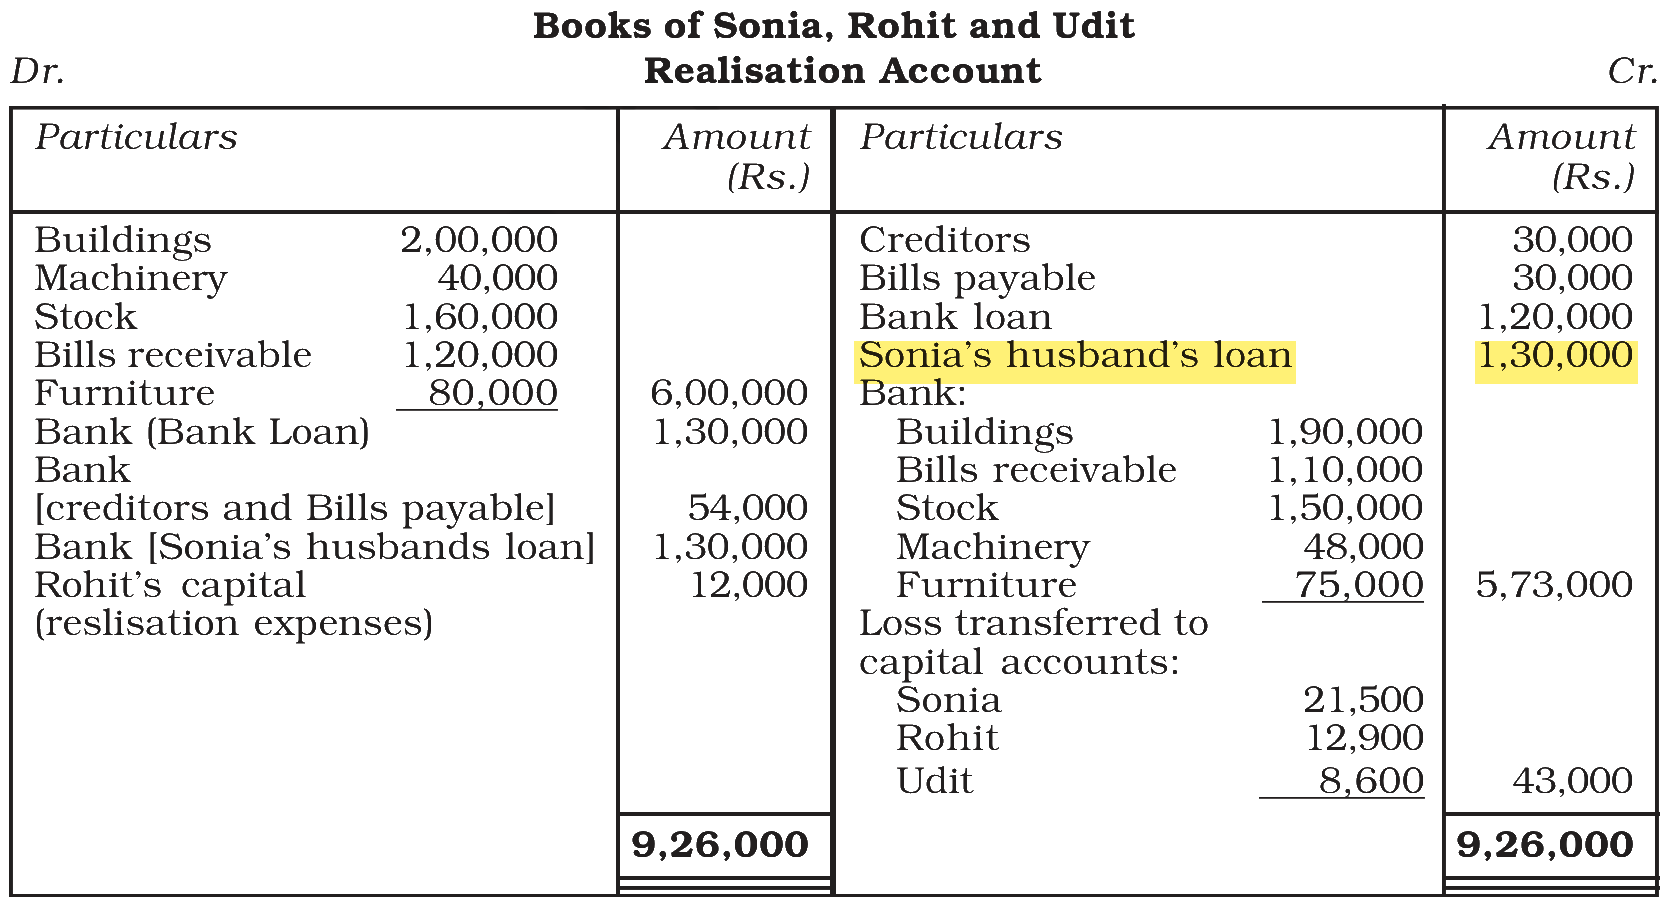
The correct answer is Option (1) → Realisation Account
A loan given to the firm by a partner’s wife or husband is money owed to an outsider. The lender is not a partner, so the loan is an outside liability and is transferred to the Realisation Account with the other liabilities:
Mrs. X’s Loan A/c Dr.
To Realisation A/c
Only a partner’s own loan stays out of Realisation; it is paid separately, after the outside creditors and before capital.
Why the other options are incorrect
Option (2) Partner’s Capital Account — Incorrect. The capital account records what the partner himself put in. His spouse’s money is not his capital, and the firm owes it to the spouse.
Option (3) Partner’s Current Account — Incorrect. Current accounts are closed into capital on dissolution; outside liabilities are never transferred to them.
Option (4) Bank Account — Incorrect. The Bank Account records the payment when it is made. The liability is first transferred to Realisation, so the account shows whether it was settled at, above or below book value.
NCERT (2026-27 edition): NCERT (2026-27 edition):
|