A, B and C were partner's in a firm sharing profit and losses in the Ratio of 5 : 3 : 2. They admitted D into partnership for 1/5 share of profit which he takes equally from A and B. D brought sufficient amount of goodwill in cash Capital brought in by is Rs. 50,000. On the date of admission the Balance Sheet of A, B and C was as follows :
Balance Sheet as on 31st March, 2021
| Liability | Rs. | Assets | Rs. |
|---|---|---|---|
| Capital | Building and Furniture | 1,50,000 | |
| A 1,00,000 | Debtors 55,000 | ||
| B 60,000 | Provision 5,000 | 50,000 | |
| C 40,000 | 2,00,000 | Cash | 20,000 |
| Creditors | 50,000 | Profit and Loss (2020-21) | 30,000 |
| 2,50,000 | 2,50,000 |
Goodwill is to be valued at 3 years purchase of average profit of last 4 years which were Rs. 60,000 (2017-18), Rs. 60,000 (18-19), Rs. 30,000 (19-20). On revaluation it was found that all debtors are good.
What would be the effect of the line "All Debtors are good.
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Provision for Doubtful Debt is Credited to Revaluation Account
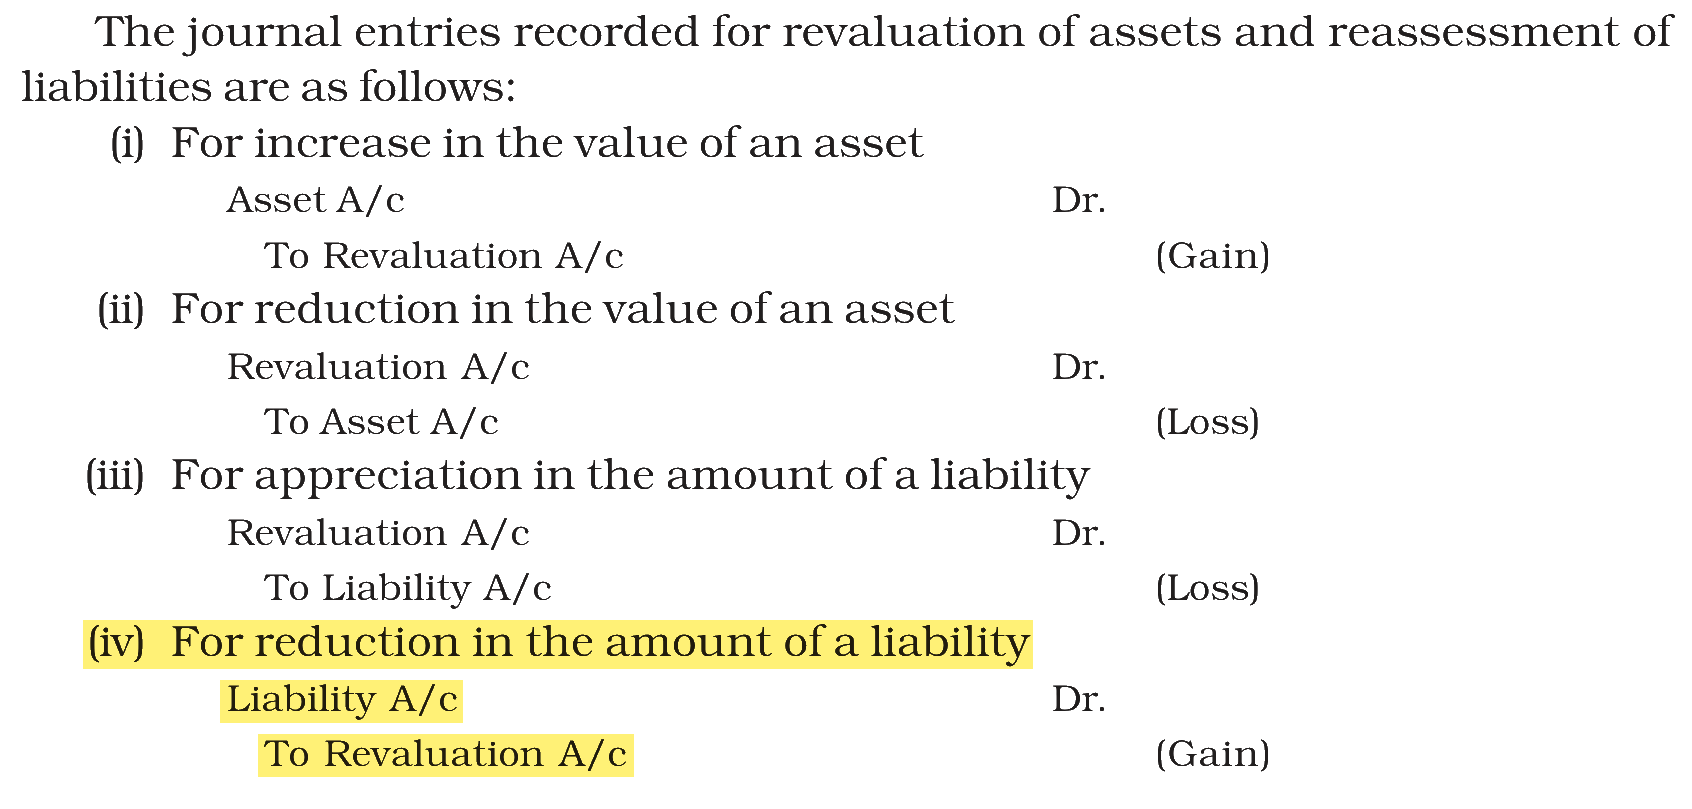
The balance sheet shows a provision of Rs. 5,000 against debtors of Rs. 55,000. If all debtors are good, the provision is no longer needed. Removing it is a reduction in a liability, which is a gain credited to the Revaluation Account:
Provision for Doubtful Debts A/c Dr. Rs. 5,000
To Revaluation A/c Rs. 5,000
Option (1) Provision for Doubtful debt is Debited to old partner Capital A/c — Incorrect. The provision does not go straight to the partners; the gain passes through the Revaluation Account first.
Option (2) Provision for Doubtful Debt is Debited to Revaluation Account — Incorrect. Debiting the Revaluation Account records a loss, as when a provision is created or raised, not when it is written back.
Option (3) Provision for Doubtful Debt is Credited to old partner's Capital A/c — Incorrect. The partners' capital accounts receive only the net result of the Revaluation Account, in the old ratio, not the provision directly.
Option (4) Provision for Doubtful Debt is Credited to Revaluation Account — Correct. The provision of Rs. 5,000 is carried to the credit of the Revaluation Account as a gain.
NCERT (2026-27 edition):
|