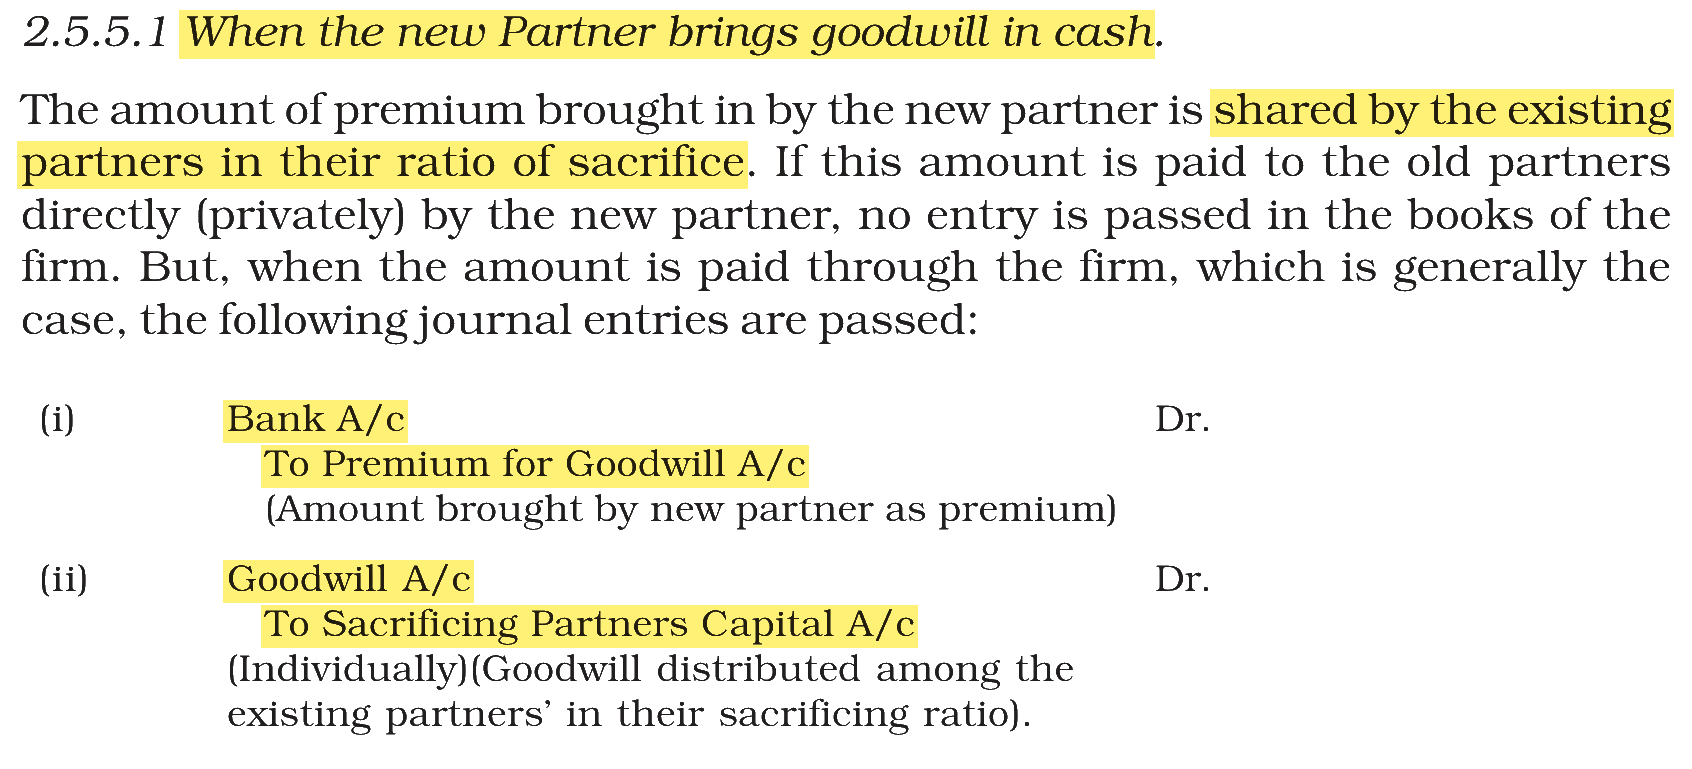
In case of admission of a new partner, Match List-I with List-II.
| LIST-I | LIST-II | ||
| A. | New partner bring goodwill in cash | I. | Premium for Goodwill A/c Dr To Old Partners' Capital A/c |
| B. | Goodwill already exists in books | II. | New Partner's Current A/c Dr. To Sacrificing Partners' Capital A/c |
| C. | New partner does not bring goodwill | III. | Bank A/c Dr. To Premium for Goodwill A/c |
| D. | Premium shared by sacrificing partner | IV. | Old Partner's Capital A/c Dr. To Goodwill A/c |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → A-III, B-IV, C-II, D-I
Goodwill on admission belongs to the old partners. The new partner compensates the sacrificing partners for the share of future profits he takes from them, either in cash or through his current account, and any goodwill already in the books is first written off.
(A) New partner bring goodwill in cash — this matches (III) Bank A/c Dr. To Premium for Goodwill A/c. The cash brought in for goodwill is first received in the bank and credited to Premium for Goodwill Account.
(B) Goodwill already exists in books — this matches (IV) Old Partner’s Capital A/c Dr. To Goodwill A/c. Existing goodwill is written off among the old partners in their old ratio, so that it is not counted twice when the new partner’s share is adjusted.
(C) New partner does not bring goodwill — this matches (II) New Partner’s Current A/c Dr. To Sacrificing Partners’ Capital A/c. The share of goodwill he does not bring in cash is debited to his current account, and the sacrificing partners are credited for it.
(D) Premium shared by sacrificing partner — this matches (I) Premium for Goodwill A/c Dr. To Old Partners’ Capital A/c. The premium received is then transferred to the old partners in their sacrificing ratio, which closes the Premium for Goodwill Account (in this entry the same account is called Goodwill Account).
NCERT (2026-27 edition):
NCERT (2026-27 edition): |