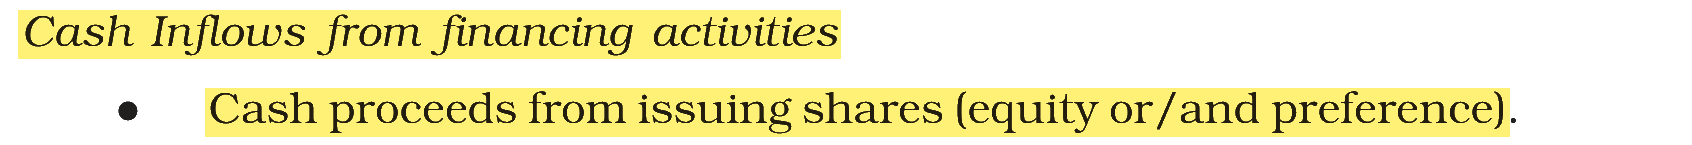Match List – I with List – II.
|
List – I |
List – II |
|
(A) Cash Inflows & Operating Activities |
(I) Proceeds from issue of preference or equity shares |
|
(B) Cash Inflows & Financing Activities |
(II) Receipt from royalties, fees, commission and other revenues |
|
(C) Cash Inflows & Investing Activities |
(III) Payment of Taxes |
|
(D) Cash Outflows & Operating Activities |
(IV) Proceeds from disposal of Machinery |
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → (A)-(II), (B)-(I), (C)-(IV), (D)-(III)
Every cash flow is placed under the activity that gives rise to it: operating (the main revenue-earning activities), investing (buying and selling long-term assets and investments) or financing (raising and repaying long-term funds).
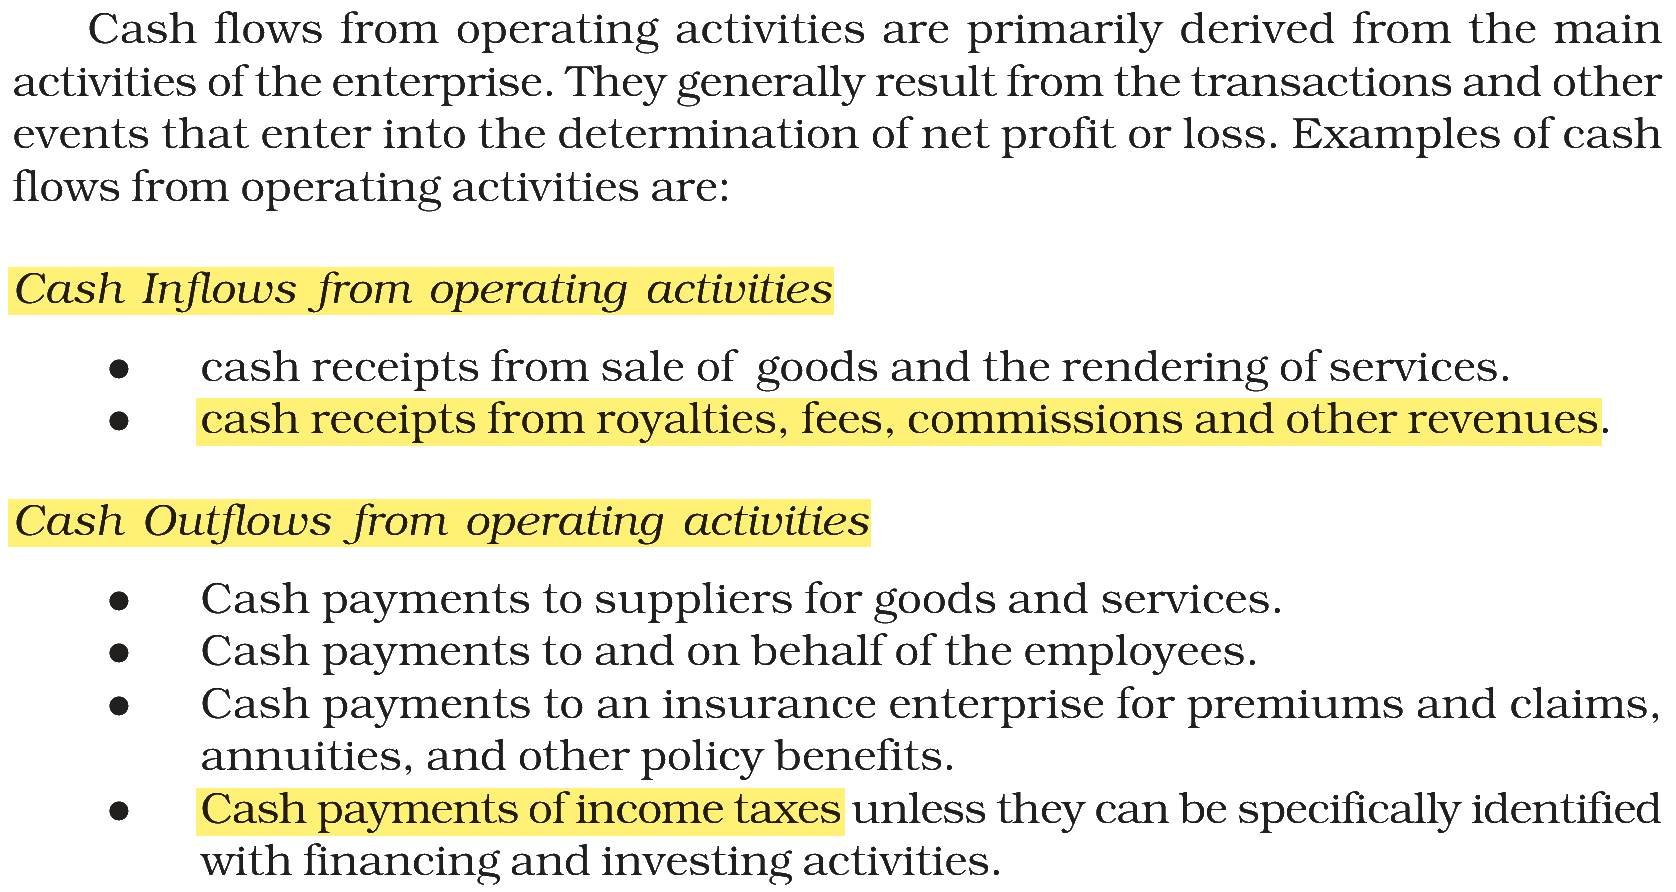
(A) Cash Inflows & Operating Activities — this matches (II) Receipt from royalties, fees, commission and other revenues. These are revenues earned from the main activities of the business, so the cash received is an operating inflow.
(B) Cash Inflows & Financing Activities — this matches (I) Proceeds from issue of preference or equity shares. Issuing shares raises owners’ capital, which changes the size of the capital of the enterprise, so the cash received is a financing inflow.
(C) Cash Inflows & Investing Activities — this matches (IV) Proceeds from disposal of Machinery. Machinery is a fixed asset; cash from selling it is an investing inflow.
(D) Cash Outflows & Operating Activities — this matches (III) Payment of Taxes. Income tax is paid out of the profit earned from operations, so it is an operating outflow unless it can be tied to a particular investing or financing activity.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|