Match List I with List II
|
LIST I |
LIST II |
|
A. Super Profit |
I. Actual Average Profit - Normal Profit |
|
B. Normal Profit |
II. Super Profit × 100 / Normal rate of return |
|
C. Goodwill |
III. Total Assets - Outside Liabilities |
|
D. Capital Employed |
IV. (Capital Employed × Normal Rate of Return) / 100 |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → A-I, B-IV, C-II, D-III
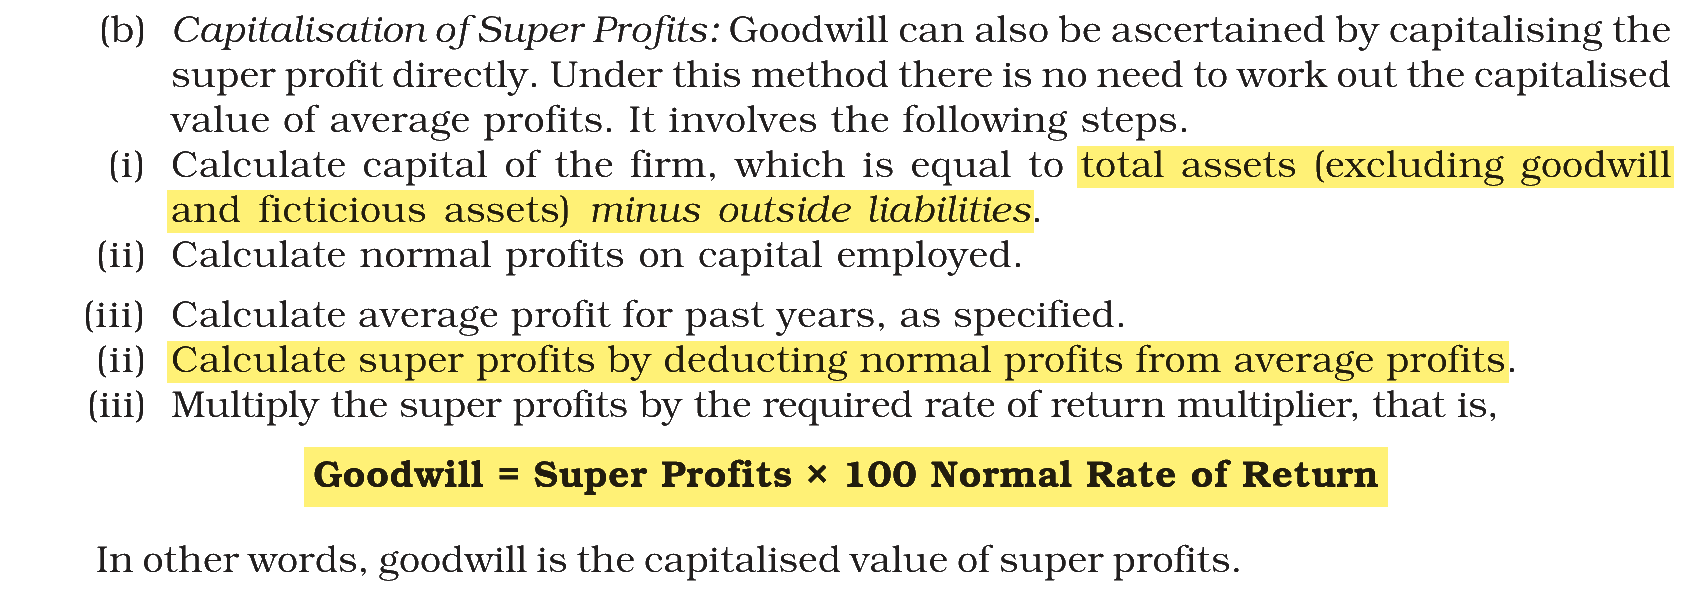
Each term of goodwill valuation by the super profits method has its own formula:
(A) Super Profit — this matches (I) Actual Average Profit - Normal Profit. Super profit is the excess of the average profit over the normal profit.
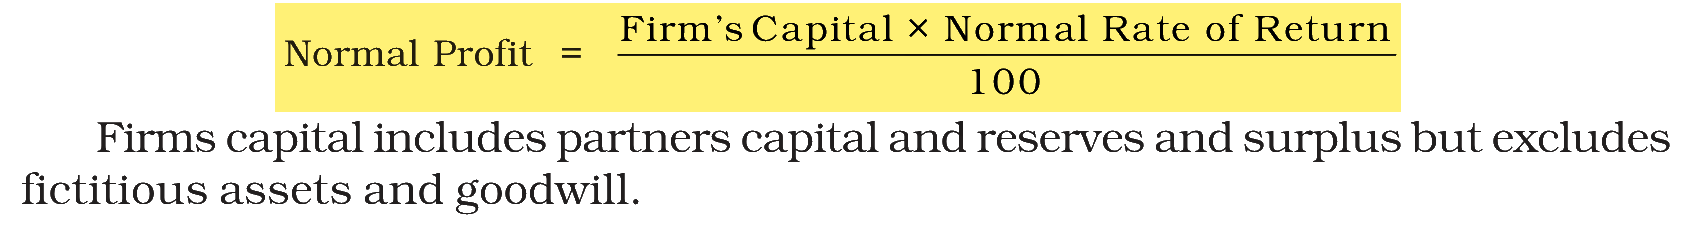
(B) Normal Profit — this matches (IV) (Capital Employed × Normal Rate of Return) / 100. It is the return a similar business would earn on the same capital.
(C) Goodwill — this matches (II) Super Profit × 100 / Normal rate of return. Under capitalisation of super profits, goodwill is the capitalised value of the super profits.
(D) Capital Employed — this matches (III) Total Assets - Outside Liabilities. Assets (other than goodwill and fictitious assets) less outside liabilities give the firm’s capital.
Note: The NCERT book prints the goodwill formula on one line without the division sign; it reads Goodwill = Super Profits × 100 / Normal Rate of Return.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|