CUETMOCK
  • Pricing
  • Mentors
Log inStart freeStart free mocks→

First test, then trust

Try a free CUET mock test.

Join 5,00,000+ students who rehearsed exam day on the exact NTA screen before sitting CUET. On the web and on Android.

Start free mocks →Get the Android app
CUETMOCK

India's #1 CUET Mock Test Platform. Original NCERT-based questions on the exact NTA exam screen — trusted by 5,00,000+ students since CUET 2022.

Get it onGoogle PlayScan to download the CUETMOCK app

Mock tests

  • CUET mock test series
  • Browse all papers
  • Commerce mocks
  • Humanities (Arts) mocks
  • Science mocks
  • Languages & GAT mocks
  • Free practice questions
  • Pricing

Resources

  • CUET exam guide
  • CUET syllabus
  • Universities accepting CUET
  • Expert blogs
  • News & notifications
  • Webinars & counselling
  • CUET score calculator
  • How we estimate your rank
  • FAQs

Company

  • About us
  • Our leadership & team
  • Our toppers
  • Mentors
  • For schools
  • Contact us
  • Terms
  • Privacy
  • Refund policy

Talk to us

+91 7696 6630 56info@cuetmock.comWhatsApp us

Our other platforms

  • JEE Mock — For IIT-JEE aspirants
  • NEET Mock — For NEET aspirants

Newsletter

Exam updates, study material and offers — no spam.

© 2026 NYC Ventures Pvt. Ltd.

701-702, Royal Business Park, Zirakpur, Punjab - 140603

  • Terms of use
  • Privacy policy
  • Refund policy
  • Contact us

iCUETMOCK is an independent preparation platform, not affiliated with the National Testing Agency (NTA). Always check exam details on the official NTA website.

  • Home
  • Mock tests
  • CUET guide
  • Pricing
  • Log in
Home/Practice questions/Accountancy Part A
Accountancy Part AAdmission of a Partner

The profits for the five years of a firm are as follows - year 2013 R…

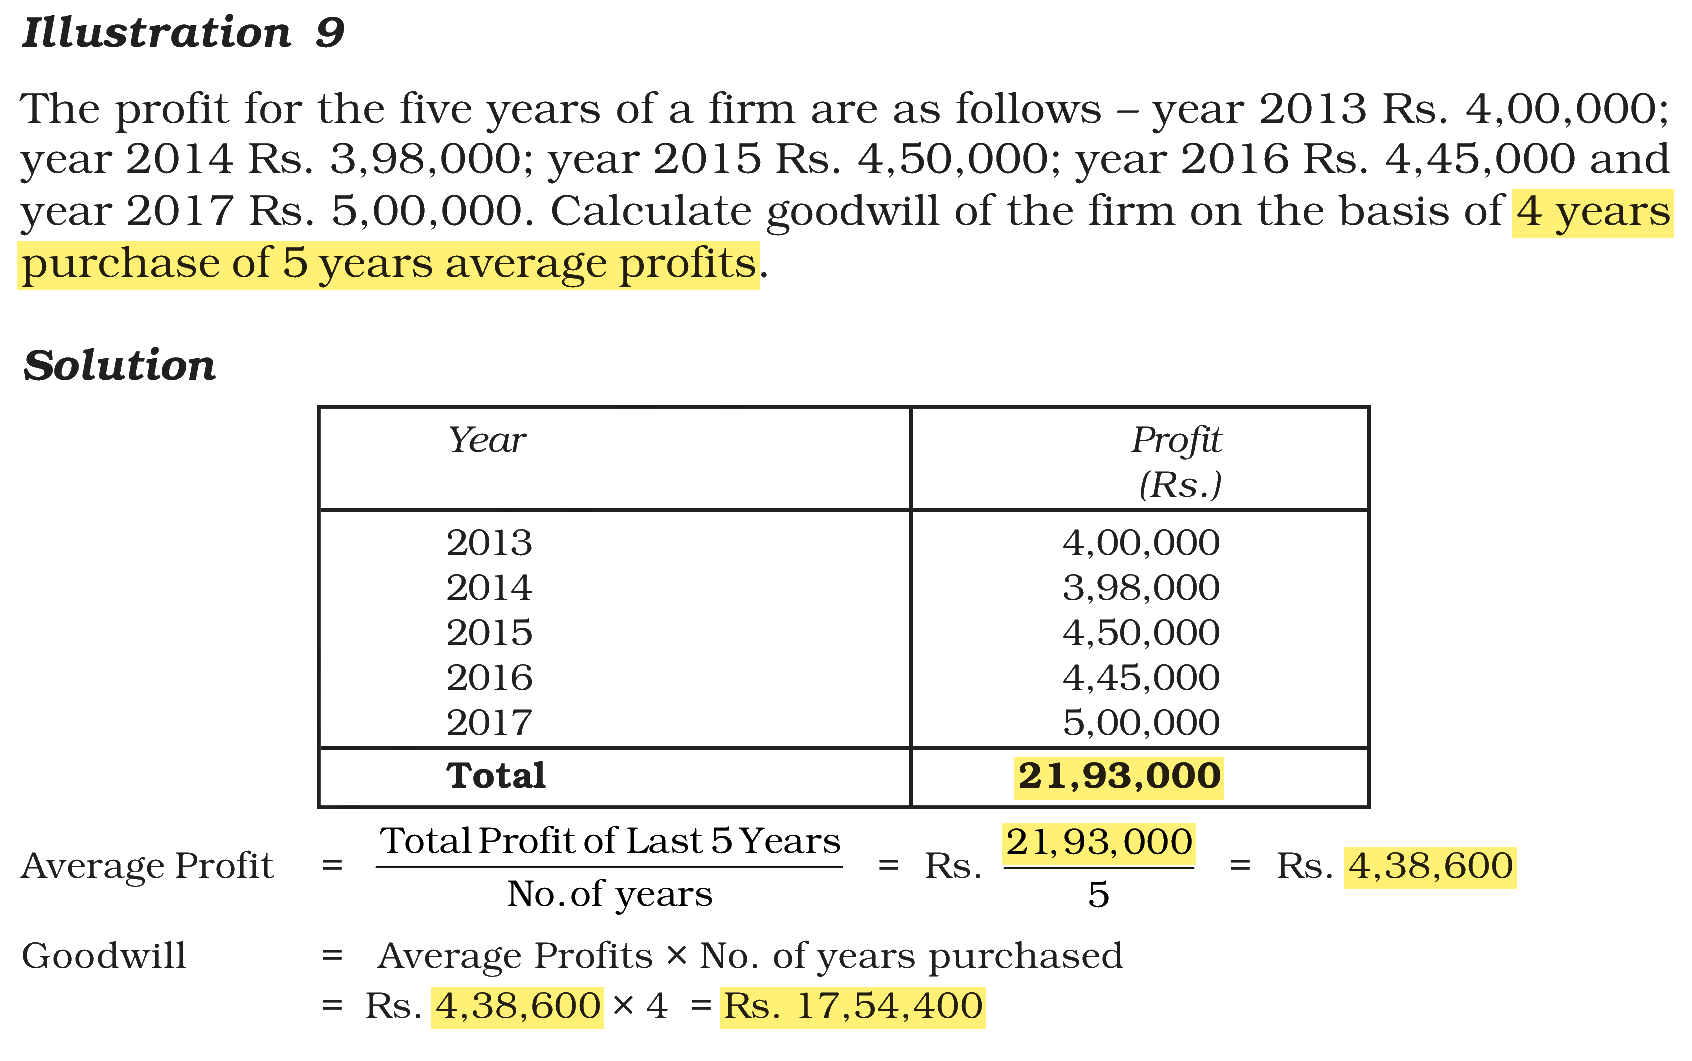
The profits for the five years of a firm are as follows - year 2013 Rs. 4,00,000; year 2014 Rs. 3,98,000; year 2015 Rs. 4,50,000; year 2016 Rs. 4,45,000 and year 2017 Rs. 5,00,000. Calculate the goodwill of the firm on the basis of a 4-year purchase of 5 years average profits:

Answer & explanation+

Correct answer: option 2

The correct answer is Option (2) → Rs. 17,54,400

Under the average profits method, goodwill = average profit × number of years’ purchase.

  • Total profit of 5 years = 4,00,000 + 3,98,000 + 4,50,000 + 4,45,000 + 5,00,000 = Rs. 21,93,000

  • Average profit = 21,93,000 / 5 = Rs. 4,38,600

  • Goodwill = 4,38,600 × 4 = Rs. 17,54,400

NCERT (2026-27 edition):
Average Profits Method

Extract from the NCERT textbook

Advertisement

Practise more on Admission of a Partner

Chapter-wise mocks on the real NTA exam screen, with solutions and your rank. Your first mocks are free.

Start free mocks →

Advertisement

Next questions

  1. In which of the following states / union territories has the Border Roads Organisation (BRO) constructed a 440-m-long tunnel to boost the C…General Aptitude Test · General Knowledge
  2. Social demography is the study of:Sociology · Indian Society: Demographic Structure of Indian Society
  3. Which of the following is not a feature of partnership as per Partnership Act 1932 ?Accountancy Part A · Accounting for Partnership
  4. Among five persons A, B, C, D and E, A is shorter than B. C is shorter than D who is taller than B and A is taller than E. C is shorter tha…General Aptitude Test · Verbal Reasoning
  5. नीचे दिए गए विकल्पों में से 'सामासिक पद और समास' का कौन-सा युग्म असंगत है?Hindi · व्याकरण - ससमास
  6. Sundaram Balachander has been the main player of which of the following musical instruments?General Aptitude Test · General Knowledge
  7. Let A be any square matrix of order 3 and B = […] . Then the matrix ABA^T is aMaths. Section A · Matrices
  8. 'किसी कथा के अंतर्गत आने वाली दूसरी कथा' को निम्नलिखित में से क्या कहते हैं?Hindi · वाक्यांशों के लिए एक शब्द
  9. What amendment was made in response to the ruling of the Allahabad High Court in the Indira Gandhi case?Political Science · Politics in India Since Independence: Crisis of democratic Order
  10. The value of ∫ 1/(x^n≤ft(1+x^n)^1 / n) d x,(n ∈ N), isMaths. Section B1 · Indefinite Integration