Match List-I with List-II.
| LIST I (Method of valuation of goodwill) |
LIST II (Formula) |
| (A) Average profit method | (I) Goodwill = Super profit x No. of years purchased |
| (B) Super Profit Method | (II) Goodwill = capitalized value of average profit - actual firm's capital |
| (C) Capitalization of super profit method | (III) Goodwill = Average Profits x No. of years purchased |
| (D) Capitalization of average profit method | (IV) Goodwill = (Super profit/ Normal Rate of Return) × 100 |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A)-(III), (B)-(I), (C)-(IV), (D)-(II)
Goodwill is valued either from the average profits or from the super profits (average profits less normal profits), by multiplying by the years’ purchase or by capitalising at the normal rate of return.
(A) Average profit method — this matches (III) Goodwill = Average Profits × No. of years purchased. The past average profit is multiplied by the agreed number of years’ purchase.
(B) Super Profit Method — this matches (I) Goodwill = Super profit × No. of years purchased. Only the profit above the normal profit is multiplied.
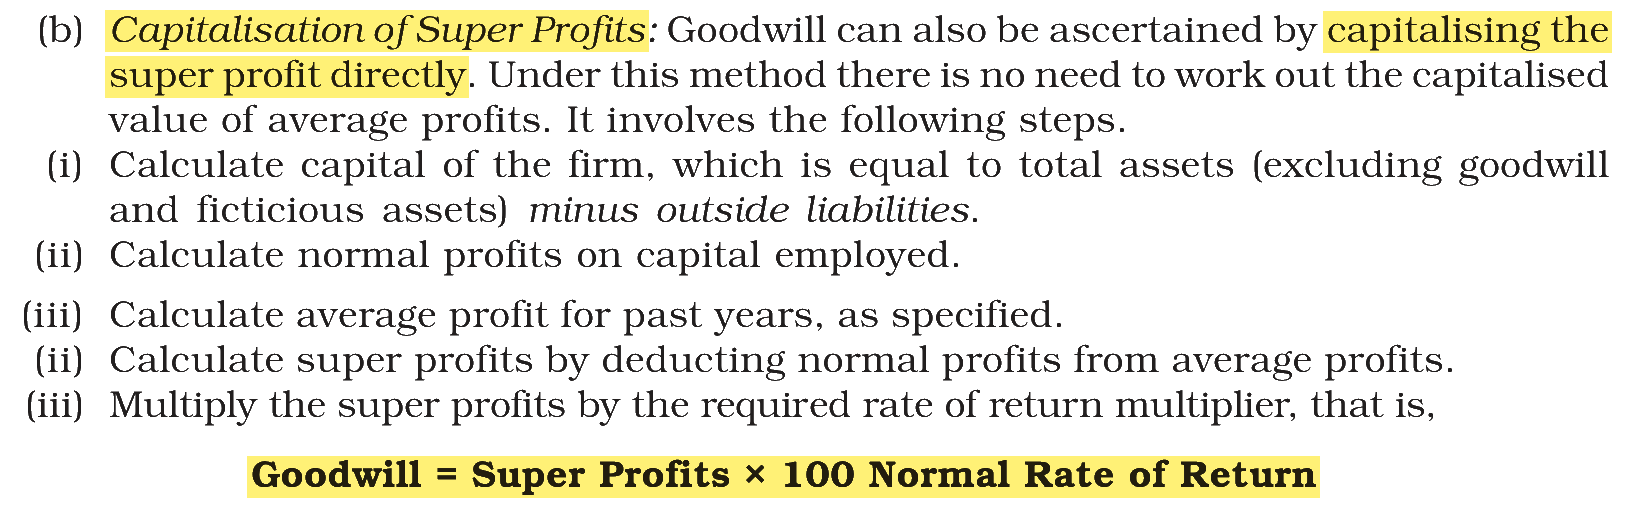
(C) Capitalization of super profit method — this matches (IV) Goodwill = (Super profit/ Normal Rate of Return) × 100. The super profit is capitalised directly at the normal rate.
(D) Capitalization of average profit method — this matches (II) Goodwill = capitalized value of average profit - actual firm’s capital. The average profit is capitalised first, and the net assets are deducted from it.
Note: The book’s formula line for capitalisation of super profits prints “Goodwill = Super Profits × 100 Normal Rate of Return” without the division sign; it should read Goodwill = Super Profits × 100 / Normal Rate of Return, as in (IV).
NCERT (2026-27 edition): NCERT (2026-27 edition): NCERT (2026-27 edition): NCERT (2026-27 edition):
|