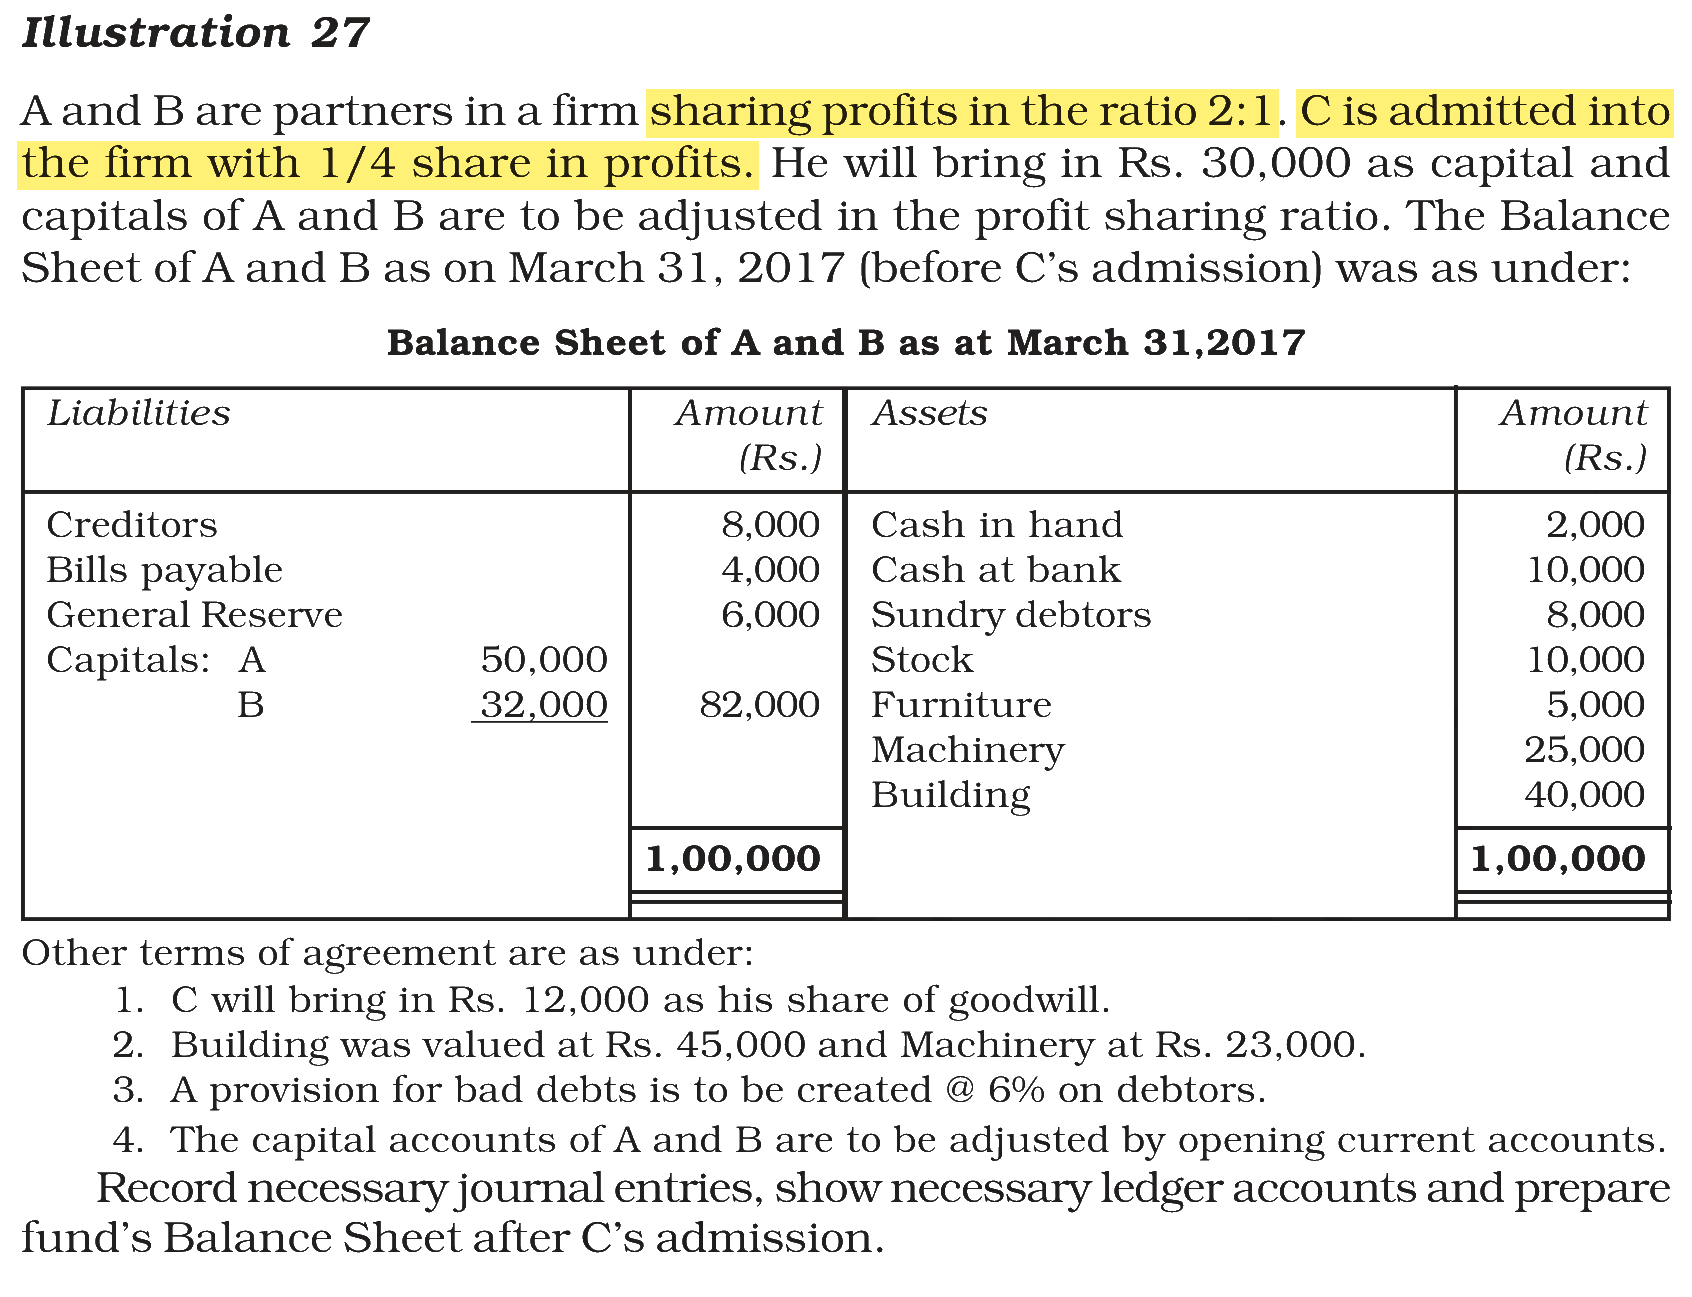
A and B are partners in a firm sharing profits in the ratio 2 : 1. C is admitted into the firm with 1/4 share in profits. He will bring in ₹30,000 as capital and capitals of A and B are to be adjusted in the profit sharing ratio. The balance sheet of A and B as on March 31, 2017 (before C's admission ) was as under :
Balance Sheet of A and B as at March 31, 2017
| Liabilities | Amount (Rs) | Assets | Amount (Rs) |
| Creditors | 8,000 | Cash in hand | 2,000 |
| Bills payable | 4,000 | Cash at Bank | 10,000 |
| General Reserve | 6,000 | Sundry Debtors | 8,000 |
| Capital : A 50000 B 32000 |
82,000 | Stock | 10,000 |
| Furniture | 5,000 | ||
| Machinery | 25,000 | ||
| Building | 40,000 | ||
| 1,00,000 | 1,00,000 |
Other terms of agreement are as under :
1. C will bring in ₹12,000 as his share of goodwill.
2. Building was valued at ₹45,000 and Machinery at ₹23,000
3. A provision for bad debts is to be created @ 6% on debtors.
4. The capital accounts A and B are to be adjusted by opening current accounts.
Calculate New Profit sharing ratio.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → 2 : 1 : 1
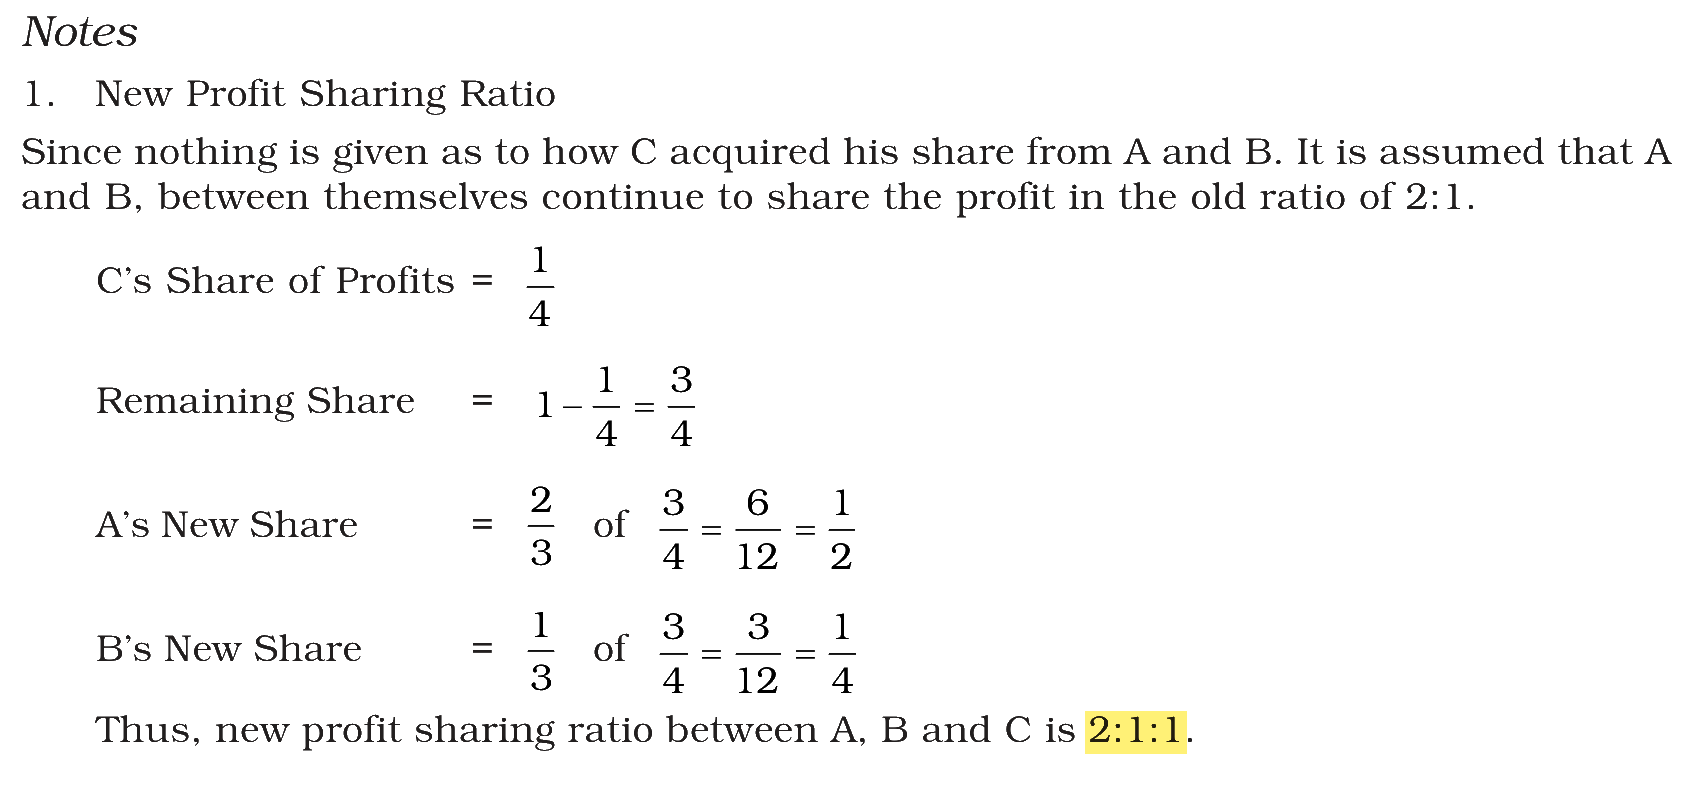
Nothing is said about how C acquires his share, so A and B are taken to give it up in their old ratio 2 : 1 and to share the rest in that ratio.
C’s share = 1/4
Remaining share = 1 − 1/4 = 3/4
A’s new share = 3/4 × 2/3 = 2/4
B’s new share = 3/4 × 1/3 = 1/4
New ratio of A, B and C = 2/4 : 1/4 : 1/4 = 2 : 1 : 1
NCERT (2026-27 edition):
|