Match List – I with List – II.
|
List - I |
List - II |
|
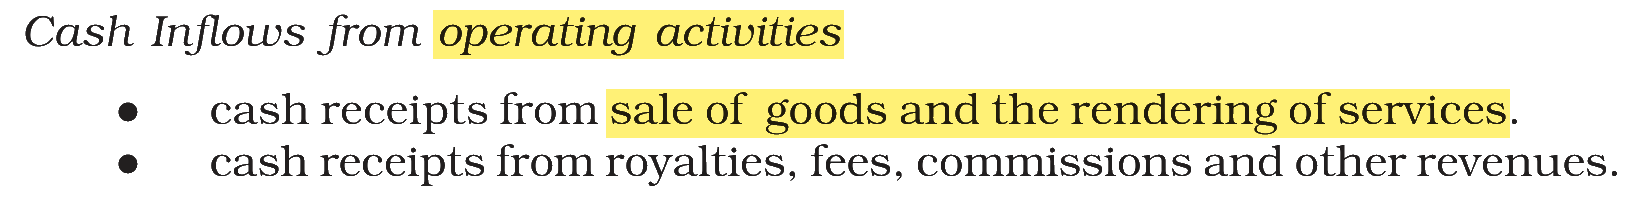
(A) Cash from Operating Activities |
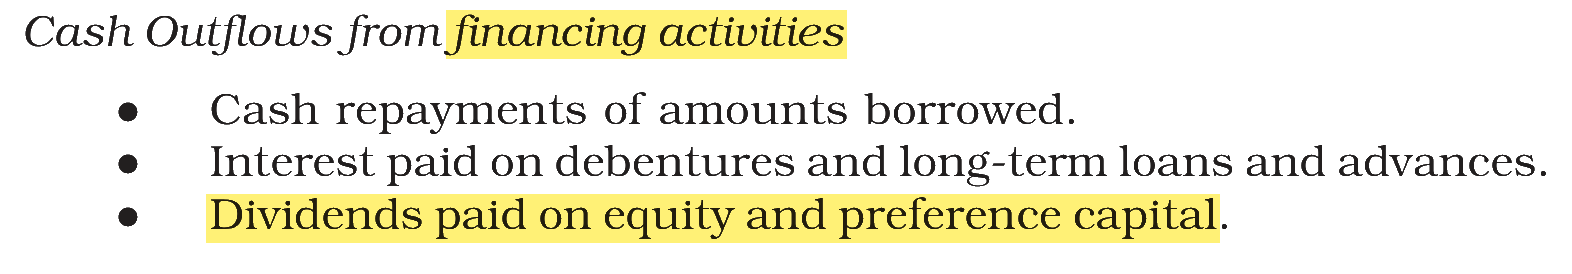
(I) Dividends paid on equity and preference capital |
|
(B) Cash from Financing Activities |
(II) Cash receipts from sale of goods and the rendering of services |
|
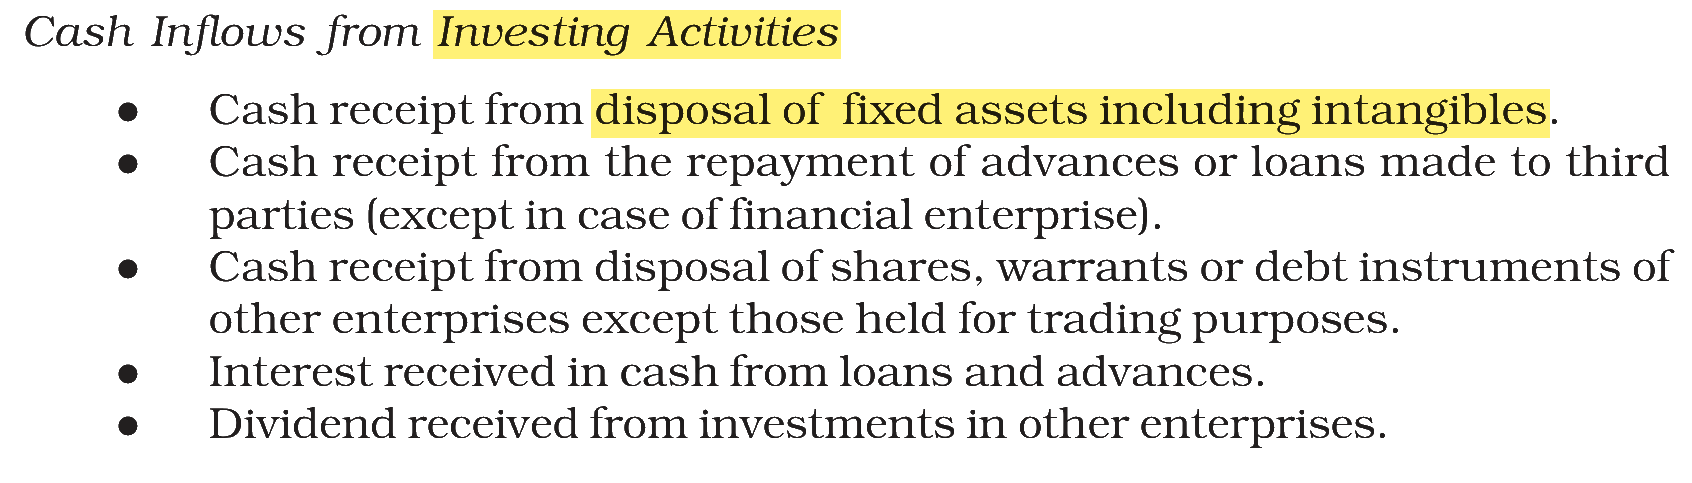
(C) Cash from Investing Activities |
(III) Bank balance |
|
(D) Cash and Cash Equivalents |
(IV) Cash receipt from disposal of fixed assets including intangibles |
Choose the correct answer from the options given below.
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A)-(II), (B)-(I), (C)-(IV), (D)-(III)
A cash flow statement sorts every cash receipt and payment by the activity that caused it: the main business (operating), long-term assets and investments (investing), and the firm’s own long-term funds (financing). Cash equivalents are the near-cash balances whose change the statement explains.
(A) Cash from Operating Activities — this matches (II) Cash receipts from sale of goods and the rendering of services. Selling goods and services is the main revenue-producing activity, so its receipts are operating cash inflows.
(B) Cash from Financing Activities — this matches (I) Dividends paid on equity and preference capital. Dividends are a return paid to the providers of capital, so they go out under financing.
(C) Cash from Investing Activities — this matches (IV) Cash receipt from disposal of fixed assets including intangibles. Buying and selling long-term assets is investing activity.
(D) Cash and Cash Equivalents — this matches (III) Bank balance. Cash includes cash in hand and demand deposits with banks, so a bank balance is part of cash itself.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition): |