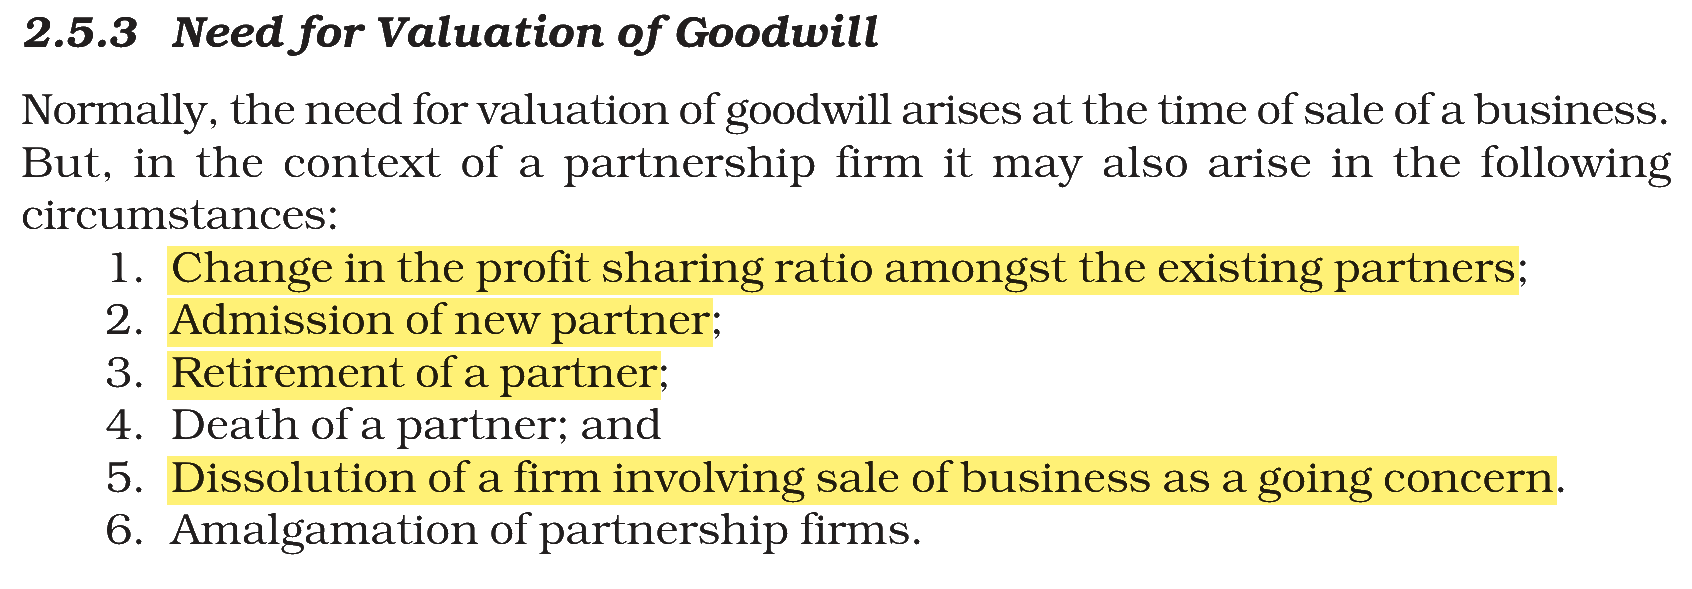
Consider the following facts about valuation of Goodwill of a partnership firm.
A. Goodwill valuation is done on change in profit sharing ratio among the existing partners.
B. Goodwill is valued on admission of a partner, to know the amount to be paid by him to compensate sacrificing partner (s).
C. Goodwill valuation is done on the retirement of a partner to know the amount to be paid to him as compensation for his sacrifice.
D. Goodwill valuation is done at the time of dissolution of a firm which involves sale of business as a going concern.
E. Goodwill valuation is done during the distribution of profits of the partnership firm.
Choose the correct answer from the options given below.
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → A, B, C and D only
A. Goodwill valuation is done on change in profit sharing ratio among the existing partners. — True. The gaining partners compensate the sacrificing partners.
B. Goodwill is valued on admission of a partner, to know the amount to be paid by him to compensate sacrificing partner (s). — True. His premium for goodwill is based on it.
C. Goodwill valuation is done on the retirement of a partner to know the amount to be paid to him as compensation for his sacrifice. — True. He is paid his share of goodwill.
D. Goodwill valuation is done at the time of dissolution of a firm which involves sale of business as a going concern. — True. The buyer pays for goodwill as part of the price.
E. Goodwill valuation is done during the distribution of profits of the partnership firm. — False. Profits are distributed every year in the agreed ratio; no change in partners’ rights takes place, so goodwill is not valued.
NCERT (2026-27 edition):
|