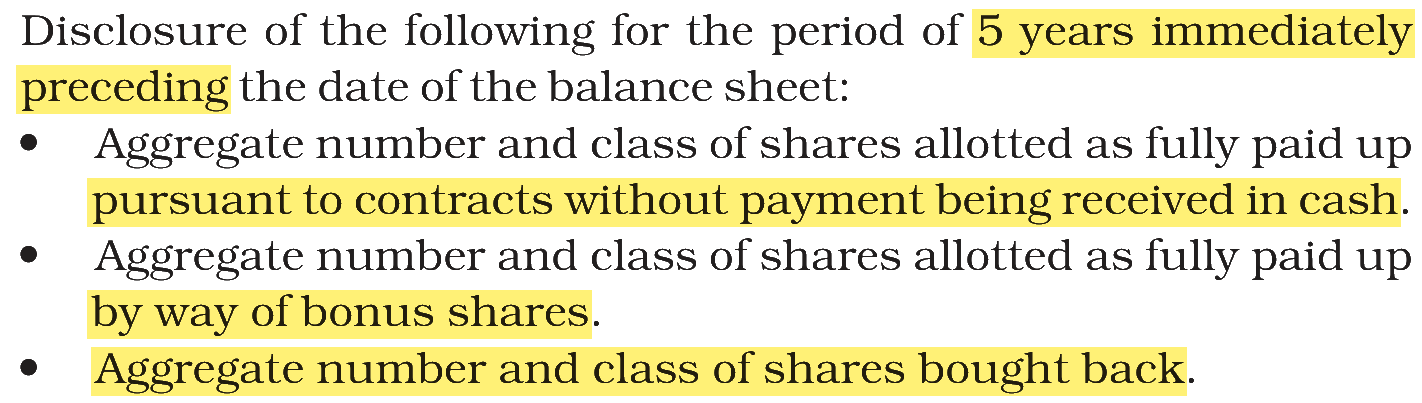
As per Companies Act-2013, Disclosure related to share capital is compulsory for a period of 5 years immediately preceding the date of Balance sheet:
A. Number and class of shares bought back
B. Number and class of shares allotted as fully paid up by way of bonus shares
C. Forfeited shares
D. Number and class of shares allotted as fully paid up pursuant to contract(s) without payment being received in cash
E. Calls unpaid (Aggregate)
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → A, B and D only
Under Schedule III, three items about share capital must be disclosed for the 5 years immediately preceding the balance sheet date: shares allotted for consideration other than cash, bonus shares, and shares bought back.
A. Number and class of shares bought back — True. It is one of the three 5-year disclosures.
B. Number and class of shares allotted as fully paid up by way of bonus shares — True. Bonus shares allotted in the last 5 years are disclosed.
C. Forfeited shares — False. Forfeited shares are a separate item of the share capital note for the current year, not a 5-year disclosure.
D. Number and class of shares allotted as fully paid up pursuant to contract(s) without payment being received in cash — True. It is one of the three 5-year disclosures.
E. Calls unpaid (Aggregate) — False. Calls unpaid are also a separate item of the share capital note, shown every year.
NCERT (2026-27 edition):
NCERT (2026-27 edition): |