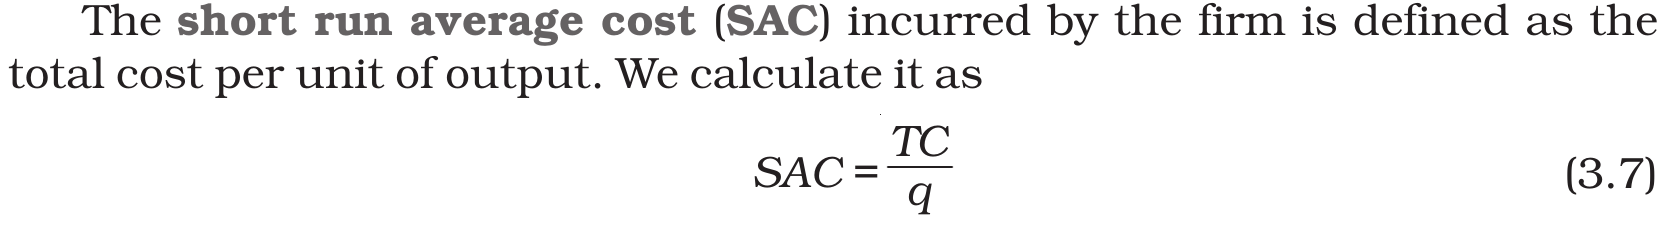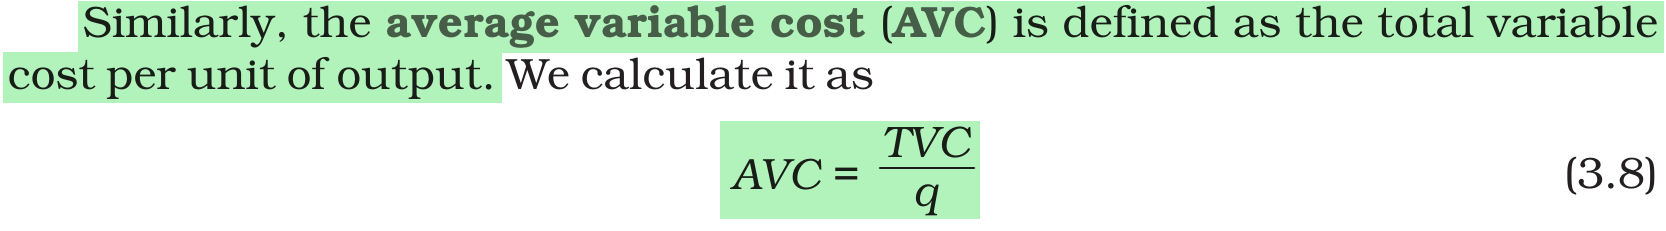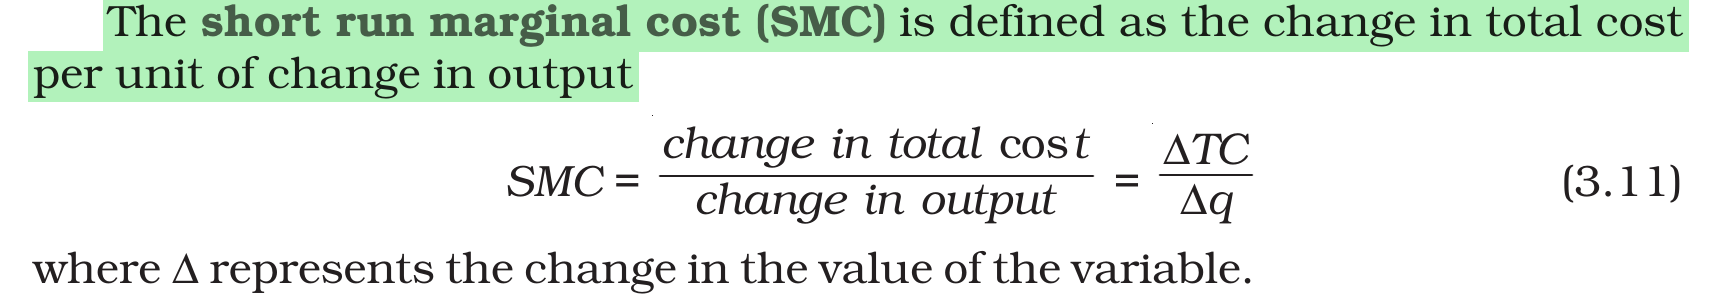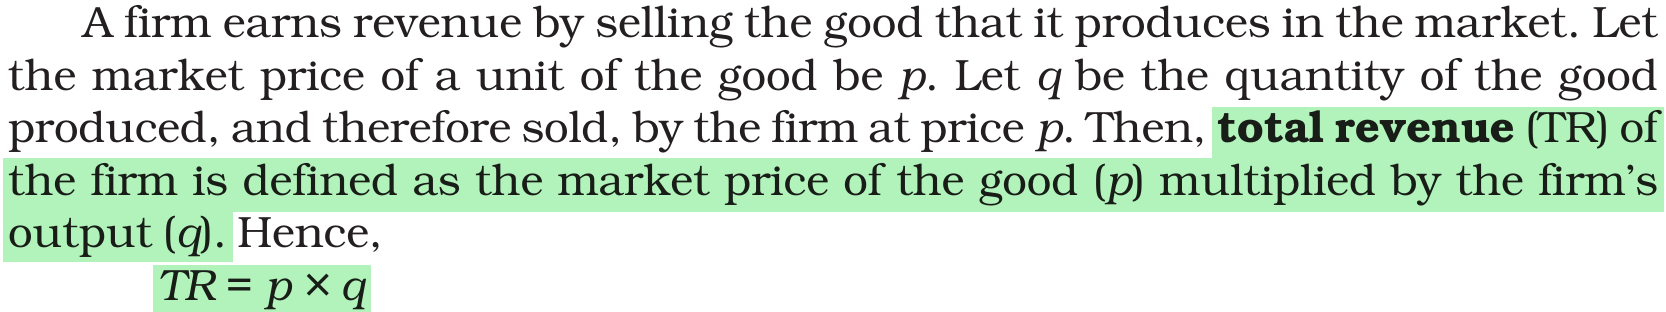Match List-I with List-II
| List-I | List-II |
| (A) Total variable cost | (I) TR – (TVC + TFC) |
| (B) Total Revenue | (II) TVCn - TVCn-1 |
| (C) Profit | (III) Average variable cost × Quantity |
| (D) Marginal cost | (IV) Price × Quantity |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A)-(III), (B)-(IV), (C)-(I), (D)-(II)
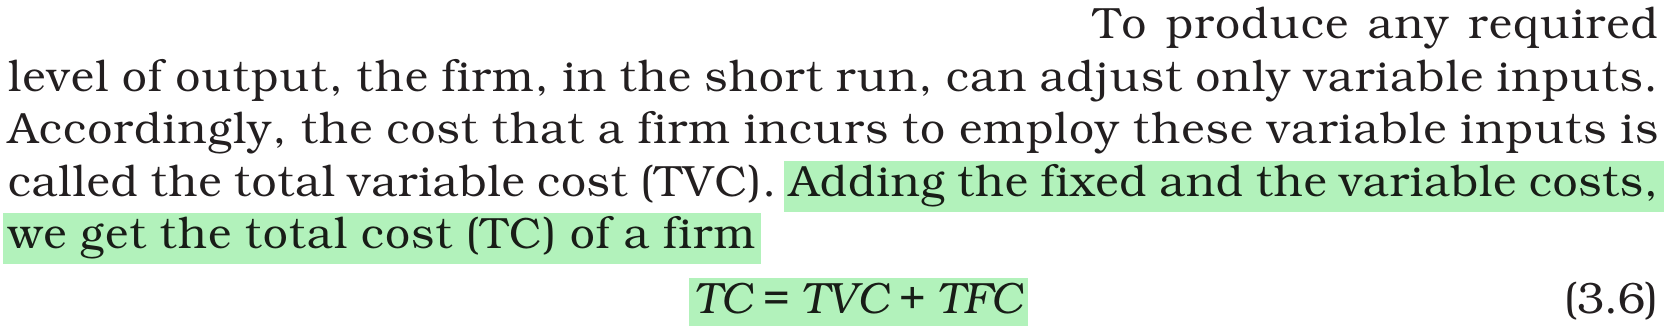
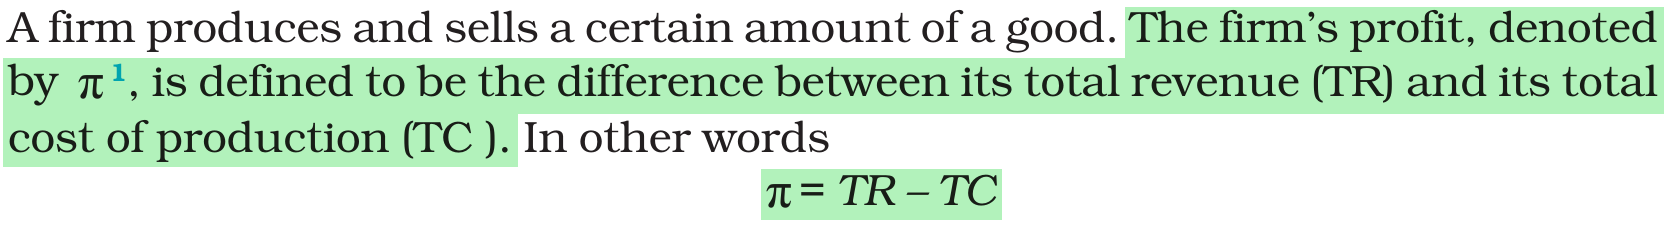
Costs and revenue are linked by a few simple formulas. Total cost is the sum of total variable cost (TVC) and total fixed cost (TFC). Profit is total revenue minus total cost.
| List-I | List-II | Reason |
|---|---|---|
| (A) Total variable cost | (III) Average variable cost × Quantity | AVC is TVC per unit of output (AVC = TVC/q). So AVC times quantity gives back TVC. |
| (B) Total Revenue | (IV) Price × Quantity | TR is the market price times the quantity sold. TR = p × q |
| (C) Profit | (I) TR – (TVC + TFC) | Profit is total revenue minus total cost, and total cost is TVC + TFC. |
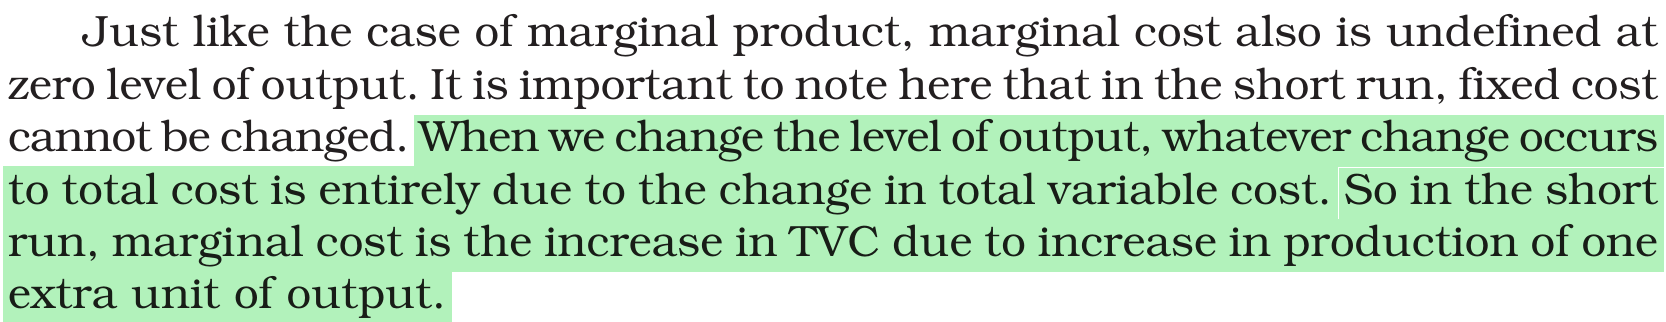
| (D) Marginal cost | (II) TVCn - TVCn-1 | MC is the change in total cost from one more unit. TFC does not change with output, so this equals the change in TVC. |
NCERT (2026-27): Introductory Microeconomics — Chapter 3: Production and Costs
NCERT (2026-27): Introductory Microeconomics — Chapter 4: The Theory of the Firm under Perfect Competition
|