Based on following Balance Sheet of Tarnav and Manav as at 31st March 2022, answer question:
Balance Sheet as at 31st March 2022
|
Liabilities |
₹ |
Assets |
₹ |
|
Sundry Creditors |
30,000 |
Cash at Bank |
13,000 |
|
80,000 |
|
80,000 |
On that date the firm was dissolved on the following terms:
(i) Tarnav promised to pay Sanjay's loan and took over stock in trade at ₹4,000.
(ii) Creditors, payable after one month, were paid immediately at a discount of 6% per annum.
(iii) Debtors of ₹1,000 proved bad, plant realised 130%.
(iv) Expenses on Realisation were ₹1,500 borne and paid by Manav.
(v) Manav took over an old computer completely written off from the book at ₹500.
Workman Compensation Reserve will be transferred to:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Credit side of Partners' Capital A/c
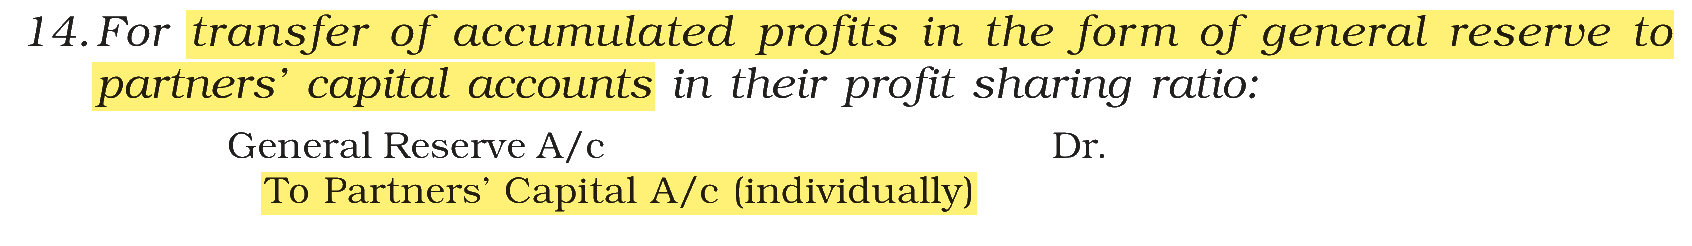
On dissolution, reserves are accumulated profits that belong to the partners. Like the General Reserve, the Workman Compensation Reserve (where no claim is outstanding, as here) is transferred to the credit of the partners’ capital accounts in their profit sharing ratio. It is not taken to the Realisation Account, which deals only with assets and outside liabilities.
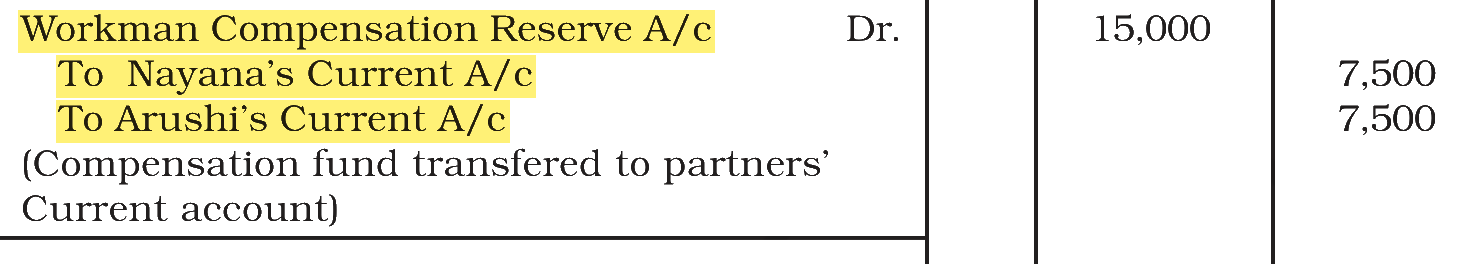
Workman Compensation Reserve A/c Dr. ₹12,000
To Tarnav’s Capital A/c ₹6,000
To Manav’s Capital A/c ₹6,000
(no ratio is given, so the profits are shared equally)
Option (2) Credit side of Realisation A/c — Incorrect. Only outside liabilities are credited to the Realisation Account; a reserve is the partners’ own profit.
Option (3) Debit side of Realisation A/c — Incorrect. The debit side of the Realisation Account takes assets, not reserves.
Option (4) Debit side of Partner's Capital A/c — Incorrect. Fictitious assets and accumulated losses are debited to the capital accounts; a reserve is a profit and is credited.
Note: In the book’s illustration the firm keeps fixed capitals, so the reserve goes to the partners’ current accounts; with fluctuating capitals, as in this firm, it goes to the capital accounts.
NCERT (2026-27 edition):
|