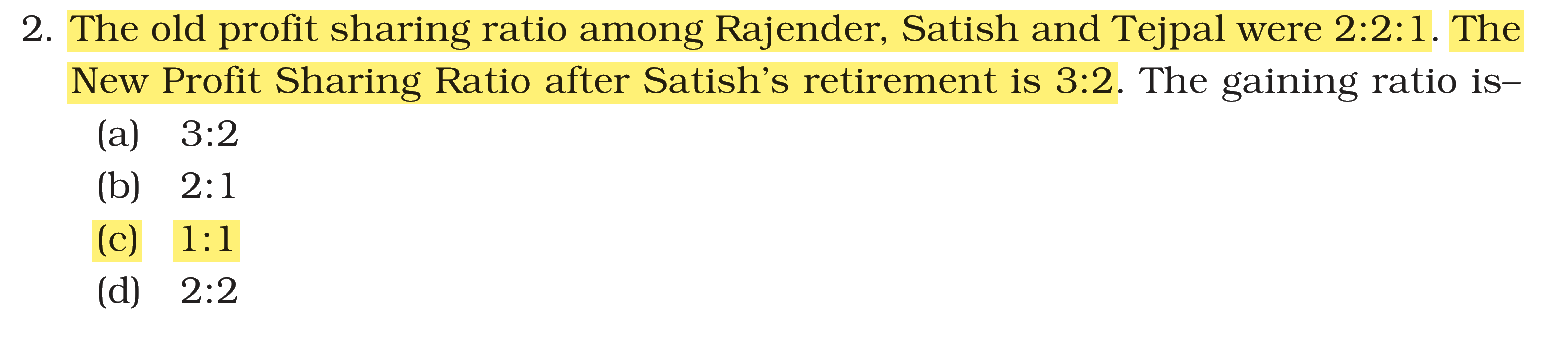
The old profit sharing ratio among A, B and C were 2 : 2 : 1. The new Profit sharing ratio after B's retirement is 3 : 2. The gaining ratio is-
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → 2 : 1
Note: The given answer is as per the official NTA Answer Key. However, the answer given by NTA appears to be incorrect, and the correct answer should be Option (3), as explained below.
The gaining ratio is the ratio in which the continuing partners acquire the retiring partner’s share. Gaining share = new share − old share.
Old shares: A = 2/5, B = 2/5, C = 1/5
New shares (3 : 2): A = 3/5, C = 2/5
A’s gain = 3/5 − 2/5 = 1/5
C’s gain = 2/5 − 1/5 = 1/5
Gaining ratio = 1/5 : 1/5 = 1 : 1
Option (1) 2 : 1 — The answer given by NTA, but it seems to be incorrect. A and C each gain 1/5 of the profit, so neither gains twice as much as the other.
Option (2) 3 : 2 — Incorrect. 3 : 2 is the new profit sharing ratio, not the ratio of the gains.
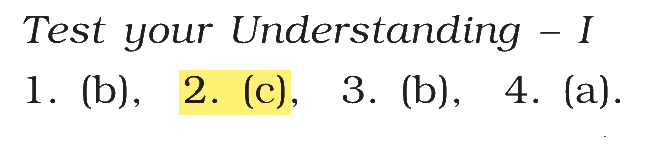
Option (3) 1 : 1 — Should be correct. Both gain 1/5, so the gaining ratio is 1 : 1; the NCERT book gives this same question with the answer (c) 1:1.
Option (4) 2 : 3 — Incorrect. It reverses the new ratio and has no link to the gains.
Advice for the exam: In the real exam, mark the answer that is correct as per accounting principles and the NCERT book. If NTA’s provisional answer key marks a different option, challenge it during the answer-key challenge window, giving proper reasoning. NTA does revise its key when a challenge is well justified, so a sound challenge can raise your marks.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|