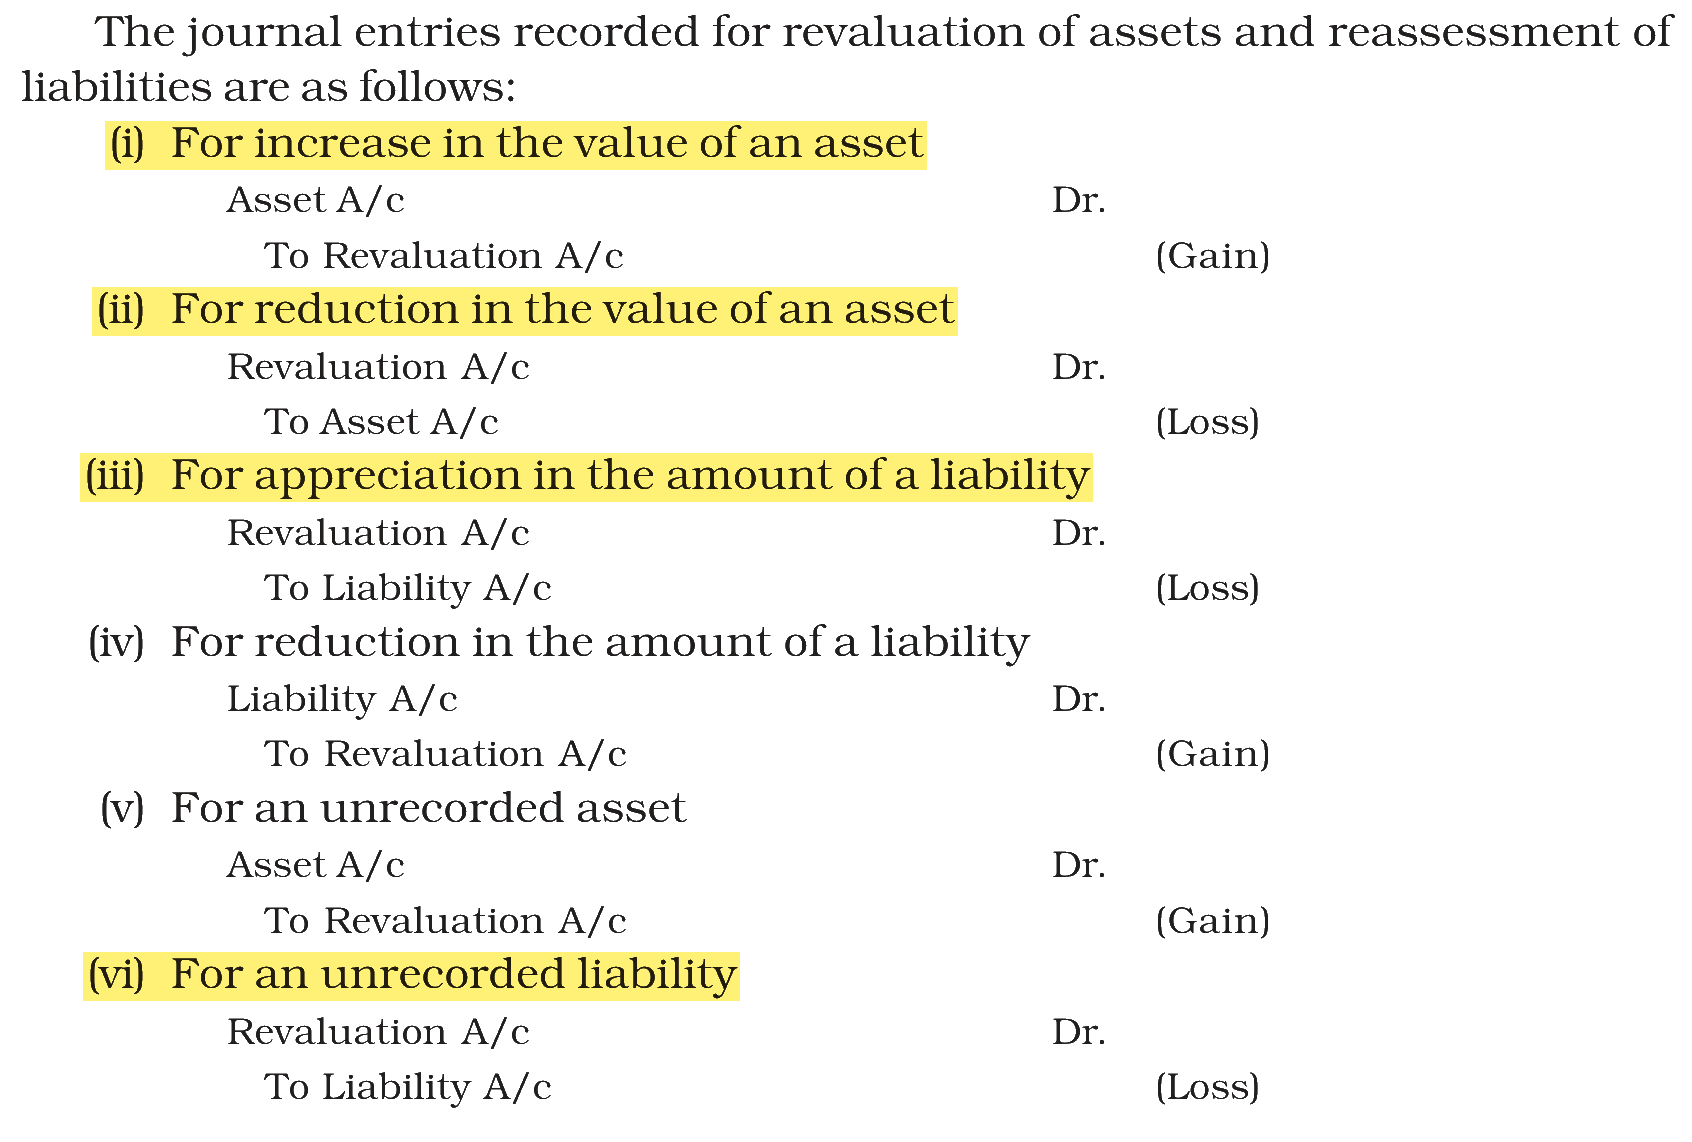
The journal entries recorded for revaluation of assets and reassessment of liabilities are given here, find the correct:
(A) For increase in the value of an asset-
Asset A/c Dr.
To Revaluation A/c
(B) For reduction in the value of an asset-
Revaluation A/c Dr.
Asset A/c
(C) For increase in the amount of a liability-
Liability A/c Dr.
To Revaluation A/c
(D) For recording in the amount of a unrecorded liability-
Revaluation A/c Dr.
To Liability A/c
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A), (B) and (D) only
The Revaluation Account is credited with every gain (a rise in an asset, a fall in a liability, an unrecorded asset) and debited with every loss (a fall in an asset, a rise in a liability, an unrecorded liability).
(A) For increase in the value of an asset — Asset A/c Dr. To Revaluation A/c Correct. A rise in an asset is a gain, so the asset is debited and the Revaluation Account credited.
(B) For reduction in the value of an asset — Revaluation A/c Dr. Asset A/c Correct. A fall in an asset is a loss, so the Revaluation Account is debited and the asset credited.
(C) For increase in the amount of a liability — Liability A/c Dr. To Revaluation A/c Incorrect. A rise in a liability is a loss. The entry is Revaluation A/c Dr. To Liability A/c; the entry printed is the one for a reduction in a liability.
(D) For recording in the amount of a unrecorded liability — Revaluation A/c Dr. To Liability A/c Correct. Bringing an unrecorded liability into the books is a loss, so the Revaluation Account is debited.
NCERT (2026-27 edition):
|