Match List I with List II
| List I | List II |
| A. Salary to partner | I. Credit side of Partner's Capital A/c |
| B. Interest on partner's loan | II. Debit side of Partner's Current A/c |
| C. Interest on partner's drawings | III. Debit side of Profit & loss A/c |
| D. Additional capital introduced | IV. Credit side of Partner's Current A/c |
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → A-IV, B-III, C-II, D-I
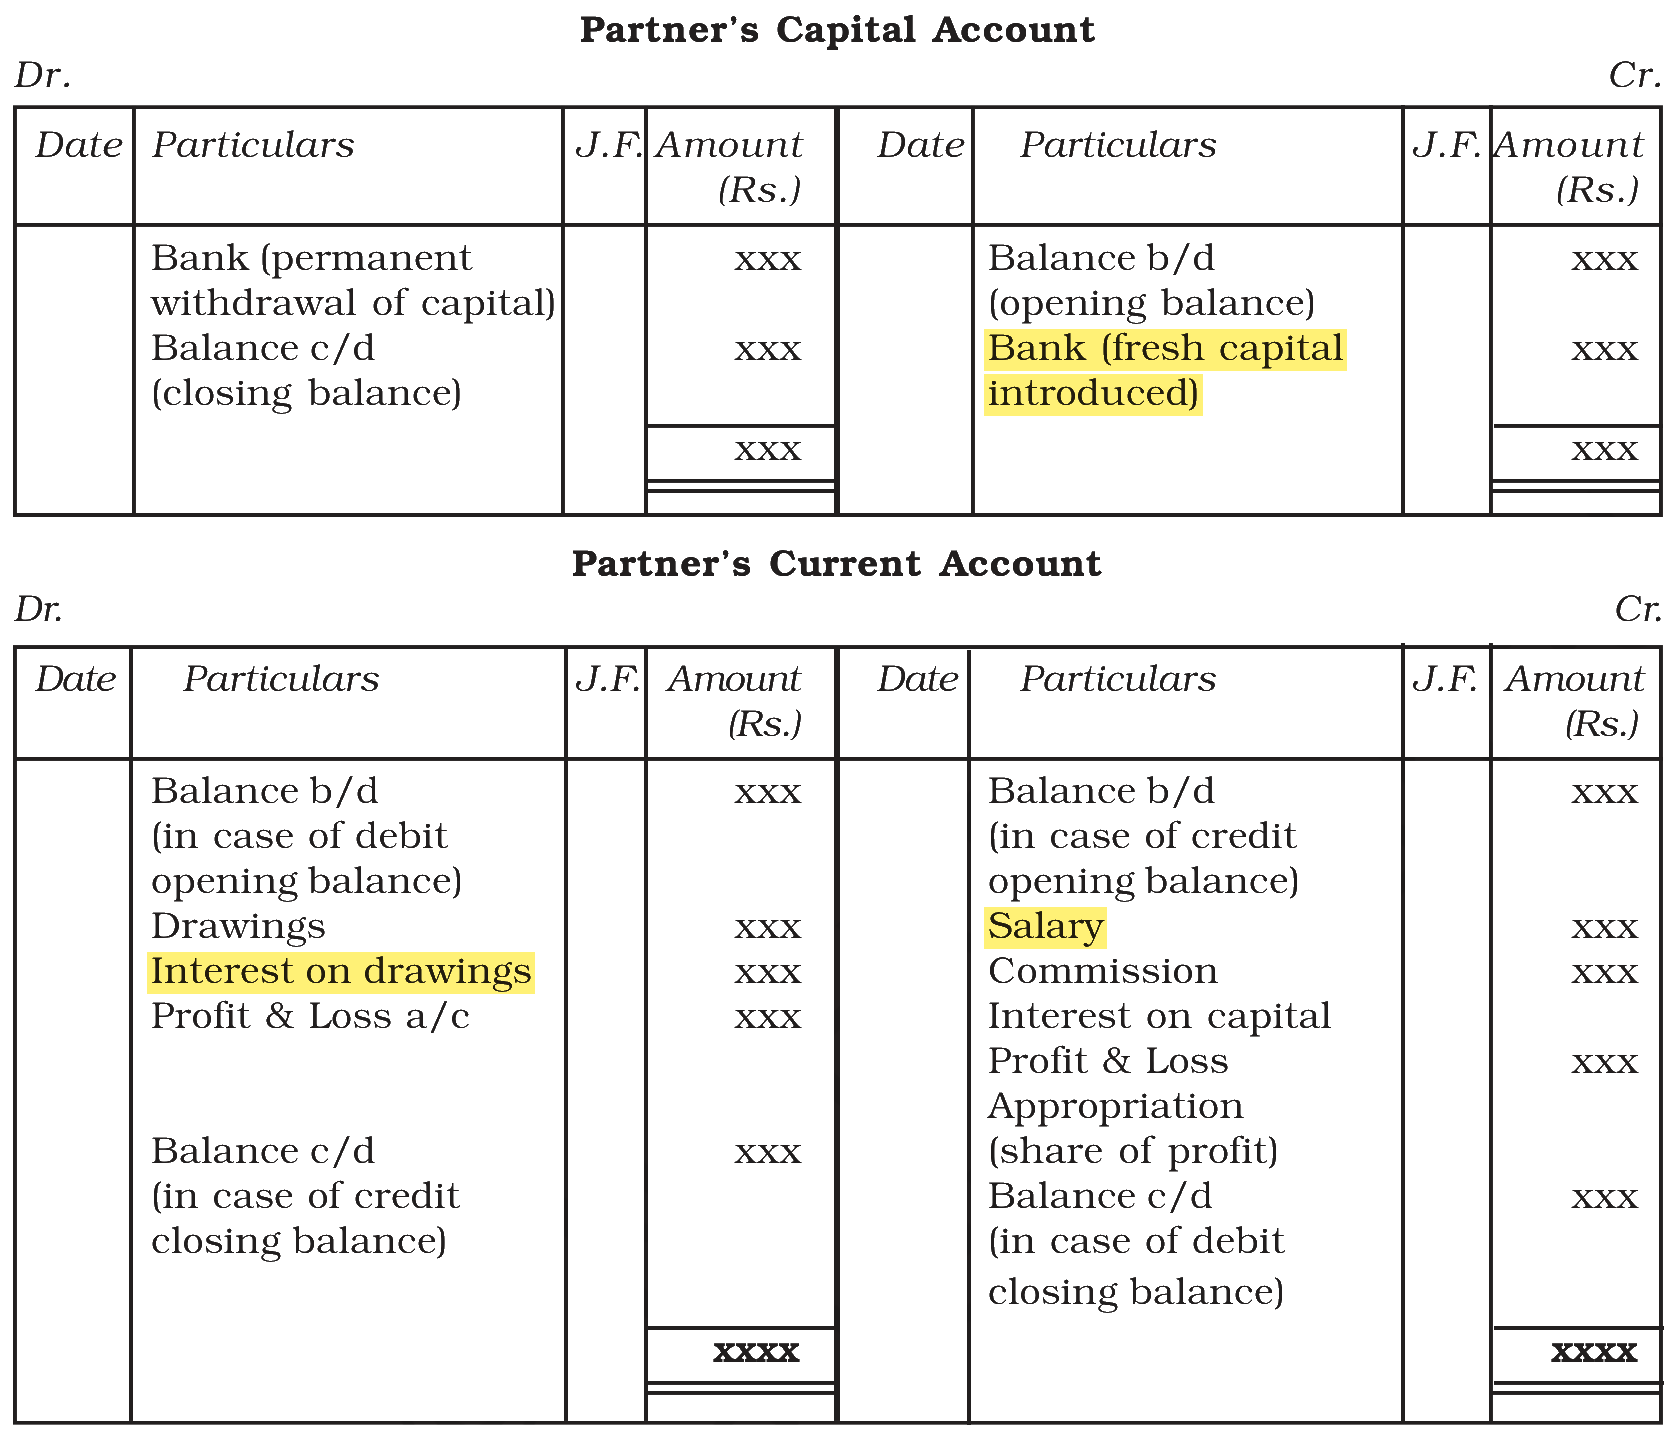
The match assumes the fixed capital method: the capital account records only capital put in or taken out, while all other dealings of a partner with the firm go to his current account.
A. Salary to partner — this matches IV. Credit side of Partner’s Current A/c. Salary is an appropriation of profit due to the partner, so his current account is credited.
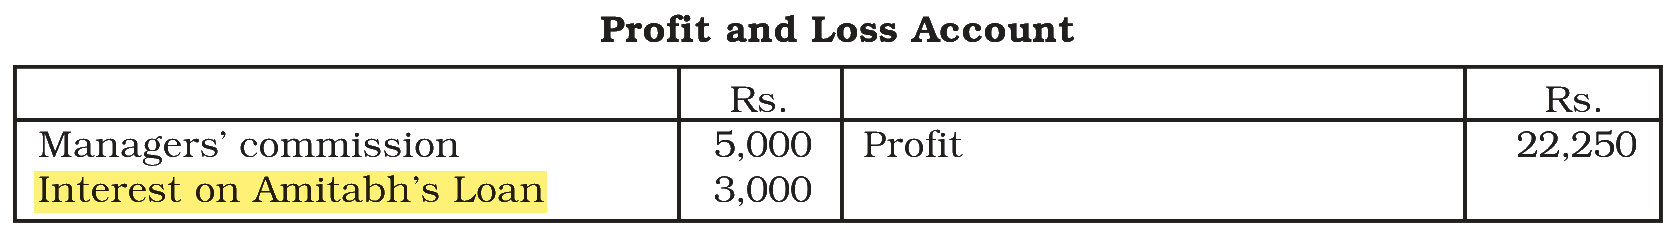
B. Interest on partner’s loan — this matches III. Debit side of Profit & loss A/c. A loan by a partner is a liability of the firm; its interest is a charge against profit, payable even in a year of loss.
C. Interest on partner’s drawings — this matches II. Debit side of Partner’s Current A/c. It is charged to the partner, so it reduces what he is owed.
D. Additional capital introduced — this matches I. Credit side of Partner’s Capital A/c. Fresh capital is the one item (besides withdrawal of capital) that changes the fixed capital account.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|